
Does Paying Off Loans Raise Credit Score
For many individuals, managing debt is a top priority, and paying off loans is a significant part of this process. Having a good credit score can make a huge difference in everyday life, from getting approved for a mortgage to securing a low-interest credit card. A good credit score can even affect the interest rates offered on loans, making it essential to understand how paying off loans impacts credit scores.
The primary purpose of paying off loans is to reduce debt and minimize the amount of interest paid over time. By doing so, individuals can free up more money in their budgets for other essential expenses, such as rent, utilities, and groceries. For example, suppose someone has a $10,000 loan with an interest rate of 6%. If they pay off the loan in 5 years instead of 10, they can save thousands of dollars in interest payments.
Paying off loans can indeed raise credit scores, as it demonstrates responsible debt management and a commitment to meeting financial obligations. When loans are paid off, credit utilization ratios decrease, and credit scores can increase as a result. This, in turn, can lead to better loan terms and lower interest rates in the future.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
To maximize the benefits of paying off loans, individuals should focus on high-interest debt first, such as credit card balances. By prioritizing these debts, they can save the most money in interest payments and make progress toward improving their credit scores. Additionally, making on-time payments is crucial, as late payments can negatively impact credit scores.
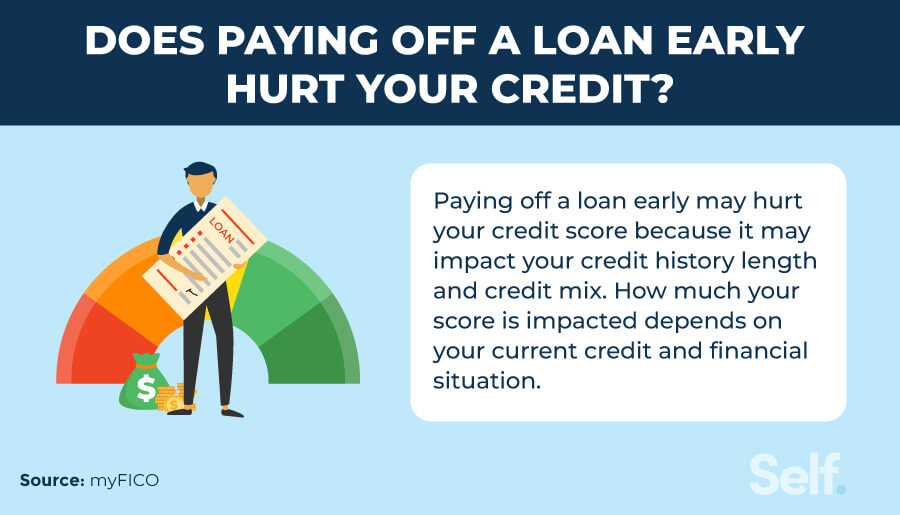
For those looking to explore this topic further, a few simple tips can be helpful. First, check credit reports regularly to ensure accuracy and detect any errors. Second, consider consolidating debt into a single, lower-interest loan to simplify payments and reduce interest rates. Finally, create a budget that prioritizes debt repayment and savings to achieve long-term financial stability.
By understanding the relationship between paying off loans and credit scores, individuals can take control of their financial lives and make informed decisions about their debt. With patience, discipline, and the right strategies, anyone can improve their credit score and achieve a more secure financial future.