
Is Help To Buy Worth It

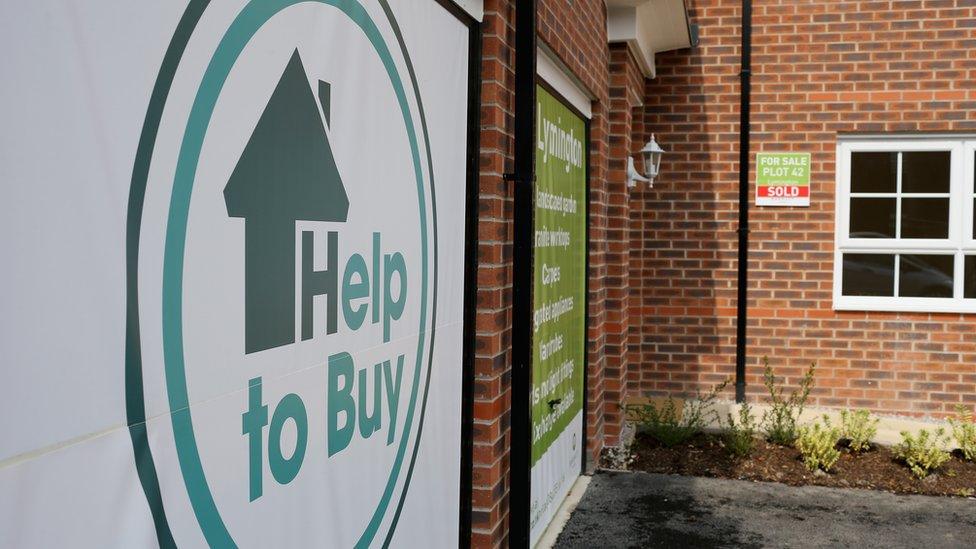
Okay, let’s be real for a second. You’ve seen those adverts, right? The ones with shiny new flats and people looking suspiciously happy while holding keys. That’s Help to Buy, the government’s little scheme to get you on the property ladder.
But is it actually a golden ticket, or just a slightly glittery loan that will haunt you later? Grab your coffee, and let’s hash this out like friends.
The “Free Money” Illusion
First off, it’s not free. I know, shocker. Help to Buy is essentially a loan from the government for up to 20% of the home’s value (or 40% in London, because everything costs a kidney there).
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
You only need a 5% deposit. That part feels amazing, like finding a twenty in an old coat. But the loan is interest-free for the first five years. Zero. Nada. That’s the sweet, sweet honey that lures you in.
After five years, fees kick in. And after five years, you start paying interest on that loan. That’s when the honey turns into a slightly awkward bill you forgot about.
The Big “But” About New Builds
Here’s the catch, and it’s a doozy. You can only use Help to Buy on a new-build home. Yes, that house that smells like fresh paint and has a dishwasher you didn’t earn yet.
New builds are expensive. Builders know you’re using this scheme, so they often jack up the price by 10-20%. It’s not a conspiracy, it’s just capitalism, baby.
So you might buy a flat for £300,000. But its real value? Maybe £250,000. You’re immediately in negative equity if the market sneezes. Yikes.
The Staircase of Doom (Or Opportunity)
You have to “staircase” your way out. That means buying back chunks of the government’s 20% loan over time. Unless you plan to sell, of course.
If you sell, you have to pay back 20% of the current market price. Not what you paid, not what you owe. The current price. If your house goes up in value? You owe more. That’s a bitter lemon to swallow.

On the flip side, if the market tanks? You win. You pay back less. It’s a weird gamble on the housing gods.
The Deposit Trick You Need to Know
The real magic of Help to Buy is the 5% deposit. Without it, you’d need 10-15% down. For many of us, that’s the difference between “maybe in a decade” and “I can move next spring.”
That 5% gets your foot in the door. Literally. But remember, you still need a mortgage for the other 75-80%. Rates on those are spicy right now, like a jalapeño you didn’t expect.
Your monthly payments might be higher than renting. Wait, higher than renting? Yes. It happens. Don’t assume ownership is cheaper. It’s just… yours.
The “Lifestyle” Upgrade Myth
Let’s talk about your social life. You buy a shiny new flat in a development called “The Apex” or “Sky View.” It has a gym that smells like regret.
But that flat is tiny. Developers squeeze rooms like you’re in a clown car. You might have a “study” that can fit a laptop and a houseplant, but not both at once.
You’re paying a premium for new carpets and a warranty. Meanwhile, your friend with a 1930s terrace has actual space and a garden. Who’s laughing now?
The Emotional Math
Here’s the part no one puts in a spreadsheet: security. When you own, no landlord can kick you out because they “found a family member.” You can paint a wall neon pink if you want.
That peace of mind is worth something. But so is the stress of a variable interest rate and a 20% loan hanging over your head like a cartoon anvil.
Help to Buy is a tool, not a miracle. It’s like a power drill. Great if you need to put up shelves. Terrible if you try to use it as a hammer.
The Final Verdict (With Extra Sugar)
Is it worth it? I’ll say this: It is if you can afford the payments and you plan to stay put for 5+ years. If you flip houses like pancakes, skip it. The fees will eat you alive.
It’s also great if you have a solid income but zero savings. That 5% deposit is a lifesaver. It’s a bridge over the “I can’t afford a deposit” river.
But if you’re buying in a city with falling prices? Run. Don’t walk. Negative equity is a monster that loves new-build owners.
So, grab another coffee. Chat with a mortgage broker. Not the one your dad uses, a real one who actually listens.
Help to Buy is a bit like that friend who offers you a ride but then asks for gas money. It’s helpful, but it’s never free. And that’s the real tea.
Now go enjoy your overpriced latte. You’re going to need it before signing any papers.