
Buy Now Pay Later Just Eat
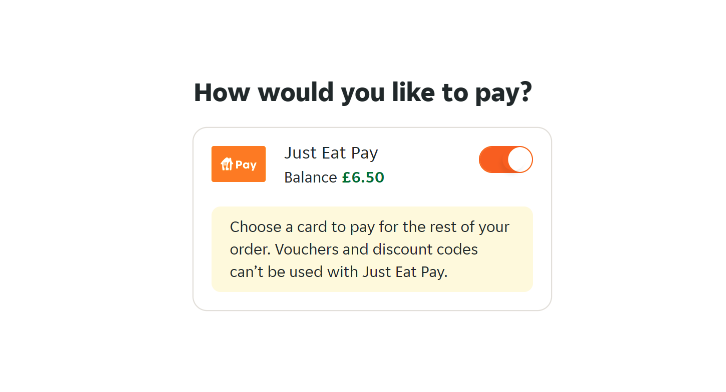
So there I was, on a Tuesday night, stomach growling louder than my dignity. I had exactly £4.73 in my account—enough for a sad bag of crisps, but not the large pizza with extra pepperoni I was craving. Then, like a greasy miracle, Just Eat popped up with an offer: Buy Now, Pay Later. I clicked. I ordered. I became the proud owner of a pizza I technically couldn't afford yet.
The seductive illusion of "future me" paying for it
That’s the magic of BNPL, isn’t it? It lets you pretend future you is a rich, responsible adult who’ll handle the mess. Right now, you’re just a hungry, impulsive creature who deserves that dessert. (And honestly? Future me is still mad about it, but at least present me was full.)
The system is dangerously smooth. You add your food, pick “Pay later,” and—bam—dinner is on its way. No credit card details, no guilt, just glorious instant gratification. But let’s be real: that £25 curry you bought last week? It’s now a tiny ghost haunting your bank account.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
How it actually works (and why you shouldn't ignore it)
Just Eat partners with services like Klarna or Clearpay, splitting your total into four interest-free payments, due every two weeks. Sounds harmless, right? Until you realize you’ve ordered takeout three times this week, and suddenly you owe £60 for kebabs you barely remember eating. (I’m talking to you, 2 AM doner wrap person.)
The trap is psychological. Because the first payment is tiny—say, £5—your brain thinks, “Oh, that’s nothing!” But you’re stacking those tiny payments like Jenga blocks. One missed payment? Late fees. Or worse, a ding on your credit score. (Yes, some BNPL services report to credit bureaus now.)
The convenience that eats your budget
Let’s be honest: BNPL for food is comically risky. We’re talking about a product that disappears in 20 minutes. You’re financing something that literally becomes waste. But the convenience? Oh, it’s addictive. I now have a habit of ordering sushi without checking my balance, and future me is just shaking their head.

What’s fascinating is why we do this. It’s not just hunger—it’s the feeling of control. BNPL gives us back choice when money feels tight. But it’s a false choice, because you’re just borrowing from yourself later. (And later you’ll be broke, eating instant noodles, wondering where your pizza money went.)
The fine print nobody reads (until they cry)
I’ll admit: I never read the terms. Who does? But here’s the thing: most BNPL services for Just Eat charge late fees around £5–£15 per missed payment. That’s basically adding a second meal’s cost to your first. And if you’re really unlucky, they’ll pass your debt to a collection agency. For a burrito. A burrito.
There’s also the invisible debt spiral. You buy dinner on BNPL, then see a new offer for lunch the next day. “Oh, it’s only £3 now,” you think. Next thing you know, you’re juggling four plans across different apps. Your phone screen becomes a minefield of IOU notes.
When it’s actually a good idea (rare, but possible)
Look, I’m not here to judge. Sometimes life is chaos. Maybe your paycheck is delayed, or your fridge went empty after a power cut. In those emergency moments, BNPL on Just Eat can be a lifeline. I used it once when I was sick and couldn’t cook, and it saved me from eating dry crackers. (Thank you, Klarna, you beautiful vulture.)
But here’s the rule: only use it for planned splurges, not daily habits. If you’re buying a £8 pizza because you’re tired, you’re playing with fire. If you’re buying a £40 family meal for a celebration? Okay, that feels safer—still risky, but less absurd.
My final, slightly shaky advice
I still use BNPL for takeout. I’m a hypocrite, and I know it. But I’ve learned to treat it like a credit card: pay off the full balance as soon as I can. No excuses, no “next paycheck” promises. (Because future me is a liar.)
Also, set a limit. For me, it’s two BNPL orders per month—max. After that, I have to use real money or starve with dignity. It’s a silly rule, but it works. Automate reminders, or better yet, link Just Eat to a separate “fun money” account. (Bonus: if you link a debit card with zero overdraft, the app literally can’t let you overspend. Sweet, painful self-control.)
So next time you’re eyeing that “Pay in 4” button for a double cheeseburger, ask yourself: Do I need this memory I’ll excrete tomorrow? Probably not. But if you do click it—enjoy every bite, and pay it off before the burp fades. Your future self will thank you. Eventually.