
How To Get A Large Mortgage
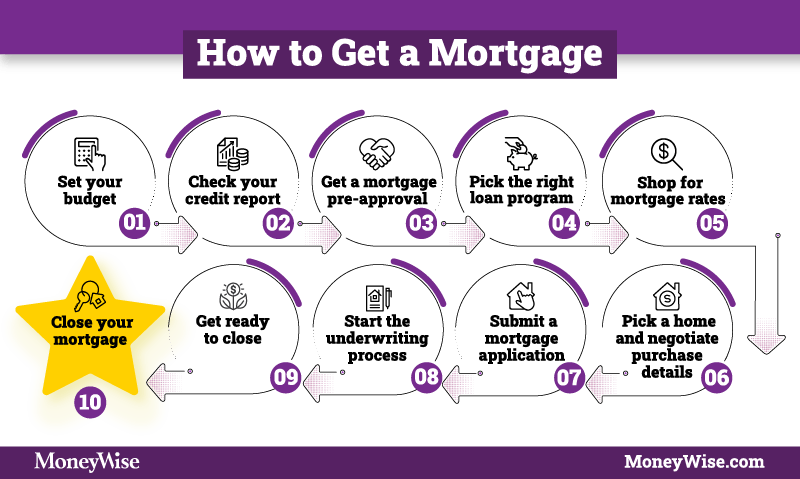
So, you want a large mortgage. Not just a “cozy cottage” loan, but a sprawling estate loan. The kind where your mailbox gets its own zip code. Good news: it’s possible. Bad news: you’ll need to charm bankers like a magician charms a cobra. Let’s dive in.
Step 1: Get a Job That Screams “I Eat Bankers for Breakfast”
Banks love stability, but they really love giant piles of cash. If you’re a brain surgeon who also owns a chain of laundromats, perfect. If you’re a freelance mime, maybe not. The rule is: show a consistent two-year history of income that makes a banker’s eyes water. Pro tip: if your W-2 looks like a phone number, you’re in the club.
Self-employed? You’ll need tax returns that prove you’re not a hobo in a suit. Lenders will scrutinize your deductions. That “business trip” to the Bahamas? They don’t care if it was fun. They care about your net income. So, calculate your adjusted gross income like a hawk—or hire an accountant who eats calculators for breakfast.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Step 2: Your Credit Score Must Be a Unicorn
You want a 800+ credit score. Why? Because that unlocks the secret handshake of jumbo loans. A 620 gets you a cardboard box. An 800 gets you a house with a ballroom. Surprising fact: nearly 30% of Americans have a sub-600 score, so by aiming for 800, you’re already in the top-tier of financial wizards. Fix your credit by never missing a payment, and maybe sacrifice a goat to the credit bureau gods. (Joking. But do pay your bills on time.)
Quick Credit Hacks:
Don’t open new cards before applying. It screams “I’m desperate and shopping.” Also, keep your credit utilization under 30%. If you have a $10,000 limit, never owe more than $3,000. Even better? Pay off your balance every month like a responsible adult—or a superhero.
Step 3: The Down Payment Isn’t a Down Payment; It’s a Statement
You want 20% down to avoid Private Mortgage Insurance (PMI). But for a large mortgage—say, $1 million—that’s $200,000 in cash. That’s not spare change; that’s a small car collection. But here’s the twist: some jumbo loans only require 10% down if your credit and income are stellar. It’s like a VIP pass to the debt party. Just know that with less down, your monthly payment becomes a comedy show—funny until you see the bill.
If you don’t have the cash, consider a gift from family. But the bank will ask: “Is this a loan? Is it a gift? Are you laundering money?” They’ll demand a letter saying your Aunt Karen truly loves you and expects nothing in return—except maybe a holiday card.

Step 4: The Debt-to-Income Ratio: The Bocce Ball of Lending
Lenders want your monthly debts (car, student loans, credit cards) to be under 43% of your gross income. For a huge mortgage, aim for 36% or lower. That means if you earn $20,000 a month (ha, we can dream), your total payments should stay under $7,200. Not too shabby, but remember: that includes the mortgage payment itself. So that $7,200 gets eaten quickly by a $5,000 mortgage plus your Porsche loan. Do the math before you fall in love with a mansion.
Fun fact: In 1980, the average mortgage payment was 21% of income. Today, in many cities, it’s over 40%. You’re basically playing a game of financial Tetris. Make sure your blocks fit.
Step 5: Bring a Tome of Paperwork (Literally)
To get a massive loan, you need to prove you exist. Bring two years of tax returns, W-2s, bank statements, pay stubs, and a blood sample. Okay, no blood sample, but they might ask for your pet’s vet records. Seriously, gather everything. Lenders fear gaps in documentation more than vampires fear crosses. If you had a mysterious $5,000 deposit from “random check,” expect a forensic audit of your life. Be transparent: “That was from selling my collection of signed baseball bats.” They’ll nod. They might not believe you, but they’ll accept it.
Pro Tip: Pre-Approval Is Your Wingman
Get pre-approved before house hunting. It shows you’re serious. A pre-approval letter from a local bank is like a golden ticket. But remember: pre-approval isn’t final. The underwriter will later dissect your soul. They might ask why you visited a casino in 2019. Just say you were on a business trip to research “alternative investments.” They’ll love that.

Step 6: The Jumbo Loan Secret—Rates Are Actually Lower (Sometimes)
Here’s a shocker: jumbo loans often have lower interest rates than conventional loans. Why? Because rich people are less likely to default. Banks know if you’re borrowing $750,000+, you’ve got skin in the game. So shop around. Don’t just go to one bank. Hit up credit unions, online lenders, and your uncle’s friend who’s a mortgage broker. Compare rates like you’re checking avocado prices at three different stores.
And negotiate. Yes, you can haggle. Ask for a rate reduction or for them to waive origination fees. They might say no. But if you have a thick neck and a big smile, they might say yes. Worst case, they think you’re slightly annoying but rich. Win-win.
The Bottom Line: It’s a Circus, But You Can Be the Ringmaster
Getting a large mortgage isn’t rocket science; it’s just a high-stakes game of “Prove You’re a Responsible Adult.” Keep your credit shining, your income flowing, and your paperwork tidy. Don’t panic when the banker asks for your mother’s maiden name and the name of your first pet. It’s all part of the dance. And if all else fails, just marry a billionaire. (Kidding. Mostly.)
Now go forth and borrow responsibly. Your mega-mansion with a moat awaits.