
How Long To Fix Mortgage For
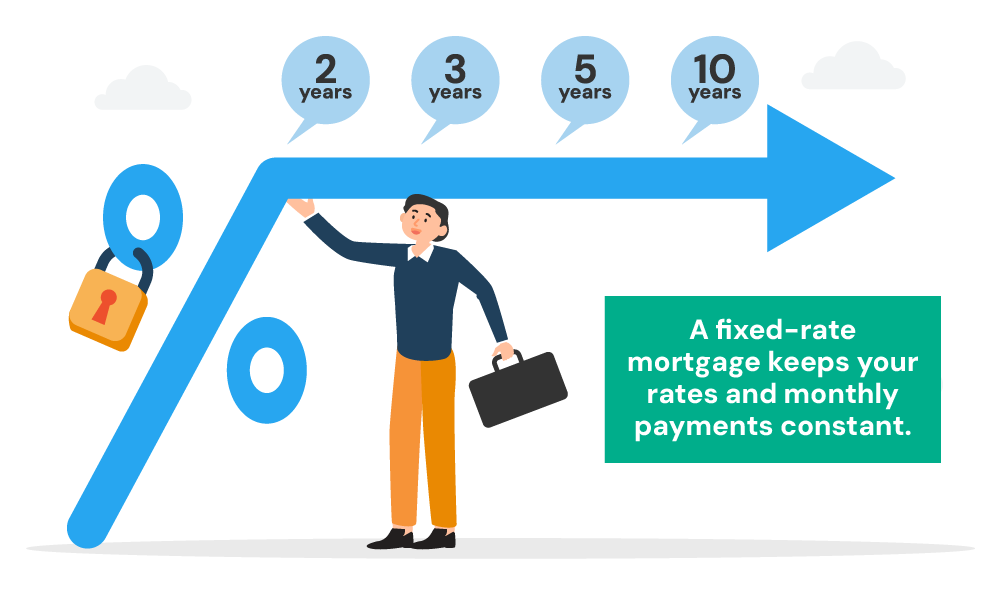
Let’s be honest—mortgages sound about as fun as doing your taxes after a bad night’s sleep. But stick with me, because this one tiny decision can save you thousands.
I’m talking about fixing your mortgage rate. You know, choosing between a fixed rate (safe and steady) or a variable rate (a bit of a gamble). It’s like deciding whether to order your usual coffee or try the mystery blend.
Why should you care? (The short answer)
Imagine you’re on a road trip, and your car has two settings: cruise control or manual. Fixing your mortgage is like hitting cruise control—you know exactly what you’ll pay each month, no surprises.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Variable rates are like driving stick shift in a city with sudden potholes. You might save a little gas, but you could also bump your head on the ceiling when the economy jerks.
So, the big question is: how long should you fix it for? Two years? Five? Ten? Let’s break it down without the finance jargon.
The “Goldilocks” of mortgage terms
Think of your mortgage term like picking a pair of jeans. Two-year fix is a skinny jean—snug, trendy, but could stretch out quickly if interest rates change.
A ten-year fix is like a pair of elastic-waist sweatpants. Super comfy, but you’ll pay a bit more upfront for that cushion, and you might feel trapped if you want to move house.
The sweet spot? For most people, a five-year fixed rate is the Goldilocks choice. It’s not too risky, not too stiff, and it gives your monthly budget a nice, long hug.
But what if rates go down?
Ah, the big fear. You lock in a rate, and then the Bank of England (or your local central bank) drops rates like a hot potato. Suddenly, your neighbour is bragging about their lower variable rate.
Here’s the truth: you can’t time the market. Trust me, I tried to time buying avocados once, and I ended up with brown mush. Don’t be like me.
Fixing gives you peace of mind. And peace of mind is worth more than the few hundred quid you might save chasing a lower rate. If rates do go down, you can always remortgage after your fix ends.
The “emergency fund” rule
Here’s a rule I made up, but it works: Fix as long as you can afford to pay the monthly bill without crying.
If you have a stable job and a little savings buffer, a short fix (two to three years) is fine. You can ride the waves like a surfer who knows how to swim.
But if your job is a bit wobbly, or if the thought of a rate hike keeps you up at night, go for a longer fix. It’s like buying a sturdy umbrella instead of a paper one—you’ll be dry even in a downpour.
The “life stage” test
Are you planning to move in the next few years? If yes, don’t fix for more than two or three years. You don’t want to pay early repayment charges just because you fell in love with a house with a bigger garden.
Are you settling down for a while? Maybe starting a family, or just tired of packing boxes? Then a five- or seven-year fix is your jam. It’s the financial equivalent of ordering the same takeaway every Friday—reliable and comforting.
And if you’re retired or near retirement? Ten-year fix all the way. You’ve earned the right to not think about rates while you sip tea and watch the birds.
What about the “savvy” people?
You’ll meet folks who swear by variable rates. They’ll say things like, “I saved 1.5% last year, mate!” Good for them. But they won’t mention the sleepless nights when inflation sneezes.

I’m not saying don’t be savvy. I’m saying know yourself. If you’re the type who checks the stock market before breakfast, maybe variable is for you. If you’re the type who panics when your Netflix bill goes up by a pound, fix it and forget it.
The one question you must ask yourself
When you’re staring at those mortgage offers, ask this: “If rates go up by 2% tomorrow, will I be able to sleep tonight?”
If the answer is “No,” fix it for as long as you can. If it’s “Yes, I’ll just skip fancy lattes for a month,” then go short or variable.
I remember my cousin Lucy fixed her mortgage for seven years right before rates shot up. She didn’t become a financial guru—she just wanted to know her payment wouldn’t change while her kids grew out of shoes every week. Smart Lucy.
Final tip: Don’t overthink it
Here’s the thing—mortgage rates are like the weather in London. You can try to predict it, but you’ll end up carrying a raincoat and sunglasses for nothing.
Most experts agree that fixing for at least five years is a solid bet for the average person. It’s not flashy, but it’s sensible, like eating vegetables or flossing.
So, go grab a cuppa, look at your budget, and ask yourself what kind of peace you want. Then pick a fix that feels like a warm blanket, not a straitjacket.
You’ve got this. And hey, if you get it wrong? You can always remortgage later. That’s the beauty of it—this isn’t a tattoo. It’s just a choice.