
Is It Hard To Get A Mortgage
So, my buddy Dave—you know the type, perpetually optimistic, thinks everything will work out—calls me up last week. “Dude,” he says, “I found the perfect house. Three bedrooms, a yard for the dog, and the seller even left the washer-dryer.” He’s already picking out paint colors. Then his voice drops. “But… is it hard to get a mortgage? Like, really hard?” I had to laugh. Dave’s credit score is a mystery even to him, and his down payment savings consist of a jar labeled “Future Island Getaway.” We’ve all been there, right? Staring at the dream and wondering if the paperwork monster will eat it alive.
Here’s the thing: the answer isn’t a simple yes or no. It’s more like, “It depends on who you are and what you’re hiding in your bank account.” And honestly? A lot of the fear comes from horror stories your uncle tells you at Thanksgiving. You know the one—he talks about 2008 like he was a frontline soldier. But times have changed, and so have the rules. Let’s cut through the drama and look at the real puzzle.
The Three-Headed Monster of Qualification
Think of a mortgage application as a three-headed dragon. You’ve got your credit, your income, and your down payment. If one head is choppy, the whole beast might breathe fire in your face. But here’s the secret: you don’t need to slay all three perfectly—you just need to convince the lender you’re not going to burn their house down.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
First Head: Your Credit Score (The Drama Queen)
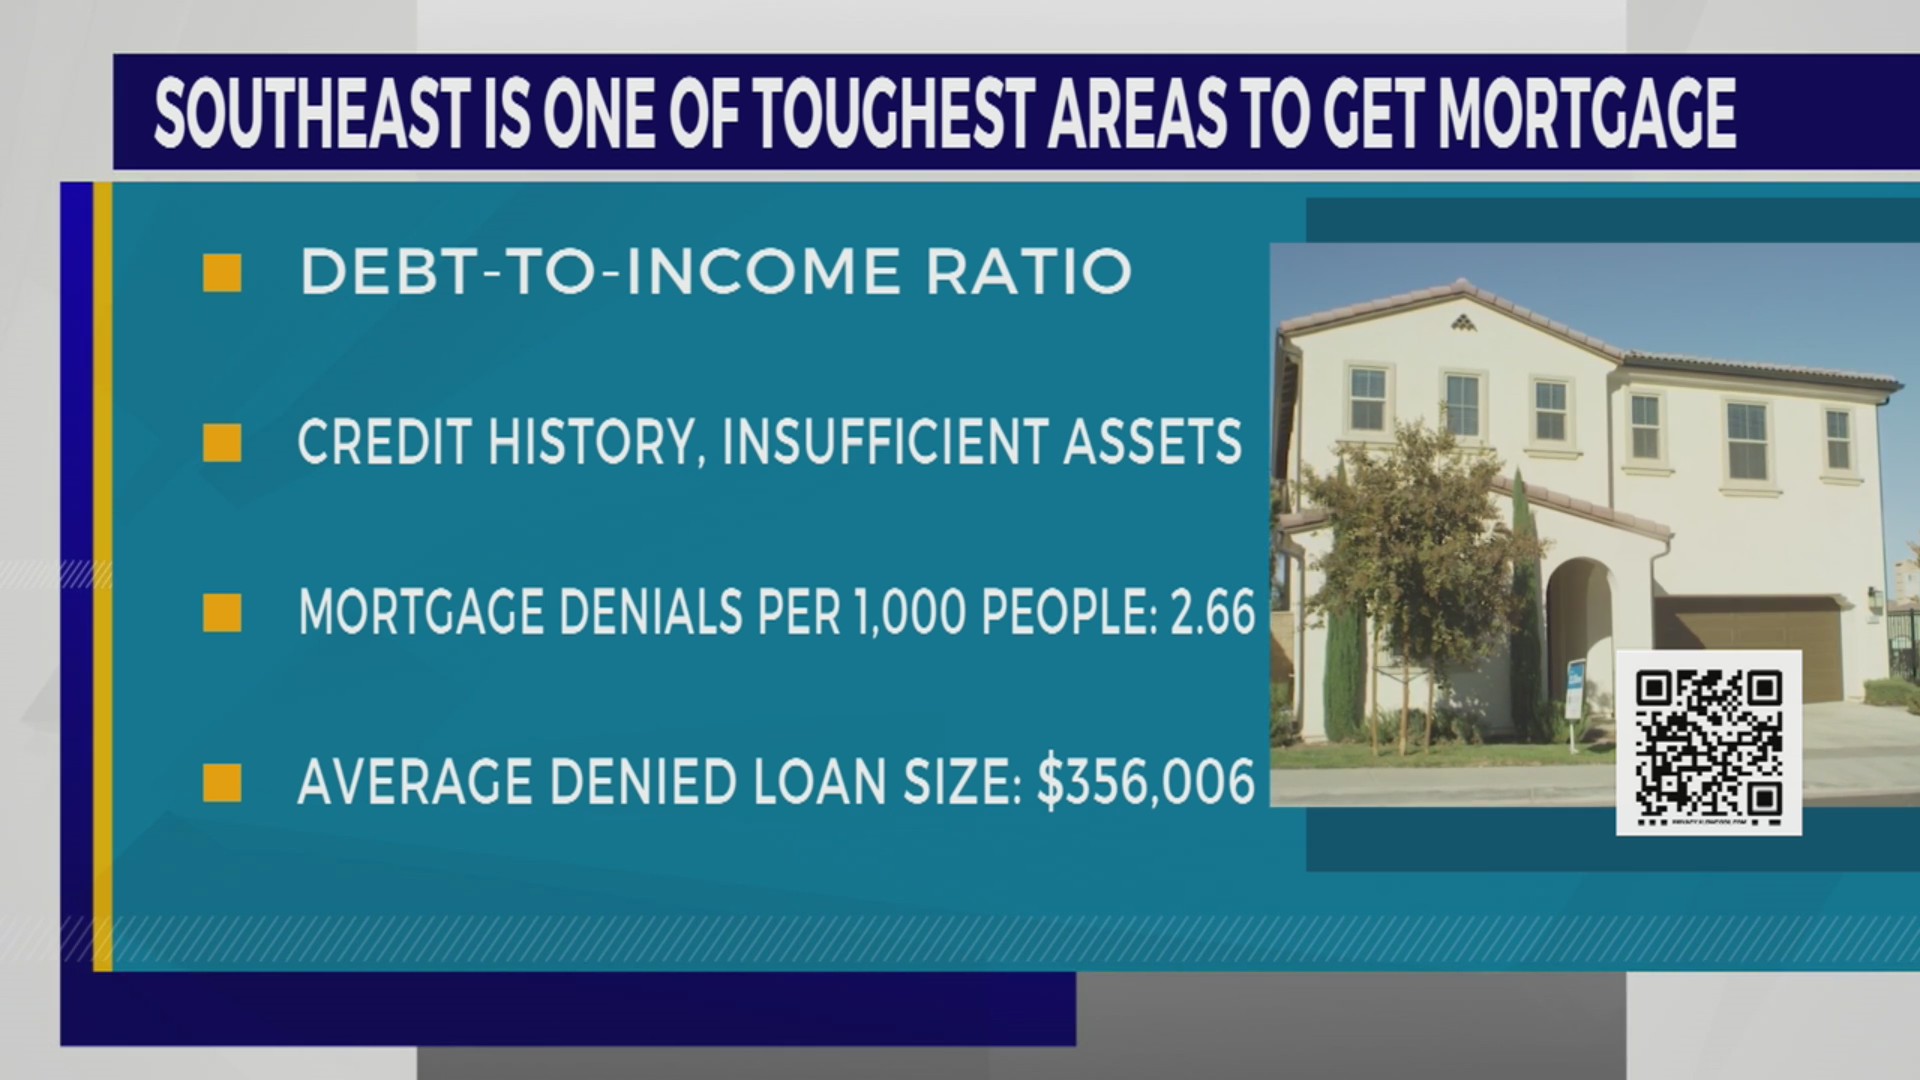
This is the part everyone hyperventilates about. A 780 score? You’re a golden god. A 620? Yikes. But guess what? There are mortgages designed for people who missed a credit card payment six years ago. FHA loans can go as low as 580, and sometimes even 500 with a bigger down payment. (Don’t tell Dave that—he’ll buy a boat first.) So, is it hard? Only if your credit report looks like a crime scene. Get a free copy, check for errors, and pay down those rascal balances. Do that, and you’re already halfway there.
Second Head: Your Income (The Skeptic)
Lenders want to see stable income. They get twitchy if you’re a freelancer, a gig worker, or someone who changes jobs every year. “But I make great money!” you say. Sure, but they want proof. Two years of tax returns, W-2s, and maybe a note from your dog sitter. (Kidding—mostly.) The trick here is to document everything. If you’ve been driving for Uber, show them the mileage logs. Get organized. It’s annoying, like doing taxes twice, but it’s the price of entry. And yes, it is harder if you’re self-employed. But not impossible—just more paperwork.
The Down Payment Myth (and the 3% Miracle)
Everyone thinks you need 20% down. That is a beautiful, ancient lie. Sure, 20% gets you out of paying private mortgage insurance (PMI), but you can get a conventional loan with as little as 3% down. FHA loans need 3.5%. Even VA loans and USDA loans can be zero down if you’re eligible. I know a couple who bought their first home with $5,000 total out of pocket. They ate ramen for three months, but they did it. So, is it hard to get a mortgage because of the down payment? Only if you’ve been saving your spare change in a pillowcase.
But Wait—There’s More! (The DTI Trap)
Ah, the debt-to-income ratio—the sneakiest dragon head. This is your monthly debt payments divided by your gross income. Lenders generally want it under 43%. If you have a car loan, student loans, and three credit cards with balances, your DTI could be screaming “danger zone.” The fix? Pay off the smallest debts first, or—brace yourself—wait until you pay down the car. Patience isn’t fun, but neither is living in your parents’ basement forever.
So, Is It Hard? (The Honest Answer)
Look, getting a mortgage is like assembling IKEA furniture. It looks terrifying on the box, it takes longer than you expect, and you’ll probably swear at least once. But millions of people do it every year—including people with less-than-perfect credit and weird jobs. It’s not hard in the “can’t do it” sense. It’s hard in the “you have to be patient and organized” sense. And if you’re reading this while munching chips on your couch, you’re already ahead of Dave, who’s still trying to figure out what a “pre-approval” letter is.
So, keep your job, pay your bills on time, and grab a coffee with a loan officer. Ask questions. Be annoying. They get paid to help you. And when you finally get that key in your hand? You’ll forget about the paperwork—until the first time the toilet clogs. But that’s another article. You got this.