
Buying A House On Benefits Uk
So, you’re on benefits and you’ve got this wild, crazy idea: buying a house. First off, give yourself a round of applause—because that’s not a pipe dream, it’s a real possibility. Yeah, you heard me. The UK property ladder isn’t just for people with trust funds and avocado-toast-free diets.
The Big Myth: “You Can’t Buy On Benefits”
Let’s smash that myth with a sledgehammer right now. You can buy a house while claiming benefits—it’s just a bit more of a puzzle. Think of it like assembling IKEA furniture without the instructions: frustrating, but totally doable if you know which bit goes where.
The key word here is affordability. Lenders will look at your total income, including certain benefits like Child Benefit, Tax Credits, and even some parts of Universal Credit. They’re not monsters—they just want to be sure you can pay them back without selling a kidney.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Which Benefits Actually Count?
Not all benefits are created equal in the eyes of a mortgage lender. Guaranteed, long-term benefits are your best friends here. Think PIP (Personal Independence Payment), Disability Living Allowance, and Carer’s Allowance—these are like gold dust because they’re often treated as stable income.
Universal Credit is trickier. Lenders will usually only count the housing element if you’re buying, and even then, they might squint at it suspiciously. But don’t panic—specialist lenders exist who get the benefits system and won’t run away screaming.
Jobseeker’s Allowance? Yeah, that’s a tougher sell. Lenders see it as temporary, like a bad haircut. But if you can top up with part-time work or other benefits, you can still build a strong case.
The “Bootstraps” Moment (Spoiler: It’s Not That)
You’ll hear people say you just need to “save harder” or “get a better job.” Ignore them. They probably think a “flat white” is a type of pavement. The truth is, buying on benefits is about creative financing, not magic.
Start with a Help to Buy: ISA or a Lifetime ISA—the government basically gives you free money for your deposit. If you’re on certain benefits, you might also qualify for Shared Ownership, where you buy a slice of the house and rent the rest. It’s like buying a pizza slice instead of the whole pizza—still delicious, just less dough.
The Deposit: Where Do You Find That?
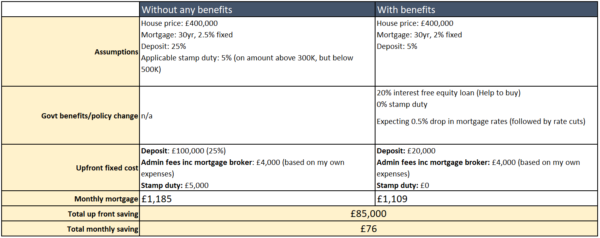
Right, the deposit. This is the bit where most people’s eyes glaze over. But here’s a secret: you don’t need a 20% deposit. Some schemes let you put down as little as 5%. Yes, 5%. That’s basically the price of a halfway decent used car.
And don’t forget gifted deposits. If your mum, nan, or that mysterious rich uncle you never see can chip in, lenders are usually fine with it. Just make sure they sign a letter saying it’s not a loan—because no one wants your gran chasing you for repayments.

Also, look into Local Authority schemes. Some councils offer equity loans or grants to help people on benefits buy a home. It’s buried treasure, but you have to dig through a few web pages to find it.
The Mortgage Application: A Comedy of Forms
Getting a mortgage on benefits involves paperwork. So much paperwork. You’ll need benefit award letters, bank statements, and a letter from your MP if they’re feeling generous. But here’s the trick: present your benefits as stable income.
For example, if you’ve been on PIP for five years, that’s not “temporary” – that’s rock solid. Write a cover letter explaining your situation. Lenders are humans (mostly), and a clear story can make them nod along instead of hitting “decline.”
And for goodness’ sake, check your credit score first. If it’s looking a bit rough, fix it. Pay off old mobile phone bills, cancel unused credit cards, and argue with anyone who’s wrongly marked you as late. It’s like spring cleaning, but for your finances.
The Dream Home? No, The Right Home
You won’t be buying a mansion with a helipad. But you can buy a cosy flat or a small house that’s yours to paint, decorate, and never ask a landlord for permission to hang a picture.
Think about location too. A cheaper area might mean a longer commute, but it also means a mortgage you can actually afford. And remember: a fixer-upper is your best friend. You can do it up slowly, room by room, like a hobby, but with fewer splinters.
Also, consider new-build schemes like First Homes, which offer discounted prices for local buyers. It’s like a sale, but for houses, not shoes.
The “But What If I Lose My Benefits?” Panic
This is the worry that keeps you up at 3am. But here’s the thing: many lenders will still consider you if you have a buffer—like savings or a partner’s income. Plus, you can get income protection insurance specifically designed for people on benefits. It’s not cheap, but it’s cheaper than a heart attack.
And let’s be real: being on benefits doesn’t mean your life is static. You might get a job, get promoted, or win the lottery (don’t hold your breath). The point is, buying a house now can be a launchpad, not a trap.
Final Advice: Get Professional Help
Don’t do this alone. Find a specialist mortgage broker who knows benefits inside out. They’ll know which lenders accept Universal Credit, which ones love PIP, and which ones to avoid like a wet handshake.
Also, chat with a housing advisor at your local council. They often have free workshops or one-to-one sessions. They won’t judge you—they’ve seen it all, including the guy who tried to buy a house with a piggy bank.
And most importantly: believe it’s possible. The system isn’t built for people on benefits, but that doesn’t mean you’re excluded. It just means you have to be cleverer, more patient, and more stubborn than the average buyer.
So go on. Start saving that deposit, even if it’s a tenner a week. Check your credit score. And when you finally get those keys in your hand—those shiny, beautiful keys to your own front door—you’ll look back and laugh at everyone who said you couldn’t.
You didn’t just buy a house. You proved that the system doesn’t define your future. And that, my friend, is the best kind of victory—no mortgage needed for that feeling.