
How To Apply For Advance Payment
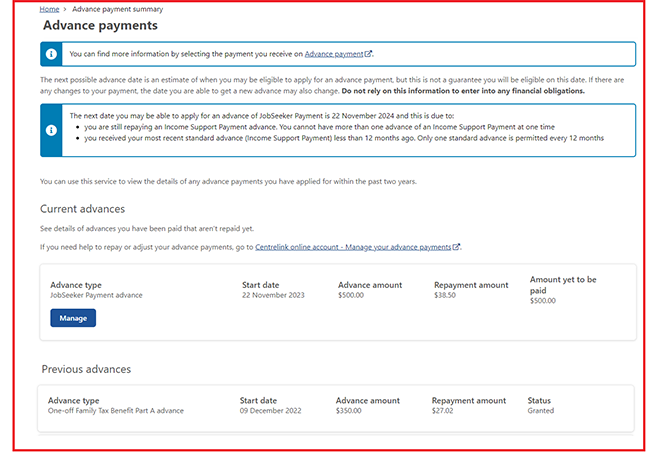
So, you need money now. Not in a week, not after you’ve sold a kidney on the dark web, but immediately. Welcome to the glorious, bureaucratic dance called an advance payment request. It’s like asking your boss for a loan, but with more paperwork and fewer awkward stares.
What’s the Big Deal?
An advance payment is basically your future salary saying, “Hey, hold my beer.” You’re borrowing against work you haven’t done yet, which feels like time travel, but with bank fees. Governments, startups, and even your weird uncle use them—though Uncle Gary’s version usually involves a jar of change.
Surprising fact: The concept of advance payments dates back to ancient Mesopotamia, where farmers got grain loans before harvest. If they defaulted, they were sold into slavery. Today, you just get a nasty letter from a robot. Progress!
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Step 1: Check If You’re Even Eligible
Before you start printing forms, ask yourself: Do I have a pulse? Is my credit score above “feral raccoon”? Most lenders require you to have a job, a bank account, and a history of not lighting your money on fire. If you’re a freelancer, good luck—they’ll ask for tax returns that smell of regret.
Pro tip: If your bank says “no,” try smiling. It works 2% of the time. The other 98%? You get a pity pamphlet.
Step 2: Gather Your Weapons (Documents)
You’ll need a photo ID that doesn’t make you look like a wanted criminal. Also, pay stubs, a utility bill, and a signed affidavit from your third-grade teacher confirming you’re a responsible human. Okay, maybe not that last one, but expect to feel like a magician pulling stuff out of a hat—except the hat is on fire.
One common mistake: forgetting to include the actual amount you need. Don’t just write “a bunch.” Banks hate vagueness. Write a specific number, like $500, or if you’re feeling spicy, $499.99—they love precision.
Step 3: Fill Out the Form (Or Hire a Sad Clown)
Forms are the universe’s way of testing your patience. They ask for your name, address, and the names of all your dead ancestors. Read every line twice—once for content, once for the tiny print that says “you owe us your firstborn.” Just kidding. Mostly.

Fun fact: In Japan, some advance payment forms include a section for your blood type. Why? Because bureaucracy is a circus. If you’re type A, you might get approved faster. I’m not making this up—it’s a real thing in certain Asian business cultures. True story.
Step 4: Submit and Pray to the Online Gods
Most applications are digital now, which means you’ll fight a CAPTCHA that asks you to “select all traffic lights.” You will click wrong. The page will reset. Your soul will shrivel. Breathe. Then try again, while muttering curse words your grandma wouldn’t approve of.
After submission, you’ll get a confirmation email that smells faintly of spam. Don’t delete it. Print it. Frame it if you must—that digital receipt is your only friend now.
Step 5: Wait (And Practice Patience, You Anxious Cactus)
The wait time varies. Sometimes it’s 24 hours. Sometimes it’s “we’ll get back to you before the next ice age.” Don’t call every hour. They’ll know it’s you. I called once, and the rep said, “Sir, I can see you’ve called 47 times. Why?” I said, “Because you said ‘soon.’” He sighed. I didn’t get the money.
If approved, the cash usually lands in your account within 1–3 business days. That’s 72 hours of watching your balance like a hawk on espresso. Use the time to plan what you’ll buy—maybe a lottery ticket, because you’re clearly a gambler now.
The Fine Print (aka the Horror Story)
Advance payments often come with fees. Like, a “convenience fee” for the inconvenience of giving you money. Or an “origination fee” because businesses love big words. Some lenders charge interest rates that would make a loan shark blush. Read the terms like you’re diffusing a bomb—slowly, with trembling hands.
Shocking stat: According to a 2023 survey, 1 in 3 people who take an advance payment later say they “didn’t fully understand the repayment schedule.” That’s like diving into a pool and then realizing you hate water. Don’t be that person.
Final Wisdom: Don’t Do It for Tacos
Advances are for emergencies—like a car repair, a surprise medical bill, or buying a gift for your mom so she stops guilt-tripping you. Not for tacos. I know tacos are delicious. Trust me. But four taco Tuesdays later, you’ll be eating ramen and crying over the repayment plan. Your future self is watching you, and they’re holding a spreadsheet.
If you follow these steps, you’ll get your cash faster than a cat chasing a laser pointer. Just remember: money advances are a tool, not a lifestyle. Use them wisely, or expect to see a sad clown at your door, asking for your form back.
Now go forth, apply, and try not to shake your fist at the sky. Good luck—you’ll need it.