
What Is Oop In Insurance

Alright, let’s talk about insurance. Yes, insurance—that thing we buy hoping we never actually need to use. It’s like buying a fire extinguisher for your kitchen: you’re glad it’s there, but you’d rather not practice your fire-dance moves. One term that pops up in the fine print is OOP. No, it’s not a dance move or a video game sound effect. OOP stands for Out-of-Pocket costs. It’s the money you, the brave policyholder, have to cough up before your insurance company starts writing those lovely checks.
Think of OOP as your financial entrance fee to the insurance party. You pay your monthly premium (that’s the cover charge), but OOP is what you shell out for actual care, repairs, or medication. It’s like buying a concert ticket and then having to pay extra for the overpriced soda. Annoying? Sure. But it keeps the system from going totally bankrupt.
The Three Musketeers of OOP
Out-of-Pocket costs usually come in three flavors: deductibles, copays, and coinsurance. They’re like that friend trio where one is dramatic, one is chill, and one is always calculating the bill. Let’s break them down so you don’t need a decoder ring.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
First up: the deductible. This is the amount you must pay every year before your insurance starts covering stuff. It’s like a video game boss—you have to defeat it (pay it) to unlock the next level. For health insurance, it might be $1,500 or $5,000. For car insurance, it’s the cash you pay after an accident before the company fixes your bumper. The higher your deductible, the lower your monthly premium. It’s a trade-off: pay now or pay later.
Next is the copay. This is a flat fee you pay for a specific service, like $20 for a doctor’s visit or $10 for a prescription. It’s the insurance version of a “convenience fee.” You walk in, you hand over a twenty, and you get to see a professional who tells you to drink more water. Copays usually don’t count toward your deductible, but they do count toward your annual OOP maximum.
Finally, there’s coinsurance. This one’s a bit trickier. It’s a percentage you pay after you’ve met your deductible. Say your plan has 20% coinsurance. That means you pay 20% of the bill, and insurance pays 80%. If your hospital stay costs $10,000, you’re on the hook for $2,000. Ouch. But don’t panic—there’s a safety net.
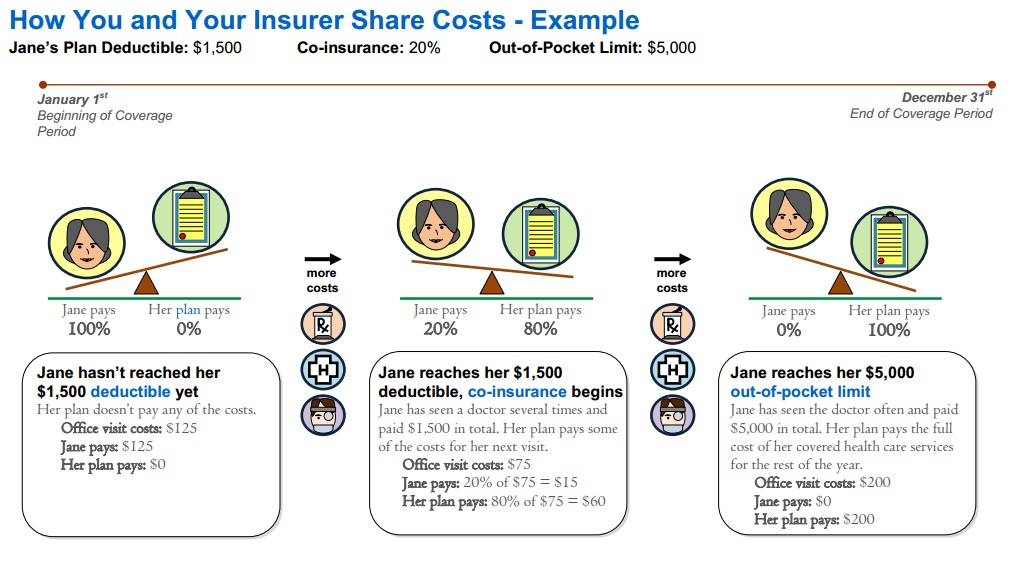
The Magic Number: OOP Maximum
Every insurance plan has a maximum out-of-pocket limit. This is the absolute most you’ll pay in a year for covered services. Once you hit that number, insurance covers everything at 100% (for the rest of the year). It’s like a financial force field. For 2024, the federal limit for health plans is around $9,450 for individuals and $18,900 for families. So even if you get hit by a meteor and need six surgeries, you won’t pay a penny more after that cap. Phew.
Here’s the hidden gem: your deductible, copays, and coinsurance all count toward that maximum. But monthly premiums? Nope, those are separate. It’s like a loyalty card for paying medical bills—collect enough stamps, and you get a free rest of the year. Well, “free” in a relative sense, since you’ve already paid thousands.
Why Should You Care About OOP?
Because OOP costs are where surprise bills hide. You might think, “I have insurance, so I’m covered!” Then you get a $500 bill for an ambulance ride and suddenly you’re questioning your life choices. Knowing your OOP costs helps you budget for real life—not just the plot from a medical drama. It also stops you from crying in the parking lot of the ER.
For example, if you have a chronic condition, choose a plan with a lower deductible and higher premium. You’ll pay more each month, but those OOP costs won’t bankrupt you. If you’re young and healthy, pick a high-deductible plan with a Health Savings Account (HSA). You’ll save on premiums and stash tax-free money for future boo-boos. It’s like playing life on easy mode—just remember to actually save that money.

A Little Tip From Your Cheeky Friend
Always check if a doctor or hospital is “in-network.” Going out-of-network can double your OOP costs faster than you can say “Why is my bill this high?” Insurance companies have deals with certain providers. Stray outside that circle, and you’re paying full price for that Band-Aid. It’s like ordering a fancy coffee at a gas station—overpriced and not worth the regret.
Also, keep all your receipts and Explanation of Benefits (EOBs) forms. Mistakes happen. A study found that 1 in 5 medical bills has errors. You might pay a copay for a service that should have been free. Fight for your money. You worked hard for it; don’t let a billing code snatch it away.
Wrapping Up With a Smile
So, there you have it: OOP is the money you pay before insurance takes over. It’s the deductible, copay, and coinsurance trio that likes to party in your wallet. But the OOP maximum is your superhero cape—it stops the bleeding once you’ve paid enough. Think of insurance as a weird, bureaucratic friend who helps you pay for things you’d rather not need. Is it perfect? No. But having a plan is better than walking around uninsured, hoping you never sneeze wrong.
Next time you hear “out-of-pocket,” don’t panic. You’ve got this. You now know the secret language of insurance agents. Use your knowledge to pick a plan that fits your life, not just one with a pretty brochure. And remember: the best OOP cost is the one you never have to pay because you stayed healthy, drove carefully, and didn’t try to pet a wild raccoon. But if life throws a curveball, at least you won’t be caught off guard. You’re informed, you’re prepared, and you’re absolutely brilliant. Now go forth, read that policy, and maybe treat yourself to a coffee—because you just mastered insurance speak without needing a nap.