
Check Property Liens Free
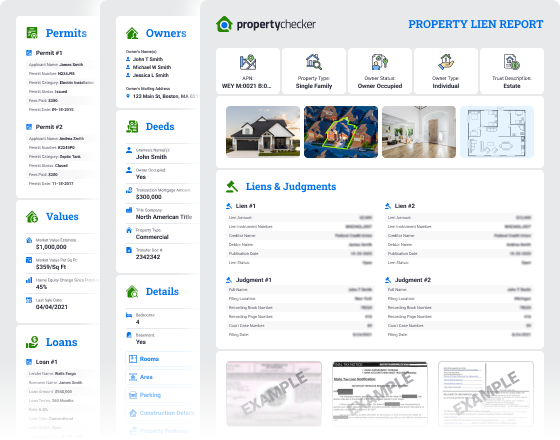
Let’s talk about property liens. You know, those sneaky little financial holds that can turn your dream home into a bureaucratic nightmare? Yeah, those. Maybe you’re buying a house, selling one, or just scrolling Zillow at 2 AM like a normal person. Whatever the case, checking property liens for free is the smartest coffee-break research you’ll do today.
What’s a lien, anyway?
Think of a lien as a red flag tied to a property’s title. It’s a legal claim someone makes because money is owed. Maybe the owner didn’t pay the roofer. Or the tax man wants his cut. Either way, that red flag means the property isn’t fully free and clear.
And here’s the kicker: if you buy a property with a lien still attached, you could be on the hook for that debt. Yikes. That’s why you need to check before you sign anything—or even before you make an offer.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The good news: you can do it for free
I know what you’re thinking: “Free? In this economy?” Yes, really. You don’t need to hire a lawyer or pay for some overpriced service to check property liens. The county recorder’s office—your local government’s dusty file cabinet—has all that info online now.
Most counties let you search property records by address or owner name. It’s like playing detective, but with fewer trench coats and more browser tabs. Just go to your county’s official website, look for “recorder of deeds” or “assessor’s office,” and start poking around.
Is it thrilling? Not exactly. But it beats finding out later that you owe $15,000 for someone else’s unpaid solar panels. Trust me on that.
Wait, can I really trust free sites?
You’ll see ads for “free lien check” websites everywhere. Be careful here. Some of those are just lead generators trying to sell you something. Stick with official .gov domains or reputable tax assessor portals. They’re boring but bulletproof.
If you want a second opinion, try a site like PropertyShark or NETR Online. They offer limited free searches. Just don’t hand over your credit card until you’re sure you need it.
And hey, if you’re feeling lazy, call your real estate agent. They should be able to pull a preliminary title report for you. But doing it yourself? That’s power. That’s coffee-and-internet-sleuthing power.

Why bother? Because liens love to hide
Here’s a fun fact: a property can have multiple liens. There’s the mortgage lien (the big one). Then maybe a mechanic’s lien from an angry contractor. Or a tax lien from the IRS. Or even a homeowner’s association lien for unpaid dues.
You might think the seller is honest. You might have a handshake and a smile. But the county records don’t care about vibes. They care about paperwork. Cold, hard paperwork.
So checking for liens is like looking under the bed before you buy it. You don’t want to find a monster later. You want to find dust bunnies and maybe an old sock. No monsters allowed.
How do I actually search?
Okay, let’s get practical. Open your browser. Type the county name plus “property search” or “lien check.” Most sites let you search by owner name, property address, or parcel number. Parcel numbers are gold—they’re unique IDs that avoid confusion over similar names.
Once you’re in, look for documents labeled “Notice of Federal Tax Lien,” “Mechanic’s Lien,” or “Judgment Lien.” Those are the troublemakers. If you see “Release of Lien” or “Satisfaction of Mortgage,” you’re in the clear. High five.
Take a screenshot or save the PDF. You’ll thank yourself later when you’re comparing notes with your lender or title company.

What if I find a lien?
Don’t panic. Finding a lien isn’t the end of the world—it’s just the beginning of a negotiation. You can ask the seller to pay it off before closing. Or you can walk away if the debt is bigger than your dreams for the house.
But here’s the secret: you have power because you know. The seller might hope you never check. But you did. And now you can act like a pro. Ask for proof it’s been paid. Demand a title search from a licensed company. Don’t accept a “don’t worry about it” from anyone.
And if the seller gets defensive? Run. Run fast. A defensive seller is often a seller with something to hide.
Free is nice, but not foolproof
Let’s be honest: free online checks are great for a first look, but they might miss a lien filed in a different county or one that’s pending. That’s why you’ll eventually want a full title search from a professional. Think of it like a free dental screening vs. a real X-ray. One catches obvious cavities; the other finds the hidden ones.
Still, the free check is your first line of defense. It’s fast. It’s free. And it saves you from that sinking feeling when you realize you bought a money pit with strings attached.
So next time you’re sipping coffee and dreaming of that cute bungalow, take five minutes to check its liens. Your future self—and your bank account—will send you a thank-you note.
Now go forth, you savvy property detective. And remember: liens are like bedbugs. You don’t want to bring them home.