
Wells Fargo Buys Wachovia
Picture this: it’s 2008, the economy is having a full-blown meltdown, and two of America’s biggest banks are staring at each other like awkward prom dates. Wells Fargo, the stagecoach-riding, cowboy-hat-wearing bank from the West, suddenly buys Wachovia, the Southern banking giant with a name that sounds like a fancy dance move. It was less of a merger and more of a financial game of Mine!—and the prize was a massive, slightly wobbly banking empire. Let’s grab a coffee and unpack this ridiculous, nail-biting saga.
The Shocking Announcement
In early October 2008, the world learned that Wells Fargo had snatched up Wachovia for about $15 billion in stock. Wachovia, mind you, was the fourth-largest bank in the U.S. at the time, with thousands of branches from Connecticut to California. It was like finding out your quiet neighbor just bought a Ferrari, but the Ferrari was on fire and had a broken steering wheel. Why would anyone do this? Because Wachovia was drowning in bad mortgage loans, and the government was desperate to avoid another Lehman Brothers-level disaster.
Here’s the surprising fact: Citigroup had already won the bidding war for Wachovia just days earlier, offering a government-backed deal. Wells Fargo crashed the party like a bull in a china shop, swooping in with a better offer—no government cash needed. Citi sued, threw a tantrum, and even called it “tortious interference,” which sounds like a law school drinking game. The whole drama played out over a single weekend, with bankers working so fast they probably forgot to eat pizza.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The Accidental Empire Builder
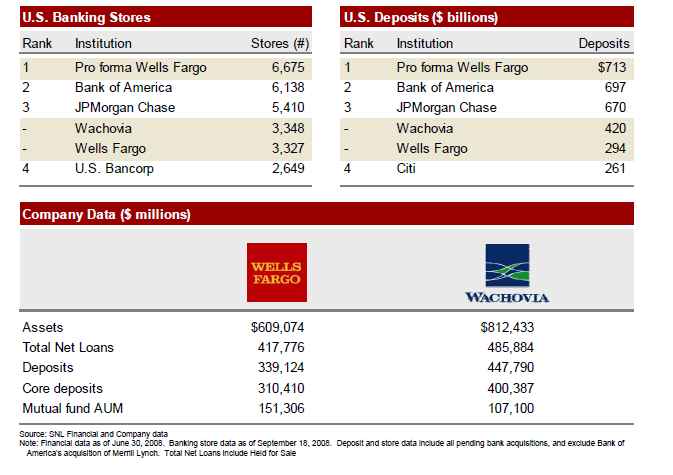
Wells Fargo, known for its sturdy, boring reputation, suddenly became the king of the East Coast. Overnight, they added Wachovia’s 3,300 branches, gaining a massive footprint in states like Florida, North Carolina, and New York. It was like the shy kid in high school suddenly inheriting a tuxedo and a yacht. The deal made Wells Fargo the largest retail bank in the United States by number of branches, with over 6,600 locations. Even their own executives seemed stunned, probably muttering, “Did we just buy all of this with frequent flyer miles?”
Let’s not forget the cultural clash. Wells Fargo employees wore blue jeans and cowboy boots; Wachovia folks wore pressed suits and spoke with a genteel Southern drawl. One banker described the merger as “a rodeo meeting a garden party.” The real comedy came later when Wells Fargo started slapping its stagecoach logos on all those Wachovia signs, making entire towns look like frontier outposts. Did anyone ask the locals? Nope. Because in banking, you get the horse you’re given.
The Financial Mirage
On paper, buying Wachovia was a genius move. Wells Fargo got a huge customer base, a bunch of insurance and wealth management units, and—oh, yeah—$142 billion in Wachovia’s loan portfolio. But here’s the kicker: that portfolio was stuffed with toxic mortgages, the same ones that caused the global financial crisis. Wells Fargo’s CEO, John Stumpf, confidently claimed the loans were “manageable,” which is like saying a leaking boat has “a slight dampness.”
Within a year, Wells Fargo had to write off $24 billion in bad Wachovia loans. That’s enough money to buy every person in Texas a one-way ticket to Mars—and back. The government had to inject $25 billion in TARP funds just to keep the combined bank afloat. So much for a no-government-cash deal. It was the financial equivalent of buying a house with a haunted attic, then discovering the attic has a ghost army.
Still, the merger did save Wachovia from a catastrophic collapse, which would have wiped out millions of customers and employees. The FDIC estimated that without the merger, the cost to taxpayers would have been $20 billion or more. So in a weird way, Wells Fargo’s impulsive bet actually worked—like a drunk karaoke performance that somehow wins you a recording contract. Sometimes the dumbest ideas are the smartest ones.
The Aftermath and Irony
In the years after, Wells Fargo endured its own scandals—fake accounts, shady fees, you name it—but the Wachovia deal remained a textbook example of bank-crisis first aid. Today, most people have forgotten that “Wachovia” was ever a separate brand. Its branches are now just Wells Fargo offices, filled with the same tired tellers and overpriced coffee. The only trace of the old bank is a few Wachovia-branded ATMs that stubbornly refuse to be replaced, like an elderly aunt who won’t throw away her 1980s couch.
Oh, and one more surprising fact: Wachovia’s previous CEO, Ken Thompson, was forced out in 2008 for his role in the disastrous acquisition of Golden West Financial—a mortgage lender that basically lit the fuse on Wachovia’s collapse. So the bank that bought everyone else got bought itself. Irony tastes like a mortgage payment you can’t afford. The whole saga is a reminder that in finance, nobody wins forever—they just buy the next loser.
So next time you walk into a Wells Fargo and see that stagecoach, remember: you’re standing on the grave of a Southern banking dynasty. Give a little nod to the Wachovia ghosts—they’re probably still arguing over the boardroom temperature. And if you hear a faint “yee-haw” from the ATM? That’s just capitalism, laughing all the way to the bank.