
Underwriting Loan Phone Calls

Let’s be honest for a second. If your phone buzzes and the caller ID says “Unknown Number,” your first instinct is probably to send it straight to voicemail. And if it’s a loan officer on the line? That might feel even more awkward, like getting a pop quiz from a friendly but serious professor. But here’s the thing: that phone call, known in the banking world as an underwriting call, is actually your secret weapon. It’s less like an interrogation and more like a helpful friend double-checking your grocery list before you leave the house.
It’s Not a Test; It’s a Quick Check-In
Think of underwriting as the backstage crew of a theater production. You see the shiny loan, but they make sure all the ropes and pulleys are secure. When they call you, it’s usually because they just need one or two small clarifications. Maybe your paystub shows a bonus that looks weird, or you recently switched bank accounts. They aren't trying to trip you up; they just want to connect the dots so they can say “yes” with confidence.
Remember when you baked that complicated cake for a friend’s birthday? You probably called them to ask, “Hey, are you allergic to anything?” That’s exactly what this phone call is. It’s a simple, warm check-in to make sure the final product is perfect for you. The underwriter just wants to make sure your financial recipe has the right ingredients.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The “Human Glitch” Moment
We all know the panic of a typo. Maybe you wrote “Main St.” instead of “Main Street” on a form. To a computer, that might as well be on another planet. An underwriter understands that life is messy and full of small mistakes. Their call is often the little nudge that says, “Hey, can you confirm if this is a typo or a different address?”
Don’t be embarrassed. I once had a friend who accidentally put their birth year as 1982 instead of 1992. The underwriter chuckled, asked for clarification, and the loan sailed through. They are real humans sitting at real desks, often sipping the same cold coffee you are. Treating them like a friendly neighbor from two cubicles down makes the whole thing smoother.
Why You Should Actually Pick Up the Phone
Here is the biggest secret in the lending world: Speed is your friend. If an underwriter calls and you let it go to voicemail, the clock doesn't stop. Their pile of work keeps growing, and your file gets pushed to the bottom of the stack while they wait for you. A single returned call can shave days off your closing time.
Imagine you’re ordering a pizza. The kitchen has everything ready—dough, sauce, cheese—but they can’t find the pepperoni. They call you to ask, “Do you still want pepperoni?” If you don’t answer, they just stand there. Your pizza gets cold. Your loan is the same way; they just need one tiny answer to fire up the oven.
What a Good Call Actually Sounds Like
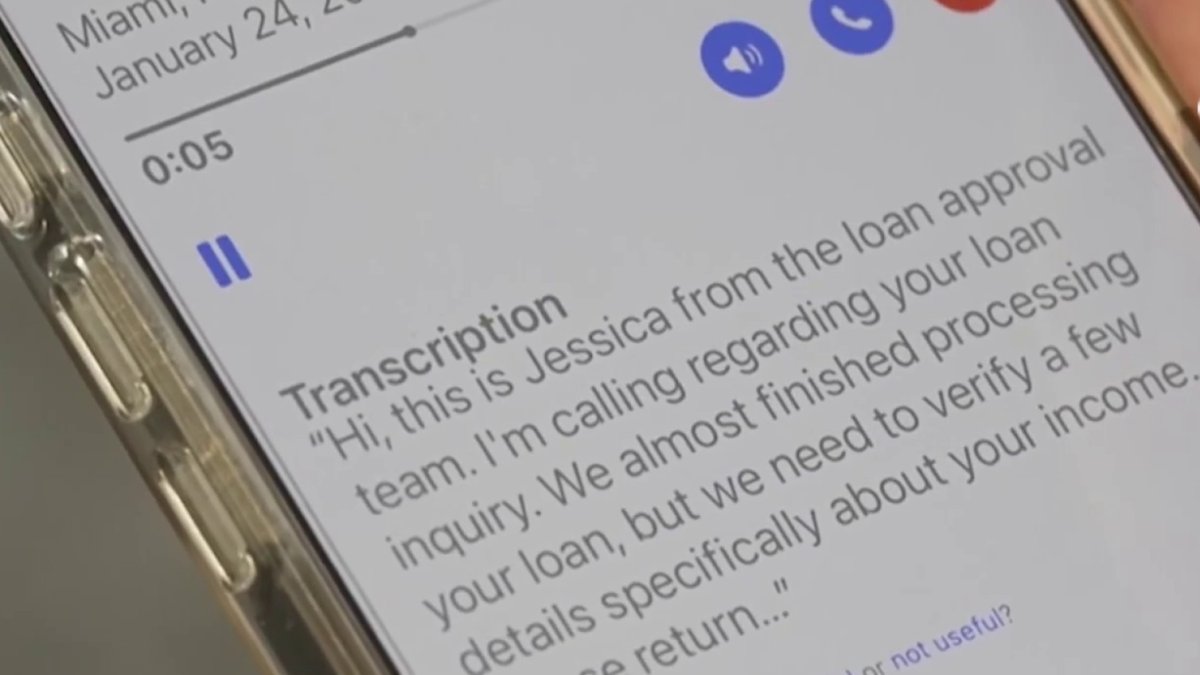
A solid underwriting call is relaxing and straightforward. The person on the other end will likely start with, “Hi, this is Sarah from the loan team. I just have a quick question about your recent deposit.” It’s not a grilling. It’s a cooperative puzzle. You’re on the same team, trying to solve a small riddle together.
You might hear things like, “I see you wrote down ‘cash bonus’ but it’s listed differently on your statement. Can you tell me about that?” It’s a simple story, not a math exam. If you can explain it like you would to a curious cousin, you’re golden.

How to Sound Like a Pro (Without Being One)
You don’t need a finance degree to ace this call. Just be honest and prepared. If you can, have your recent bank statements and pay stubs nearby. If they ask about a $50 charge at a coffee shop, you can just say, “Oh, that’s my weekly coffee subscription.” They don’t care about the coffee; they just want to confirm it’s not a hidden loan payment.
Also, don’t be afraid to ask questions yourself. If they use a fancy word like “seasoning” or “DTI,” simply say, “Can you explain that one more time in plain English?” They expect that. They would rather explain it twice than have you guess and mess things up. It shows you’re paying attention, which they love.
The Happy Ending
The very best part of an underwriting call is how it usually ends. After you answer a few easy questions, you’ll often hear the magic phrase: “Great, that clears things up! I can move this forward for final approval.” It’s like finishing a small chore and getting a gold star. Suddenly, the whole scary process feels manageable.
So next time you see that unknown number and you’re waiting on a loan, take a deep breath. Answer it with a smile in your voice. That person on the other end is just a friendly helper with a pen, trying to connect your real life to your dream loan. It’s just a quick chat, and then you’re one giant step closer to the keys to your new place.