
Lease Accounting Journal Entries Example
Alright, grab your favorite caffeinated beverage (or a glass of wine, I don’t judge) and let’s talk about something that sounds scarier than it actually is: lease accounting journal entries. I know, I know, your eyes just glazed over. But trust me, we’re going to make this as fun as balancing a checkbook on a unicycle — well, maybe a little more fun than that.
Why Bother with Lease Accounting?
First, the big picture. If your company rents anything — a office space, a fleet of delivery vans, or a giant mechanical llama for a parade — you probably have a lease. And thanks to the new accounting rules (ASC 842, IFRS 16, the usual alphabet soup), most leases have to live on your balance sheet now. No more hiding them in the footnotes like a guilty secret.
Think of it this way: you’re basically admitting, “Yes, I’m committed to paying for this thing for a few years.” It’s like telling your friends you’re in a long-term relationship with a office printer. The journal entries are your commitment ceremony.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The Stars of the Show: Right-of-Use Assets and Lease Liabilities
Before we dive into the numbers, meet your two new best friends: the Right-of-Use (ROU) Asset and the Lease Liability. They’re like peanut butter and jelly, but for accountants. The liability is the total amount of future lease payments you owe (present valued, because we’re fancy). The ROU asset is the value of your right to use that space or equipment for the lease term.
Every journal entry will involve these two. They’re the duo that never breaks up, unless you terminate the lease early — which is basically the accounting equivalent of a messy divorce.
Example Time: Renting a Cool Office Space
Let’s say your company, “Creative Widgets Inc.,” signs a 5-year lease for a trendy office space. The total lease payments are $120,000. You start using the space on January 1st. The first step? Recording the lease commencement — it’s the accounting version of moving day.
First, calculate the present value of those payments. For simplicity, let’s say it’s exactly $120,000 (ignore the nerdy discount rate for now). Your entry looks like this:
Debit: Right-of-Use Asset $120,000
Credit: Lease Liability $120,000
Congratulations! You just put a giant invisible asset and liability on your books. Don’t worry, no one can see it unless they know where to look — like a financial version of a secret handshake.
Month One: The First Payment
Now it’s time to pay the landlord. Mr. Landlord wants his $2,000 for the month. But you can’t just throw the whole payment against the liability. Oh no, that would be too easy. You have to split it into two parts: interest and principal. Think of it like a mortgage for office chairs.
Let’s assume the interest for month one is $400 (because accounting loves round numbers). Your journal entry is:
Debit: Lease Liability $1,600
Debit: Interest Expense $400
Credit: Cash $2,000
See? The cash goes out the door, the liability shrinks a little, and you recognize the cost of borrowing. It’s like paying for pizza and realizing you also tipped the delivery driver — the delivery driver is interest here.
Amortization: The Quiet Sibling
But wait, there’s more! That ROU asset doesn’t just sit there forever. It slowly gets used up, just like the shine on a new car. This is called amortization (depreciation for intangible friends). For a straight-line lease, you’ll expense a chunk of the asset each month.
In our example, the total asset is $120,000 over 60 months (5 years). That’s $2,000 per month. The entry is simple:
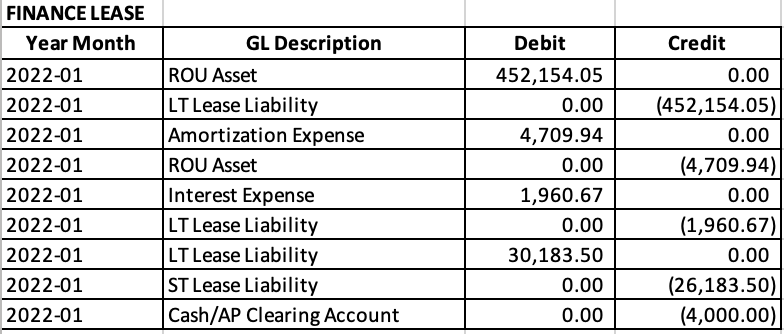
Debit: Amortization Expense $2,000
Credit: Right-of-Use Asset $2,000
Your ROU asset is now shrinking. It’s like watching your favorite candle burn down — except it’s a legal document on fire.
The Full Month’s Picture: Combine It All
To make your life easier (and your accountant happier), here’s what goes on the income statement for month one:
- Interest Expense: $400
- Amortization Expense: $2,000
- Total lease expense: $2,400
Wait a second — didn’t you only pay $2,000 cash? Yes! But accounting is weird like that. You’re recognizing the cost of having the lease (interest + amortization), not just the cash outflow. It’s like saying, “I spent $2,400 worth of value, even though my wallet only lost $2,000.” Your wallet is confused but your financial statements are thrilled.
What About Variable Payments or Lease Modifications?
Oh, you want to spice things up? Fine. What if your lease says you pay extra if the office coffee machine breaks (variable payments). Or what if you decide to extend the lease for two more years (modification)? In those cases, you need to recalculate your liability and adjust the ROU asset. It’s like accounting yoga — you stretch the numbers until they fit.
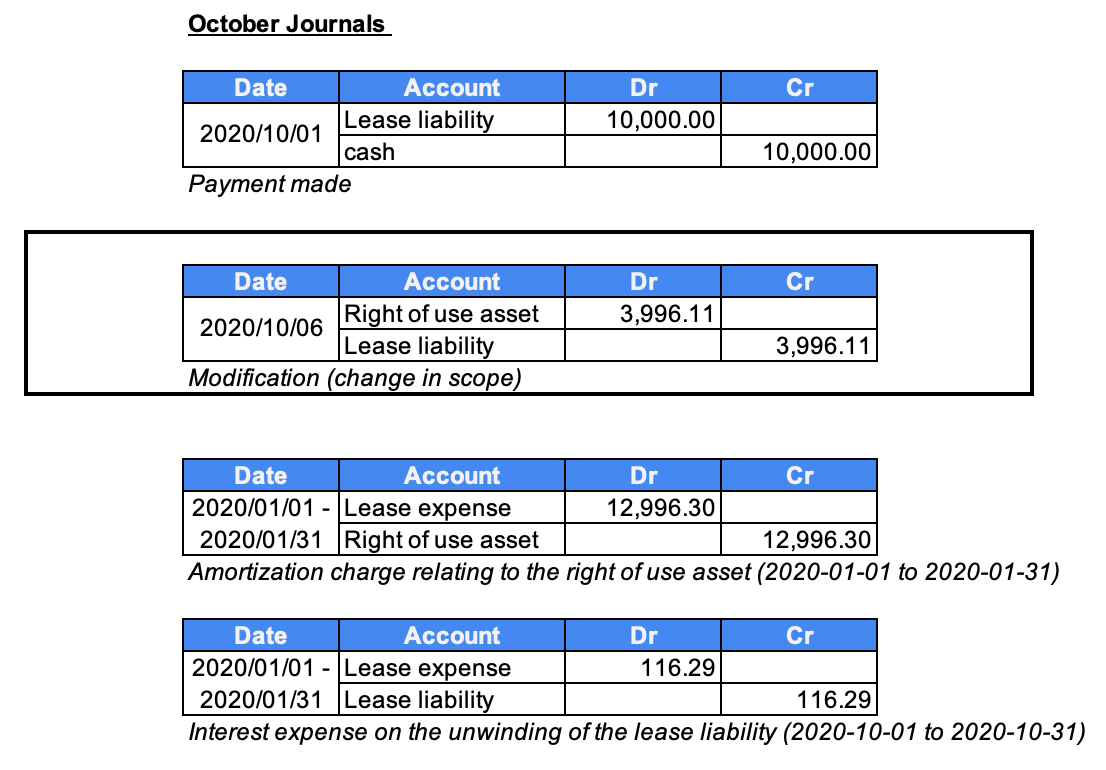
For example, if you extend the lease, you add the new payments to the liability and add to the asset. Journal entry:
Debit: Right-of-Use Asset $20,000
Credit: Lease Liability $20,000
See? Even when things change, the ROU and liability remain besties. They just have a longer commitment now.
Common Pitfalls (Don’t Laugh, You’ll Do It Too)
One common mistake is forgetting to reclassify the portion of the lease liability due within one year. If your lease payment schedule has a chunk due soon, move it from “non-current” to “current” liabilities on the balance sheet. Otherwise, your auditor will give you a look that says, “Really?”
Another classic blunder? Using the wrong discount rate. Use the rate implicit in the lease if you can find it (good luck), otherwise use your incremental borrowing rate. And please, don’t guess. That’s like playing darts blindfolded with your company’s financial statements.
The Uplifting Conclusion (I Promise)
So there you have it: lease accounting journal entries in all their glory. They look complicated, but at the end of the day, it’s just a story about commitment — a commitment to pay, a commitment to use, and a commitment to accurately report it all on paper (or a screen).
Remember, every lease entry brings you one step closer to financial clarity. And clarity is the cousin of confidence. So go ahead, book that entry. Crush that amortization. You’re not just an accountant or a business owner — you’re a lease whisperer.
And if you ever get stuck, just imagine the ROU Asset and Lease Liability doing a little dance of balance in your general ledger. They’re happy. You’re happy. And the numbers all match. Smile — you just mastered lease accounting.