
Can You Endorse A Check To Someone Else

So you’ve got a check made out to you—maybe from Grandma for your birthday, or a refund from that subscription you forgot about—and you think, “You know what? I’d rather my buddy Dave have this cash.” Can you just hand it over and let him cash it? The short answer is: yes, you can! But it’s a little trickier than scribbling your name on the back and passing the buck (literally).
Let me introduce you to the glorious, slightly strange world of check endorsements. When you sign the back of a check, you’re giving the bank a little love note that says, “I, the rightful owner, am okay with this money moving along.” And yes, you can write a note that says, “Pay to the order of Dave,” and then sign it. But—and there’s always a “but”—banks have rules, and they’re not all the same.
The Magic Phrase: “Pay to the Order Of”
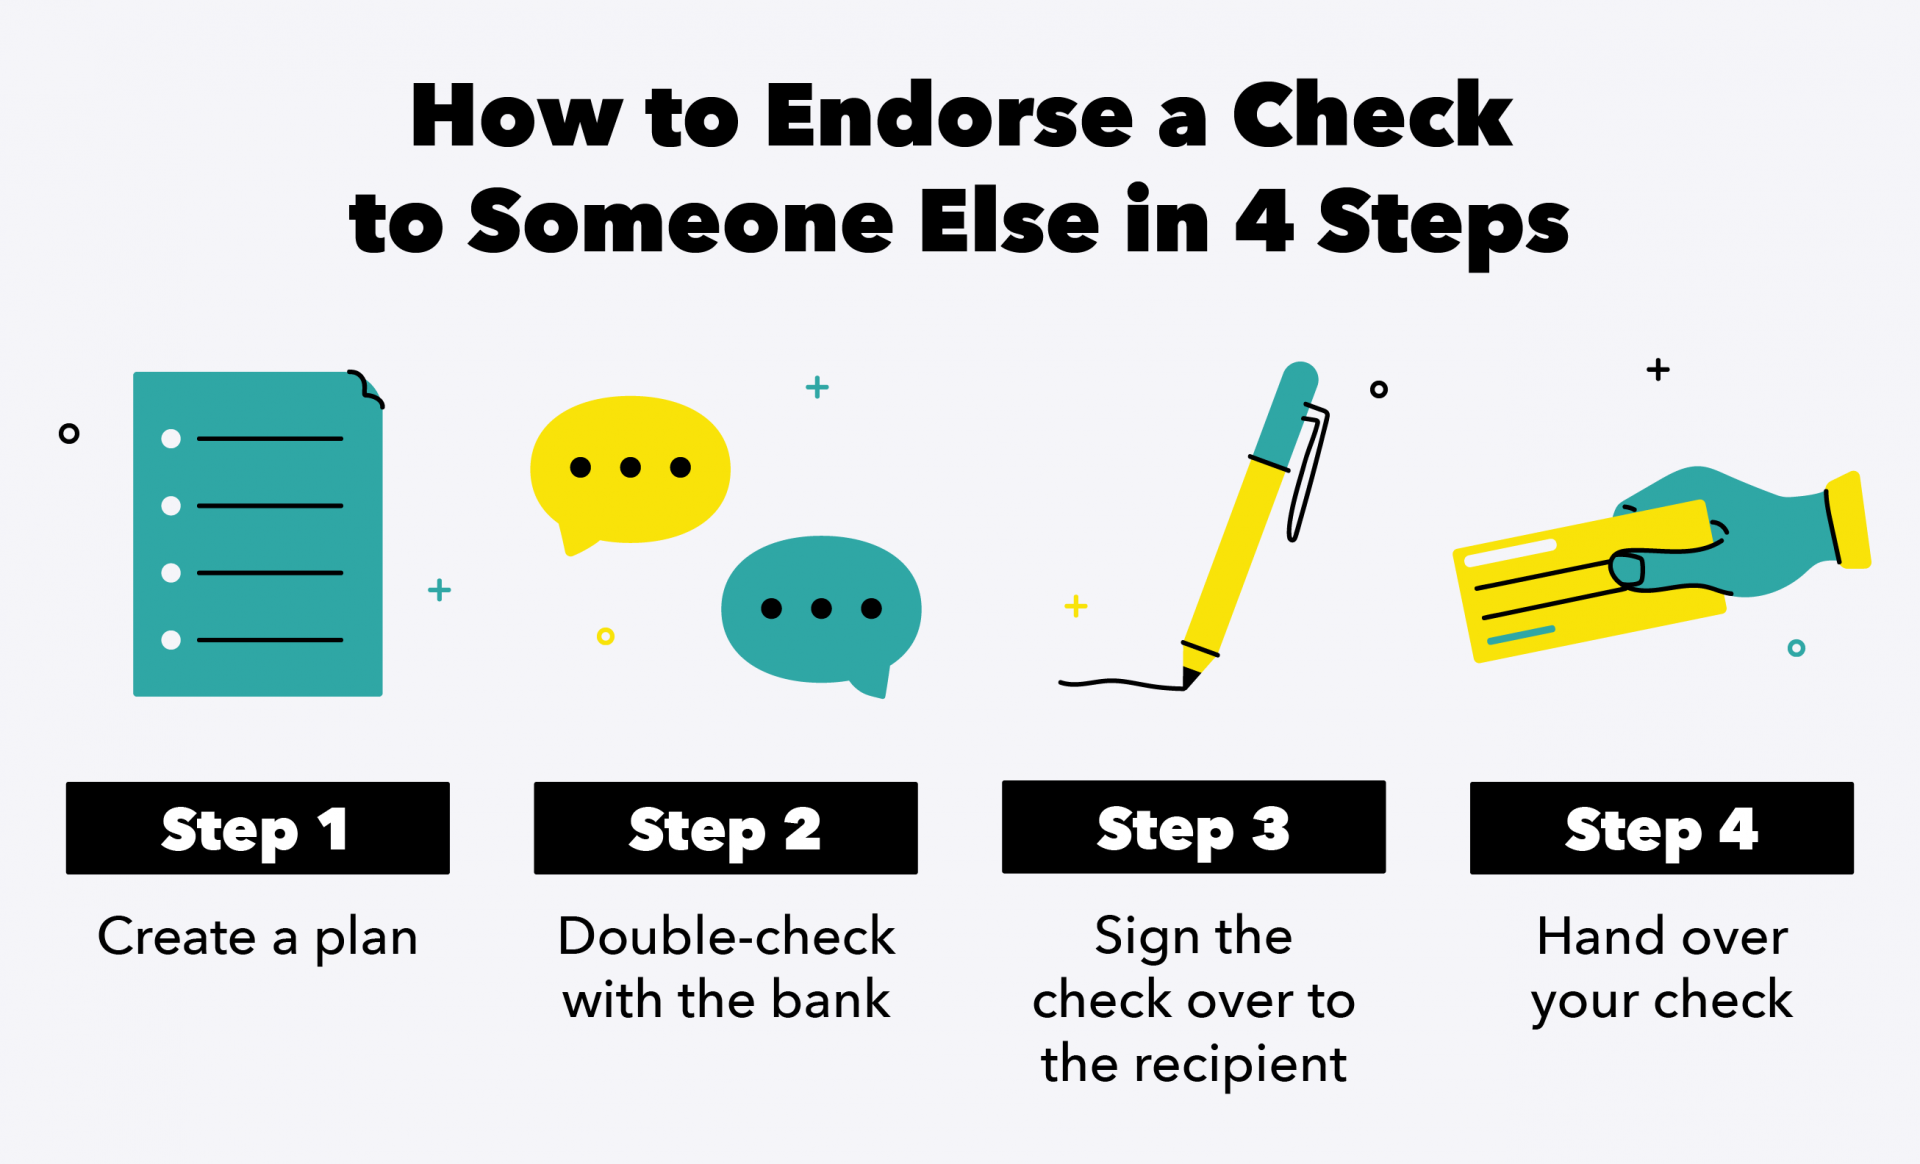
Here’s how you do it, step by step, without making the bank teller laugh at you (too much). On the back of the check, in the endorsement area (usually a 1.5-inch strip of pure real estate), you write: “Pay to the order of [Friend’s Name].” Then, you sign your name right below it. That’s it! It’s called a special endorsement, and it’s like handing Dave the keys to your financial mini-van.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
But wait—Dave’s bank might not be as chill as you are. Many banks today treat a third-party check like a suspicious clown at a kids’ party. They might require Dave to come in with you, the original payee, or they may simply refuse to cash it. The bigger and more modern the bank, the more likely they are to say, “Nope, too risky—go deposit it yourself.”
Why the paranoia? Fraud, baby! Banks hate the idea of someone faking an endorsement. So if you’re checking Dave’s ID and he looks shifty, maybe don’t endorse it to him. But if it’s your trustworthy bestie, go for it—just know the bank might give you both the side-eye.
When It’s Actually Super Easy (and When It’s Not)
If you’re at a credit union or a small community bank, you’re golden. Those places often treat you like family, and they’ll take the check with a smile and a wave. I once endorsed a check to my sister at a tiny credit union, and the teller high-fived me—true story. Okay, maybe not the high-five, but it was painless.
On the flip side, if you try this at a big box bank like Chase or Wells Fargo, prepare for a potential sob story. Many of them will refuse to cash a third-party check unless you’re both standing at the counter, IDs in hand, looking like you just met for a coffee date. Some won’t even let you deposit it into Dave’s account unless you’re there, too. It’s their way of saying, “We trust you, but we don’t trust the universe.”

And here’s the real kicker: Mobile deposit? Forget about it. You can’t snap a photo of a check endorsed to someone else and expect the app to know what’s up. The app will cry and ask, “Is this a joke?” Stick to in-person handoffs for this trick.
The “Blank Endorsement” Trap (Don’t Do This)
Now, a word of caution: never just sign the back of the check and hand it to Dave blank. That’s called a blank endorsement, and it’s like leaving your front door wide open with a neon sign that says, “Free money!” Anyone—and I mean anyone—could pick up that check, write their name above your signature, and waltz off with your birthday cash. Scary stuff, right? Always use the “Pay to the order of” method to keep it locked down.
Also, if the check is from the government (tax refund, stimulus, unemployment), you can just forget about endorsing it to someone else. Uncle Sam really doesn’t like third-party endorsements on government checks. They’ll bark “No way!” and you’ll be stuck mailing it back. Stick to personal checks or business checks from places that aren’t the IRS.
Pro Tips for the Smooth Operator
If you’re determined to endorse a check to a friend, here’s how to make it painless: Go to the bank together. Both of you bring valid, unexpired IDs. Smile at the teller. Say, “We’d like to deposit this check into Dave’s account—I’m the original payee, and I’m endorsing it to him.” It sounds formal, but it works like a charm. Bonus points if you both wear matching hats.
Another option? Just deposit the check yourself and then Venmo Dave the money. That way, you avoid the bank drama, and you can add a funny emoji to the payment. Plus, you get to feel like a financial superhero for two whole minutes.
And if the check is for a large amount—say, over $1,000—some banks will put a hold on it for days, even if the endorsement is perfect. So don’t plan on Dave buying you pizza with the cash that same afternoon. Patience, grasshopper.
The Bottom Line (Spoiler: It’s a Yes, But…)
So, can you endorse a check to someone else? Yes, you absolutely can—just be ready for a few hurdles. The key is to use the “Pay to the order of” endorsement, bring your ID, and don’t try it with government checks or your banking app. Think of it like lending your favorite hoodie to a friend—it’s doable, but sometimes the laundry room (or the bank) makes it complicated.
But here’s the uplifting part: You have the power to share your good fortune. When you endorse a check to someone else, you’re not just sliding paper around—you’re passing along a little kindness, a slice of your birthday cheer, or a refund that says, “Hey, I’ve got your back.” In a world that often feels complicated, that simple act of trust is pretty darn beautiful. So go ahead—scribble that “Pay to the order of” and make someone’s day. Just make sure they buy you coffee first. You’ve earned it.