<article>
<p>Okay, so picture this: you're sitting at the kitchen table, sipping your morning coffee, scrolling through your phone like you do every single day. Then you see a headline about a <strong>coding error that shredded the credit reports of millions of people</strong>. You blink, look around, and wonder... wait, could that be <em>me</em>?</p>
<p>Spoiler alert: it might very well be. And you could actually be owed some money because of it.</p>
<h2>What Even Happened?</h2>
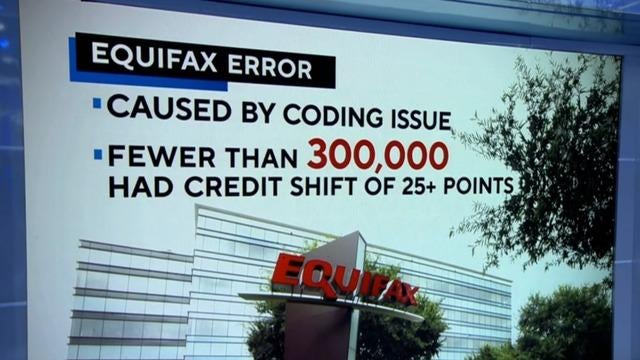
<p>Here's the short version. In 2022, a <strong>colossal coding error</strong> at Equifax — one of the biggest credit bureaus in the country — messed up the financial data on an enormous number of consumers. We're talking about millions of people whose credit information was slapped with the wrong stuff.</p>
<p>Think of it like a barista misspelling your name on the cup. Except instead of "Cara" becoming "Coral," your <em>actual credit score</em> got tangled up with someone else's late car payment or a mortgage you never had. That little mistake? Not so little when it's your whole financial reputation on the line.</p>
<p>The error affected paperwork from at least <strong>three million North Carolina residents</strong> alone in related reports, and the broader impact painted across the entire U.S. was staggering. People saw their scores drop for reasons they couldn't even explain. Others were denied loans and apartments without ever knowing why.</p>
<h2>Why Should You Care?</h2>
<p>Let me give you a little everyday comparison. Imagine you're the most responsible roommate ever — you always pay rent on time, you never leave dishes in the sink, you even split the internet bill. Then one day your landlord says, "Sorry, we've got you confused with the chaotic neighbor from 4B."</p>
<p>You'd be furious, right? That's essentially what happened to <strong>millions of people> whose credit reports were hijacked by an error beyond their control.</p>
<p>Your credit score isn't just some random number. It decides whether you get approved for a car loan, whether your mortgage application gets the green light, and sometimes even whether you land that apartment you've been eyeing. So when someone else's mess shows up on <em>yours</em>, it absolutely matters.</p>
<h2>The Settlement — Free Money?</h2>
<p>Now here's where it gets exciting. Equifax has reached a settlement — a <strong>settlement check is literally waiting for eligible people</strong> affected by the coding error. We're talking about reimbursements for the headaches, the denied applications, and the sheer inconvenience of having your life confused with someone else's.</p>
<p>This isn't a lottery. It's not a scammy email promising you $7 million because a distant relative passed away. It's a legitimate settlement designed to make injured parties whole again.</p>
<p>But — and there's always a "but" — you actually have to <em>check</em> if you're on the list. And that requires you to take a few minutes out of your day. I know, I know... it's not exactly as thrilling as binge-watching your favorite show.</p>
<h2>How Do You Check?</h2>
<p>First things first, <strong>pull your free credit reports</strong> from the official source. You can do this at annualcreditreport.com once a year — think of it like your annual health checkup, but for your finances.</p>
<p>Then, <strong>look for any elements that don't belong</em>. Did a mysterious account pop up that you swa your spouse about? Did your score inexplicably tank even though you're the most financially cautious person you know? That's your red flag.</p>
<p>From there, the settlement website provides a simple process to check your eligibility. It takes less time than waiting for water to boil. Seriously.</p>
<h2>Don't Let It Slip By</h2>
<p>Here's the thing about pieces of free money sitting in settlement funds — they don't collect themselves. If you don't act, it just sits there unclaimed while you go back to another boring Tuesday.</p>
<p><strong>The coding error wasn't your fault</strong> — not even close. You didn't type those wrong responses into a system. You didn't jumble raw data across millions of records. Somebody else dropped the ball, and now there's a fair process to make things right.</p>
<p>So grab that second cup of coffee, open up your laptop, and take five minutes to see if you qualify. Worst case scenario? You learn a little more about your credit report. Best case? You find some extra cash landing in your mailbox for a change of drama-free reasons.</p>
<p>Because if there's one thing we can all agree on, it's that we'd much rather have unexpected money than unexpected credit damage from someone else's <em>coding mistake</em>.</p>
</article>
