
How To Solve Bank Reconciliation Statement Problems
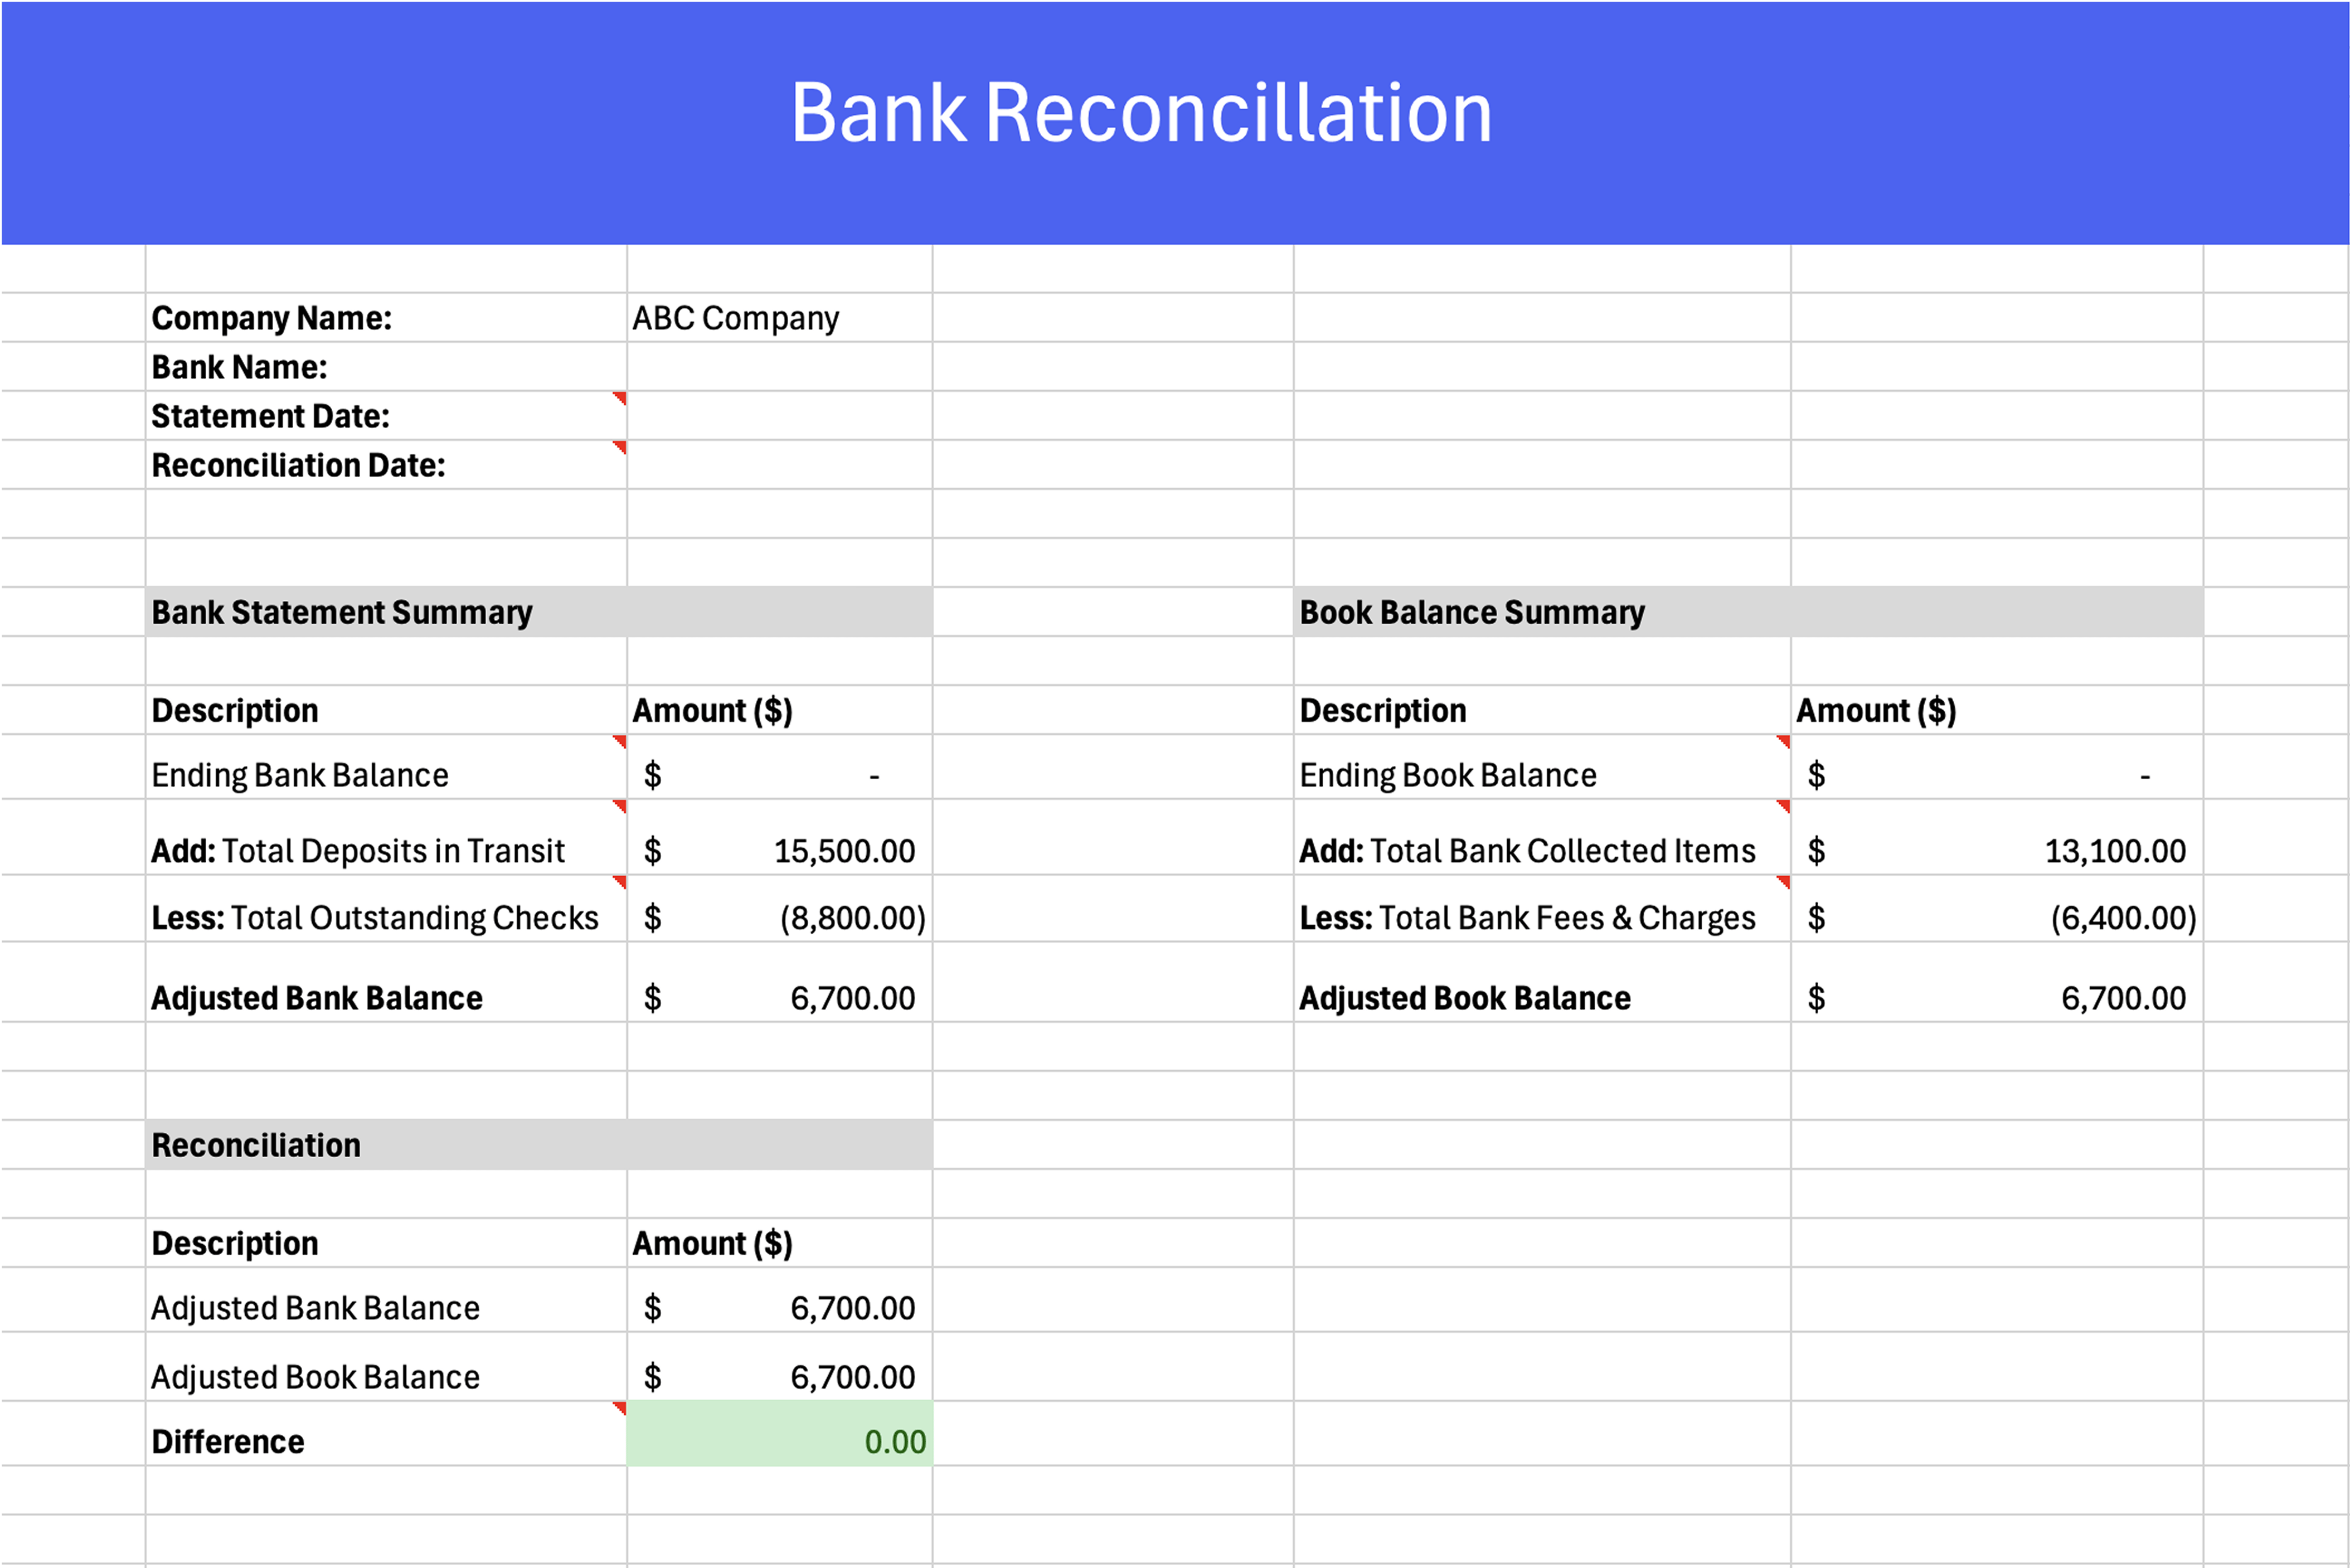
For individuals and businesses alike, managing finances is a crucial aspect of everyday life. One of the key tools used to ensure accuracy and integrity in financial management is the Bank Reconciliation Statement. This statement is a critical component that helps in identifying and resolving discrepancies between a company's or individual's financial records and the bank's records.
The primary purpose of a Bank Reconciliation Statement is to reconcile the difference between the bank balance as per the bank statement and the bank balance as per the company's or individual's own accounting records. This process is essential for detecting any errors, omissions, or frauds that might have occurred.
In practical scenarios, discrepancies can arise due to various reasons such as timing differences in recording transactions, bank charges, or even NSF checks. The Bank Reconciliation Statement helps in identifying these discrepancies and taking necessary actions to rectify them, thereby ensuring the accuracy of financial statements.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
To solve Bank Reconciliation Statement problems, one should start by carefully comparing the bank statement with the internal financial records. This involves checking for any unrecorded transactions, errors in recording, or missing entries. It's also important to consider any bank charges or interests that may not have been accounted for internally.
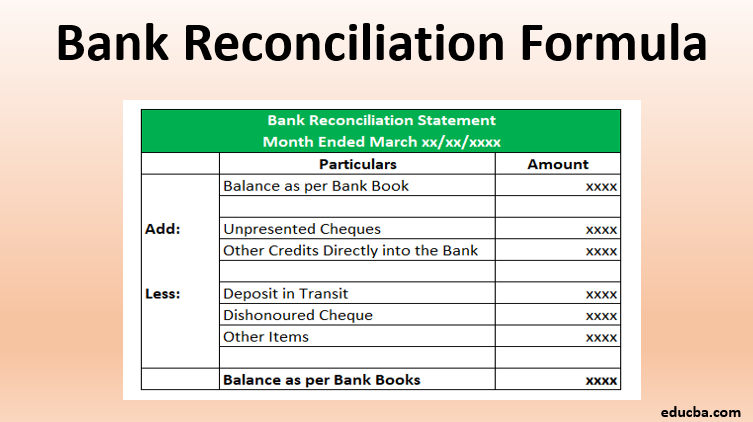
For those looking to explore this topic further and improve their skills in solving Bank Reconciliation Statement problems, a simple tip is to regularly review and update financial records, ensuring all transactions are accurately recorded and reflected in both internal records and the bank statement. Utilizing accounting software can also streamline this process and reduce errors.
By understanding and effectively using the Bank Reconciliation Statement, individuals and businesses can enhance their financial management, reduce errors, and improve their financial integrity. This is a valauble skill that offers numerous benefits in everyday life, from personal finance management to professional accounting practices.