
What Happens To 401k When You Leave A Job
So, you’ve quit your job. Maybe you “took this opportunity to pursue other interests” (read: you finally told your boss where to stick that spreadsheet). Congratulations! But now, in the back of your mind, a tiny little panic is happening. It’s your 401k, and it’s sitting there like an awkward houseguest who doesn’t know the party is over.
First, let’s get the scary part out of the way. You won’t lose your 401k money. I know, shocking. It’s not like that $50 you left in your gym locker in 2015. The money is yours—legally, permanently, and stubbornly yours. The government guards it like a hawk guarding a bag of shiny rocks. But what you do with that account now is where the real comedy—and potential tragedy—begins.
Option One: The “I’ll Deal With It Later” (The Zombie Account)
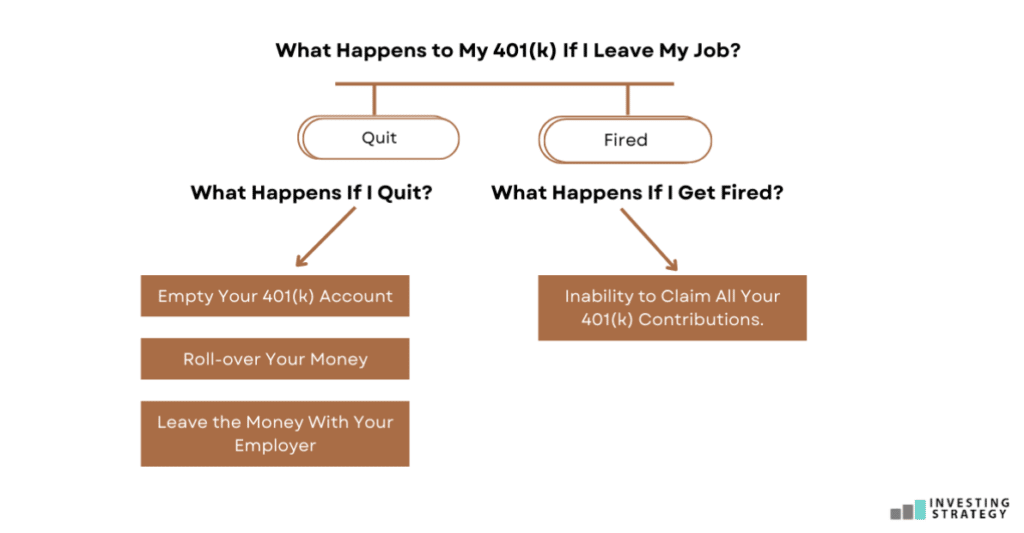
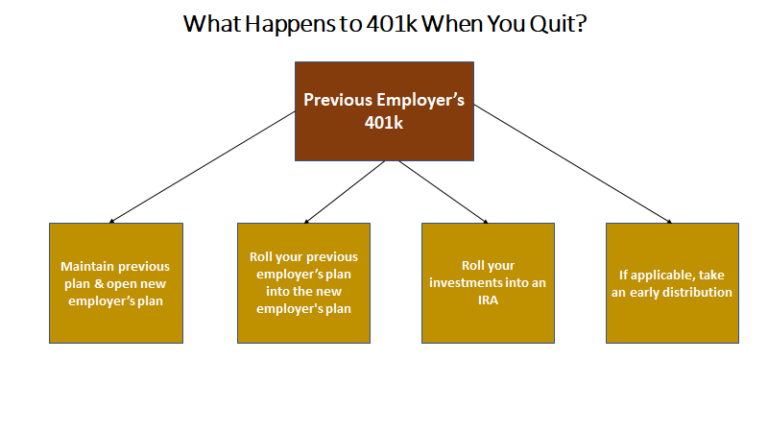
You can just leave your 401k with your old employer. It sits there, like a zombie in a server room, barely alive, slowly decaying. This is actually fine for a while. Your money keeps growing (or shrinking, thanks, stock market), but you cannot add more money to it. It’s like a plant you stop watering—it won’t die, but it won’t flourish either.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
But here’s the surprise: if your old balance is under $5,000, your ex-boss can legally roll it into an IRA for you, or even send you a check. If it’s under $1,000, they might just cut you a check and say, “Good luck, champ.” That leads to the next horror show.
Warning: The “Cash-Out Gremlin”
You might be tempted to just take the cash. “Rent is due, and I need a new espresso machine,” you think. Do not do this. Cashing out a 401k is like setting your money on fire and using the ashes to pay a 40% tax bill. You’ll pay income tax on the whole amount plus a 10% penalty if you’re under 59½. It’s the financial equivalent of slapping yourself in the face while wearing a cactus glove.
A surprising fact: According to a study by Vanguard, about 40% of people cash out their 401k when changing jobs. That’s millions of people turning their retirement into a “meh” Tuesday night pizza. Don’t be that person.

Option Two: The Rollover (The Smart, Boring Move)
This is the hero move, the “I read the manual” choice. You take your 401k and roll it over into an IRA (Individual Retirement Account) at a brokerage like Vanguard, Fidelity, or Schwab. Why? Because you become the boss of your money. You can choose any investment—stocks, bonds, even a mutual fund that only buys companies that make dog toys. The fees are usually lower, and you have total control.
It’s like taking your money out of a boring beige cubicle and moving it into a cool hacker loft. You can even roll it into your new employer’s 401k, if they have one. Just make sure the transfer is a “direct rollover.” The money goes straight from one account to the other, without touching your hot little hands. If you take a check yourself, the taxman will be waiting outside your door, licking his chops.
But Wait—There’s a Secret Bonus
Roth 401k accounts? If you had one, you can roll that into a Roth IRA. And here’s the joke: all your contributions are already taxed, so the growth is tax-free forever. It’s like planting a tree that grows dollar bills, and the IRS just waves at it from a distance. But if you roll a regular 401k into a Roth IRA, you have to pay taxes on the conversion. Ouch. Do your homework, or ask a tax guy. Seriously.
Option Three: The “What About My Company Stock?” (Oops)
If your 401k was loaded with your old company’s stock, watch out. You might have Net Unrealized Appreciation (NUA)—a fancy term that means you can pay lower capital gains taxes on that stock if you move it to a taxable brokerage account instead of an IRA. It’s a weird loophole, like finding a coupon for a Ferrari. Consult a pro. Most people ignore this, which is like walking past a $100 bill on the sidewalk because you’re texting.
The Absolute Worst Thing You Can Do
Forget about it. I mean genuinely forget. The account sits there for ten years, you lose the login, the company gets bought by another company, and suddenly your money is held hostage by a customer service robot named “Susan.” Track down your old accounts using the National Registry of Unclaimed Retirement Benefits. It’s a real website! You might find $12,000 you forgot about, or a $43 fee from a yogurt shop you used in 2018. Both are thrilling.
Finally, here’s the truth: leaving a job is like breaking up with a bad relationship. Your 401k is your emotional support animal. Don’t abandon it. Roll it over, keep it safe, and let it grow up to become a beautiful, tax-advantaged adult that buys you a beach house in 30 years. Or at least a nice hammock and a beer.
Now go update your LinkedIn profile and stop worrying. You’ve got this. And Susan the robot can’t have your money.