
Can You Lose Your 401k If You Leave A Job

So, you’re thinking about leaving your job. Maybe you’ve found a shinier opportunity, or maybe your boss just microwaved fish in the break room again. Either way, a big question is probably bouncing around your brain: Can I lose my 401k?
Let me set your mind at ease right now. No, you will not lose your 401k when you leave a job. It’s not like a library book you forgot to return—there’s no late fee, and the government isn’t sending a ninja to confiscate it. Your money is your money.
The Great 401k Myth-Busting
The biggest fear I hear is that your 401k just vanishes into a black hole when you resign. That’s ridiculous. Your 401k is a bucket of cash and investments, not a magic trick.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Think of it like a bank account you opened alongside your employer, not one they own. You brought the cash (your contributions), and maybe they brought some (their match). Once it’s in there, it’s legally yours, even if you quit on a Tuesday afternoon.
The only time you could lose it? If you cash it out without reinvesting it. That’s like burning your retirement money for warmth—not a good plan.
What Actually Happens To Your Money
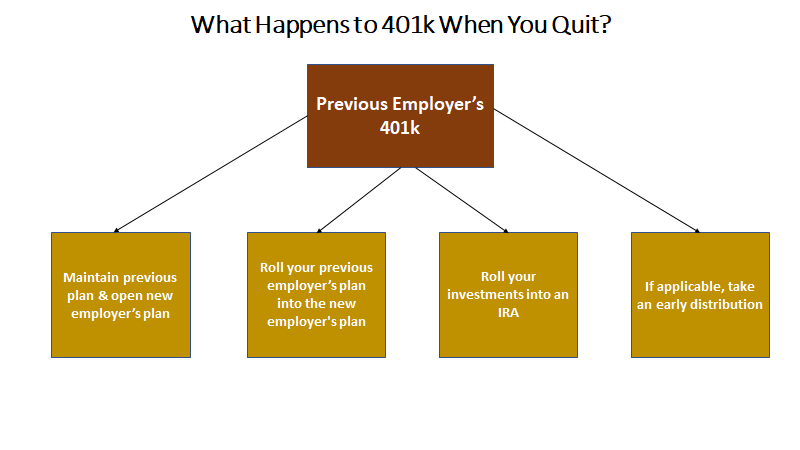
So, your money doesn’t disappear. But where does it go? You’ve got a few fun choices, and each one has a goofy nickname. Let’s break ’em down.
Option one: Leave it where it is. Your old 401k can just sit there, collecting dust and interest. It’s like leaving your favorite sweater at your ex’s house—it’s safe, but a little awkward.
Option two: Roll it over to your new job’s 401k. This is the smooth move. You transfer the money like a relay race, and your new boss cheers you on (metaphorically).
Option three: Roll it into an IRA. This is the DIY route. You open a fancy personal retirement account, and your 401k money takes a road trip there. No tax penalties, just freedom.
Option four: Cash it out. This is the trap. If you take the money as cash, Uncle Sam and your state will take a huge bite. Plus, you’ll pay a 10% penalty if you’re under 59½.
The Sneaky “Vested” Trap
Here’s one tiny, sneaky thing that can trip you up: vesting. Your employer’s contributions might be on a vesting schedule. Think of it like a loyalty program.
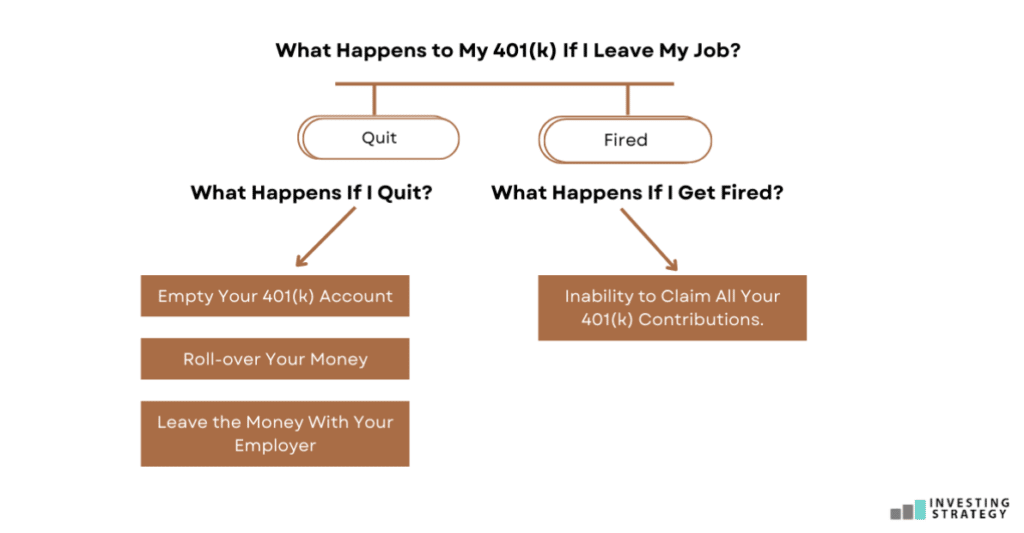
If you leave before you’re fully vested, you might lose their part of the match. Your contributions are always yours, but the free money your boss threw in? That could vanish if you bolt too early. Check your plan’s vesting schedule—it’s usually one to five years.
Example: If you’re only 50% vested and leave, you keep half of their match. The other half poofs away. It’s not the end of the world, but it’s a bummer, like leaving a party right before they serve cake.
What About That Horrible “Lost” 401k Story?
You’ve heard the urban legend: someone left a job, forgot about their 401k, and ten years later it was gone. That’s mostly fiction. The money doesn’t vanish.
If you forget about it, the plan administrator will keep it safe. They might charge small fees over time, but they won’t just eat your cash. If you truly vanish off the grid, the money eventually goes to the state as “unclaimed property.”
And guess what? You can still claim it! It’s like finding a $20 bill in an old coat pocket, but way bigger. The state holds your money until you show up with ID. So no, you don’t lose it forever.
The “Oops, I Forgot” Checklist
Don’t be that person who loses track of thousands of dollars because they were too busy binge-watching a show. Here’s a three-step plan:
First, don’t panic. Your money is fine. Second, call your old HR or the 401k provider. They’ll tell you exactly what you can do.
Third, pick your move (roll over, leave it, or cash out). If you’re clueless, just roll it into an IRA. It’s the easiest, and you avoid all taxes and penalties.
One joke truth: If you leave your 401k behind for too long, it might grow a beard. But it’s still yours.
The Real Danger: Doing Nothing
The real risk isn’t losing your 401k—it’s forgetting to manage it. If you have five old 401ks from five jobs, you’ll forget which one is which. It’s like having five savings accounts and not knowing the passwords.
Consolidate them! Roll them into one IRA or your current 401k. It makes life so much simpler. Plus, your future self will thank you when you’re retired on a beach, sipping a drink with an umbrella.
And hey, if you ever do lose track, there’s a government website called unclaimed.org that can help you find lost money. Seriously. It’s like a treasure map for adults.
Uplifting Conclusion: You’ve Got This
Leaving a job is scary enough without worrying about your retirement savings. But here’s the good news: your 401k is yours. It’s not a gift your boss can take back. It’s not a punishment for quitting. It’s your hard-earned money, growing quietly in the background.
So, whether you roll it over, leave it be, or cash it out (please don’t cash it out!), you are in control. You’re the captain of this retirement ship. And even if you make a mistake, it’s usually fixable. Life is long, and retirement accounts are forgiving.
Besides, the fact that you’re even thinking about your 401k means you’re already ahead of half the planet. So go ahead—leave that job, chase your dreams, or just escape the fish-microwaver. Your retirement savings will be right there, waiting for you with open arms (and compound interest).
And if you ever feel lost? Just remember: absent 401k is still your 401k. Now go forth and prosper—with a smile, a plan, and a 401k that’s safe and sound. 😊