
What Happens To Your 401k When You Quit
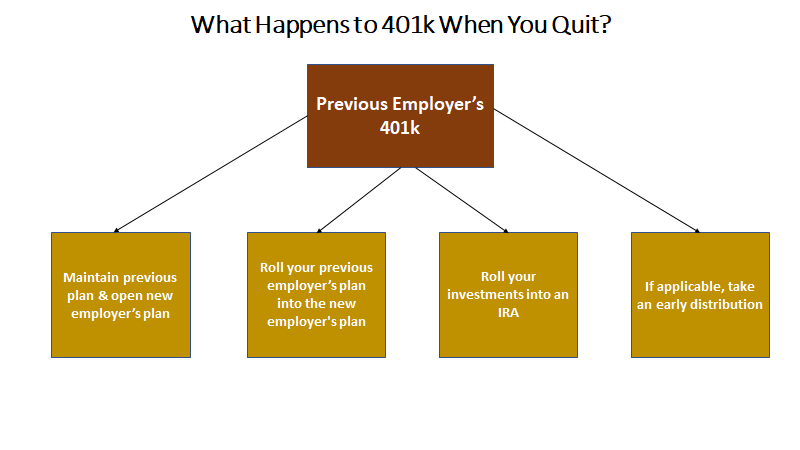
So you did it. You quit your job. Maybe you’re chasing a dream, escaping a soul-sucking cubicle, or just finally snapping after the third “urgent” email at 4:59 PM. Pop the champagne or cry into your pillow—but now your brain is whispering: “Wait, what about my 401k?” It’s like realizing you left a friend behind at a bar after last call. Panic not, my friend. You’ve got options, and they’re all pretty manageable.
The "Leave It Be" Strategy
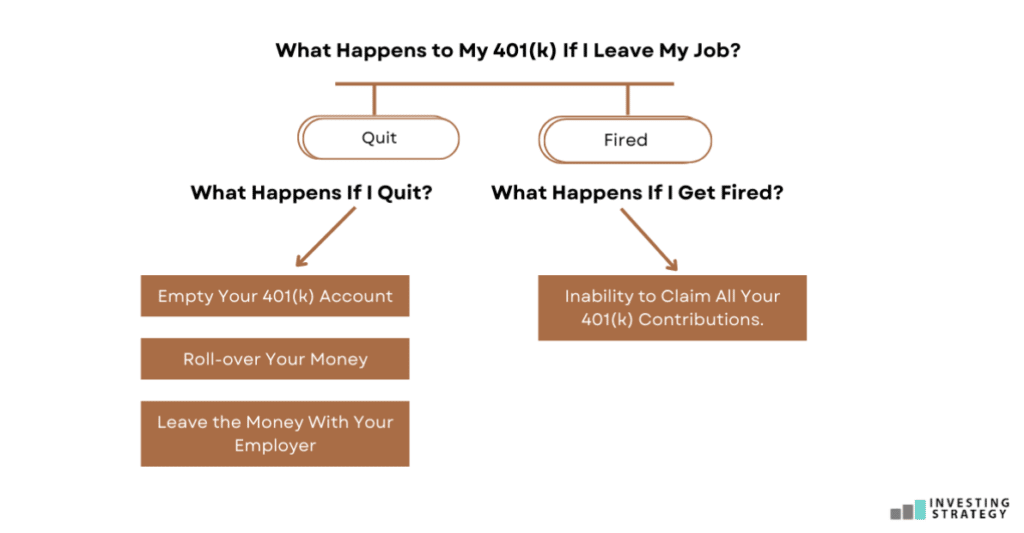
First up: you can just leave the money right where it is—like a forgotten Tupperware in your ex’s fridge. Your old 401k won’t vanish into thin air. It’ll just sit there, earning or losing money, completely oblivious that you’re no longer Tetris-packing spreadsheets for a living.
This is the laziest option. It’s the “I’ll deal with this later” special, and honestly? Sometimes that’s totally fine. You might even get some nice statements in the mail that make you feel like you’re still being paid, minus the actual paycheck and the passive-aggressive notes from accounting.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The catch? Your old company might start charging you maintenance fees, like a storage unit for your retirement dreams. Also, you can’t contribute more to it—it’s a frozen asset, like a microwave pizza that’s been in the freezer since 2019.
Roll It Over to an IRA
This is the grown-up move. You open a shiny new Individual Retirement Account (IRA) with a brokerage like Vanguard, Fidelity, or Schwab, and you simply roll that old 401k into it. Imagine scooping your goldfish from a sad bowl into a glittering, heated aquarium.
Why do this? Because you get total control. You can invest in anything—not just the five boring mutual funds your old employer picked. Want to bet on electric luge companies or index funds that track the entire stock market? Go wild, you magnificent adult.
Plus, it keeps your money consolidated. One account, one password, one less thing to forget when you’re filling out your taxes while crying over a burrito. It’s the financial equivalent of Marie Kondo-ing your life: Does this 401k spark joy? No? Then roll it over.
The "Oops, I Forgot" Danger
Here’s where people slip on a banana peel. If you cash out your 401k when you quit—just take the money and run—the IRS will bite you like a caffeinated raccoon. They take a 10% early withdrawal penalty if you’re under 59½, plus you owe income tax on the whole wad.
Cash out a $10,000 account? You might walk away with $6,500 after fees and taxes. It’s like setting a pile of cash on fire to roast a single marshmallow. Fun? Maybe for a split second. Financially stupid? Very much yes.
I once had a buddy who cashed out his 401k to buy a vintage motorcycle. He rode it for a summer, then sold it at a loss. “That’s just the tuition of life,” he said, while eating ramen in an apartment with no A/C. Don’t be that buddy.
Roll It Into Your New Job’s 401k
If your sparkling new employer has a decent 401k plan (no, the one with 2% fees and a “high-growth” fund that only invests in coal mines doesn’t count), you can transfer your old balance there. Think of it as moving your collection of dusty trophies into a nicer curio cabinet.
Major advantage: you keep everything in one place. You only have one login, one password you’ll forget, and one portfolio to nervously check. It’s tidy, like a sock drawer where every sock has a mate.
Downside? Some new plans are worse than old ones. If your new employer’s options are terrible (looking at you, “guaranteed interest account” paying 0.5%), consider the IRA route instead. Don’t marry a bad plan just because you want a single file.
The "Oops, I Forgot to Do Anything"
What if you quit, forget about the 401k for three years, and then your old company goes belly up? Relax—your money doesn’t disappear into a corporate black hole. It’s your money, held by a custodian (usually a big bank). Even if your old employer turns into a pumpkin, the custodian still has your cash, growing slowly like a mossy rock.
But if your account is tiny—say, under $1,000—the company can legally cut you a check and mail it to your last known address. They’re basically saying, “Here’s your $843. Good luck, champ.” Then you’ll have 60 days to roll it over before taxes and penalties hit. So keep your address updated, or your 401k might end up in your dead uncle’s mailbox.
The Emotional Reality
Look, we all know quitting a job is wired into your lizard brain as a risk. Your 401k feels like a security blanket. Moving it around is like trying to fold a fitted sheet—confusing and slightly frustrating, but not impossible.
Just pick one of these paths. Don’t cash out unless you’re about to become homeless or need to start a goat yoga studio. And for the love of compound interest, don’t just ignore it forever.
You got this. Now go celebrate your freedom—and maybe schedule a 15-minute call with a financial advisor. They’ll make you sound smart, even if your 401k is currently in the “shoebox under the bed” phase.