
What Happens To My 401k When I Quit
So, you’ve finally decided to quit your job. Maybe you’re chasing a dream gig in a new city, or you’re just tired of your coworker Dave who microwaves fish every Tuesday. Either way, you’ve got one big question lurking in your head: What happens to my 401k when I walk out that door?
Here’s the good news: you don’t lose that money. It’s yours—like that favorite hoodie you “borrowed” from your sibling years ago. The 401k is your hard-earned cash, not a gift from your boss. Your employer can’t snatch it back, even if they’re grumpy about you leaving.
But wait—there’s a twist. You have choices, and some of them can either make your future self do a happy dance or send them face-palming. Let’s break it down like you’re explaining it to a friend over coffee.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
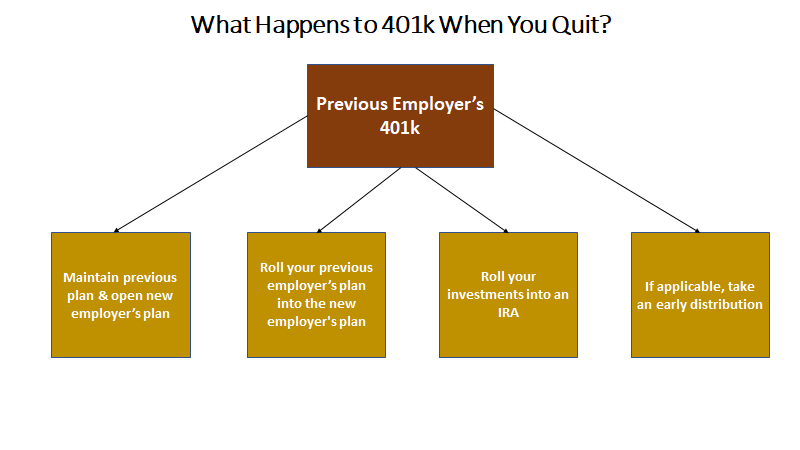
Option 1: Leave It Alone (The “Set It and Forget It” Move)
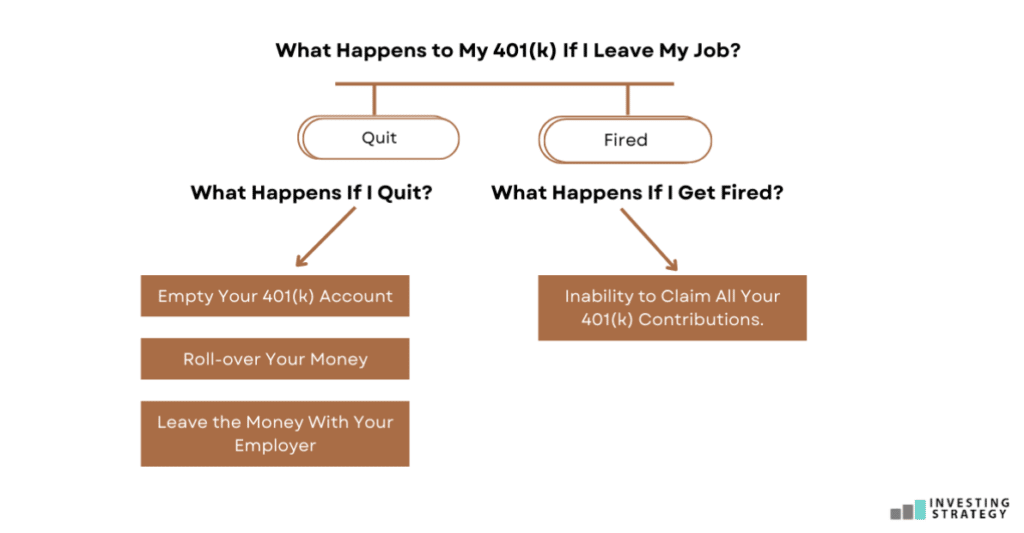
You can literally do nothing. Your 401k stays right where it is, in your old employer’s plan. It’s like that gym membership you never use—it just sits there, slowly growing (or shrinking) with the market.
This is easy, but not always smart. If you have less than $5,000 in the account, many companies will force you out after a few months. They’ll send you a check or roll it into an IRA. And if you forget to move it yourself, they might cut you a check you’ll have to cash—and then pay taxes on.
Also, you can’t add new money to an old 401k. It’s like having a savings jar that you can’t put any more coins into. So, fine for a short break, but not a long-term plan if you want to keep building wealth.
Option 2: Roll It Into Your New Job’s 401k (The “Hook Up” Strategy)
If your new company offers a 401k, you can roll over your old balance into it. Think of it like moving your favorite playlist from your old phone to your new one. All your songs (and money) come along seamlessly.
This is great because you keep all your retirement savings in one place. You can keep contributing and maybe even snag a company match. Plus, you avoid the temptation to spend it on a shiny used car (more on that below).

Just make sure you do a direct rollover—where the money goes straight from one account to the other. If they send you a check first, you have 60 days to deposit it, or the IRS will treat it as a withdrawal and tax you like crazy. Yes, it’s as stressful as finding a parking ticket on your windshield.
Option 3: Roll It Into an IRA (The “Freedom” Route)
This is my personal favorite. You open an IRA (Individual Retirement Account) at a place like Vanguard, Fidelity, or Schwab. Then you move your 401k money there. It’s like taking your collection of vinyl records from a dusty attic to a cool, organized shelf where you control the playlist.
With an IRA, you have way more investment choices. Instead of just a few boring mutual funds your old job picked, you can buy stocks, bonds, ETFs, or even index funds that track the whole market. It’s like upgrading from a frozen pizza to a gourmet kitchen.
Plus, IRAs often have lower fees than 401k plans. Over 30 years, even a 1% fee difference can cost you tens of thousands of dollars. That’s real cash that could go toward a beach house or a lifetime supply of avocados.
Option 4: Cash It Out (The “Don’t Do It” Trap)
I know it’s tempting. You’re staring at a big pile of cash and thinking about that vacation to Bali or paying off credit card debt. But cashing out your 401k is like eating your emergency chocolate stash when you’re not even hungry—it feels good for a second, then you regret it.
Here’s the math: If you cash out $10,000, the government takes 20% for taxes upfront (maybe more). Plus, you’ll pay a 10% penalty if you’re under 59 ½. So you get about $7,000 in hand. That $3,000 you lost? That’s the price of a nice used couch or a round-trip plane ticket. Not worth it.
Only cash out if you’re facing a real emergency (like eviction or medical bills). Otherwise, treat that 401k like a wild animal in a cage—admire it, don’t poke it.
What If You Forget About It Entirely?
If you’re like me and have the memory of a goldfish, you might just leave the 401k at your old job and forget about it. That’s fine for a year or two. But after about three years, if the balance is small, your old company might close the account and send you a check.
And then you’re stuck with that cash-out problem again. So, do future-you a favor: set a reminder on your phone to handle it within three months of quitting. Future-you will thank you with a virtual high-five.
The Bottom Line (With a Smile)
Quitting a job is a big step—like breaking up with a bad haircut. Your 401k doesn’t have to be a drama. Just remember: roll it, don’t spend it. Choose one of the first three options, and you’ll be set for a cozy retirement where you can finally afford those expensive avocados.
And hey, if you mess up? Don’t panic. The IRS isn’t the friendly neighbor, but you have time to fix mistakes. Just call your new retirement provider or a tax pro. They’ve seen it all before—even the fish-microwave guy’s 401k.
So go ahead, hand in that resignation letter. Your future self is already smiling, sipping lemonade on a porch you paid for with smart rollovers. You’ve got this.