
When Do Car Insurance Rates Go Down

You know that feeling when you open your car insurance renewal notice? It’s like finding a credit card bill from a vacation you don’t remember taking. Your heart drops, your wallet twitches, and you start wondering if you accidentally bought the “platinum, gold, and diamond-encrusted” package. The big question on every driver’s mind is: when does this madness finally chill out? Let’s be real — insurance companies aren’t exactly handing out free hugs, but they do have a few moments of mercy.
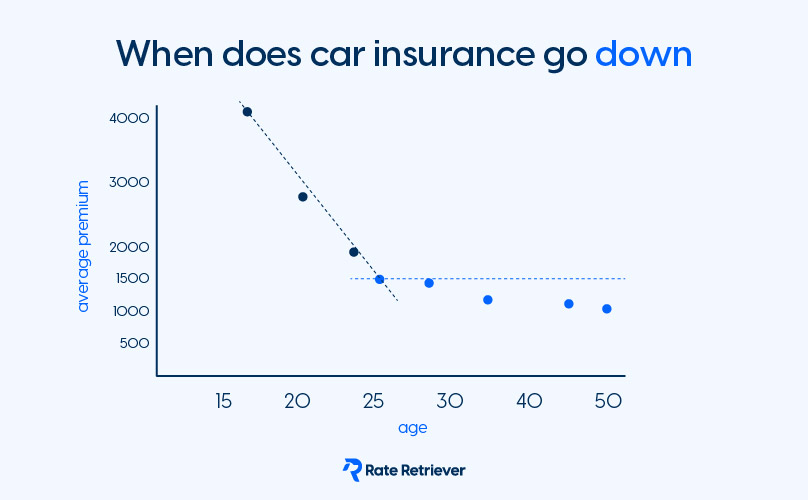
The Birthday Cake of Savings: Turning 25
If you’re under 25, your insurance rate is basically judging you for existing. It’s like being at a party where everyone thinks you’ll spill red wine on the carpet. But the moment you blow out the 25 candles, something magical happens. Your rate drops like a bad habit.
I remember my 25th birthday: I didn’t just get a cake — I got a $300 annual discount. It felt like my insurer sent me a card that said, “Okay, you’re officially not a menace to society. Congratulations.” Statistically, 25 is the age when you’re less likely to crash your car while trying to parallel park after three cups of coffee. So, yes, age works in your favor, but only if you don’t celebrate your birthday by doing donuts in a parking lot.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
No Tickets, No Problem: The Clean Record Discount
Another way rates go down? Stop driving like you’re in a Fast & Furious sequel. Insurance companies love a driver who treats speed limits like suggestions from an old librarian. If you can stay accident-free for three to five years, your rate will start sliding south.
Think of it like a gym membership for your driving record: the longer you go without skipping leg day (aka crashing), the more rewards you get. I once went three years without a ticket, and my insurer dropped my rate by 15%. It was like they said, “You’re not a total disaster. Here’s a cookie.” But one speeding ticket later, and that cookie was gone — replaced by a bill that made me question my life choices.
Your Car’s Midlife Crisis: When It Gets Old (But Not Too Old)
Here’s a weird truth: the moment you drive your shiny new car off the lot, its value plummets like a lead balloon. That’s actually good news for your wallet. As your car ages, its replacement cost drops, so your comprehensive and collision coverage gets cheaper. Your 2010 Honda Civic isn’t worth fighting over anymore, so insurance treats it like a trusty old dog — it’s still covered, but nobody’s paying for a luxury funeral.
But watch out for the trap: once your car is older than a high school reunion, you might want to drop the collision coverage. I drove a 2003 Toyota Camry that was held together by duct tape and prayers. The insurance company basically said, “If you total this, we’ll give you a bus pass.” So I saved $200 a year by removing collision. It’s like canceling a Netflix subscription — you just forget about it until you need it.
The Married Man’s Discount (AKA: Love Lowers Your Rate)
Getting married might give you a gorgeous partner, but it also gives you a 5% to 15% discount on insurance. Companies think married people drive safer because they have someone at home waiting to nag them about their turn signals. I joke, but it’s real: tying the knot tells insurers you’re more responsible, like you’ll pay your bills before buying a jet ski.
Of course, if you get divorced, the rate might crawl back up. But hey, at least you got a discount out of the honeymoon. “I do” translates to “I pay less.” Not exactly a fairy tale, but your insurance broker will toast to it.
Credit Score Tango: The Invisible Dance
Believe it or not, your credit score heavily influences your car insurance rate. It’s bizarre — like your credit card company calling your insurance agent and saying, “This person pays for coffee on time, so let them drive cheaper.” In most states, a higher credit score means a lower rate because insurers think you’re less likely to file a claim. It’s unfair, but so is the price of avocados these days.
The fix? Pay your bills on time and check your credit report for errors. I once found a mistake that said I owed money to a library in Alaska. I’ve never even been to Alaska. Fixing that dropped my rate by 10%. It’s like finding a ten-dollar bill in an old coat — except the coat is your financial life.

Miles Matter: Drive Less, Pay Less
If you work from home or walk to the grocery store, your insurance should reflect that. Telling your company you drive fewer than 10,000 miles a year is like admitting you only eat one slice of pizza at a party — it makes you look good. Some insurers offer “pay-per-mile” plans. I switched to one after my commute vanished, and my rate went from “ouch” to “eh, fine.”
Just remember: the lower your annual mileage, the less risk you pose. It’s like being a hermit and paying less for car insurance — finally, social anxiety pays off.
The Final Nod: Shop Around Like You’re Hungry
No matter what, the biggest rate drop comes from switching companies every couple of years. Insurers treat loyal customers like bargain-bin leftovers. I once stayed with the same company for five years, and my rate went up 20% despite a clean record. I switched to a competitor, got the same coverage, and saved $400. It felt like breaking up with someone who never bought you dinner.
So, if you want your insurance rates to go down, don’t wait for a magical birthday. Drive safely, marry well, check your credit, and shop around like you’re at a flea market. Your wallet will smile, and you can finally afford that extra avocado toast.