
Wells Fargo Fico Score Vs Discover
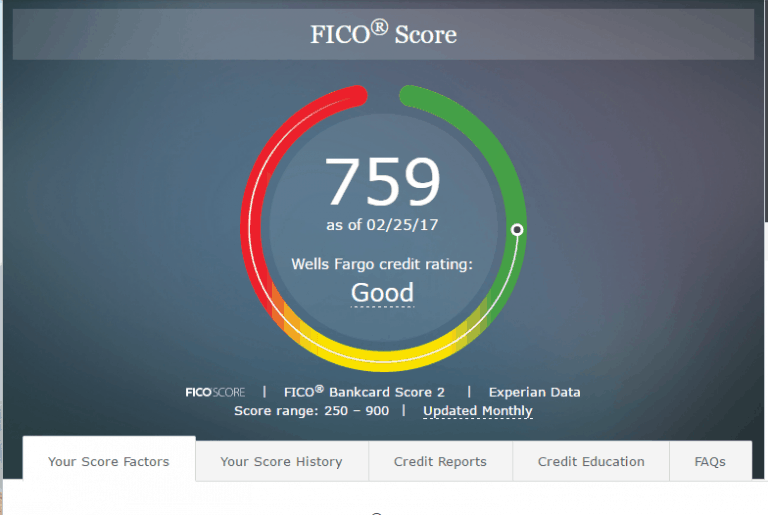
So, you’re trying to figure out your credit score, huh? It’s like trying to decipher ancient hieroglyphics, but with more anxiety and less treasure. Today, we’re pitting two heavyweights against each other: Wells Fargo and Discover. Grab your popcorn (or your credit report, whichever is less stressful).
Let’s be real—most of us just want a number that says, “Hey, you’re a financially responsible adult!” But the game is trickier than that. Both Wells Fargo and Discover offer free FICO scores, but they’re not exactly the same.
The Big Difference: What You Actually Get
Here’s the headline: Wells Fargo shows you your FICO 9 score. Discover shows you your FICO 8 score. Wait, don’t glaze over yet—I promise this is the most fun you’ll have with a math lesson.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Think of FICO versions like movie sequels. FICO 8 is the classic, beloved original (like “The Matrix”). FICO 9 is the slightly upgraded version (like “The Matrix Reloaded”—still good, but some people prefer the first one).
FICO 8 vs. FICO 9: The Nerdy Stuff
FICO 9 is friendlier to people who’ve had medical collections or paid off old debts. It’s like the credit score that gives second chances. FICO 8 is a bit stricter, like that one teacher who wouldn’t let you retake the quiz.
Most lenders check your FICO 8, honestly. So Discover’s score is typically more useful for general planning. But Wells Fargo’s FICO 9 might give you a tiny boost if you’ve been paying off medical bills like a champ.
Wells Fargo: The Bank You Already Have a Love-Hate Relationship With
If you have a Wells Fargo checking account, you’re in luck. You can see your FICO 9 score for free right in their app. It’s updated monthly, and they even include a nifty “Score Change” alert. “Hey, you paid that credit card! Your score went up by 8 points. Go you!”
But here’s the snag: you must have an active Wells Fargo credit card to get the score. Sorry, checking account alone doesn’t cut it. It’s like the bank saying, “We love you, but not that much.”

Discover: The Cool Cousin of Credit Scores
Discover is the party host of free FICO scores. You don’t even need a Discover card to get yours. Just go to their website, sign up for Free Credit Scorecard, and boom—your FICO 8 score appears, no strings attached.
It’s like they’re saying, “Have a score! On the house!” And they also show you your TransUnion credit report details, which is basically the “Director’s Cut” of your financial life. Plus, they update it weekly. Weekly. That’s like checking your phone for likes, but actually productive.
The Little Details That Matter
Wells Fargo’s score pulls from Experian. Discover’s score pulls from TransUnion. These are like different gossip sources—they might have slightly different stories, but the gist is usually the same. If you’re paranoid, check both. Most people find a small difference (5–20 points) between them. Don’t panic; it’s normal.
Also, Wells Fargo’s tool includes a “Score Simulator” that lets you pretend you paid off a loan. It’s like a video game for adults. Discover’s tool focuses on showing you your “risk factors,” which is a polite way of saying, “Here’s why you’re not perfect.”
Which One Should You Use?
If you already have a Wells Fargo card, just use theirs. It’s easy, and you’re already paying them attention (like an ex you still follow on Instagram). If you don’t, go with Discover—it’s free, no card needed, and you get weekly updates.

But here’s the pro tip: use both. Yes, it sounds like a lot, but it’s like having two mirrors to check your outfit. You’ll get a fuller picture of your credit health. And let’s be honest, watching your score go up is better than watching cat videos. (I said what I said.)
One Last Quirk
Wells Fargo’s tool randomly calls your score “FICO Score 9 Bankcard” because it’s specifically for credit cards. Discover’s tool is just “FICO Score 8” for general use. It’s like one is a specialized tool (a sushi knife) and the other is a Swiss Army knife. Both cut, but in different ways.
Conclusion: Your Score, Your Smile
At the end of the day, both Wells Fargo and Discover are trying to help you—which is refreshing, because most things in banking feel like a hidden fee waiting to happen. Whether you choose the bank you already know or the credit card company that throws free scores at you, you’re winning.
So check your score. High-five yourself if it’s good. And if it’s not? Remember: credit scores are just numbers, and numbers lie. (Okay, they don’t lie, but they’re not the whole story.) You are more than a FICO score—you’re a beautiful, slightly confused human who is trying their best. And that’s worth way more than 850 points.
Now go treat yourself to a coffee. You earned it. ☕