
What Happens To My 401k If I Quit
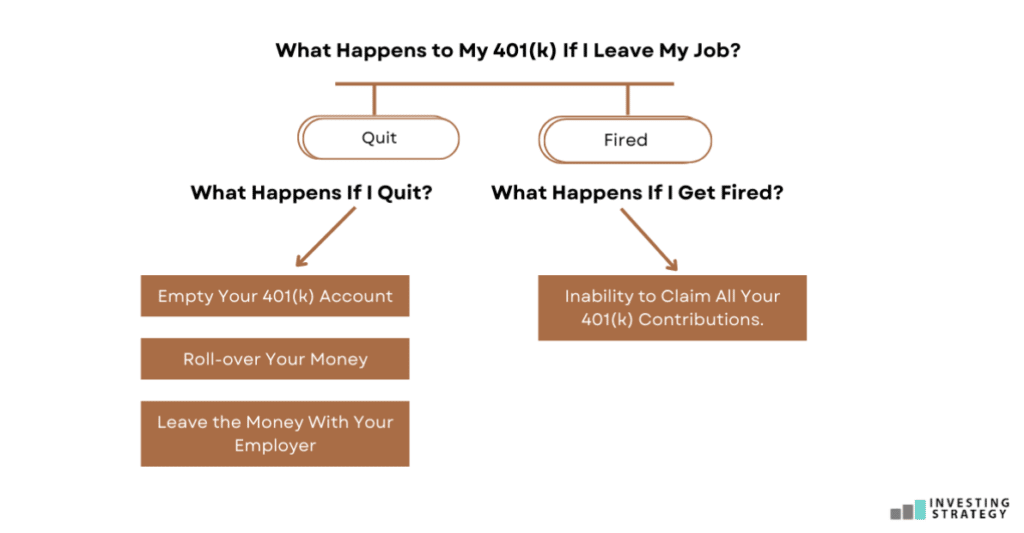
So, you’re thinking about quitting your job. Maybe you’ve had it with the office coffee that tastes like regret, or you’ve finally decided to chase that dream of opening a cat café. Good for you!
But then, a little voice in your head pipes up: “Hey… what about my 401k?” That’s fair. It’s the money you’ve been stashing away for the future, and suddenly it feels like a big question mark.
Let’s take a deep breath. You’re not alone, and the answer is simpler than you think. Imagine your 401k is like a really good backyard shed—it’s full of tools you’ll need later. What happens when you move to a new house?
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
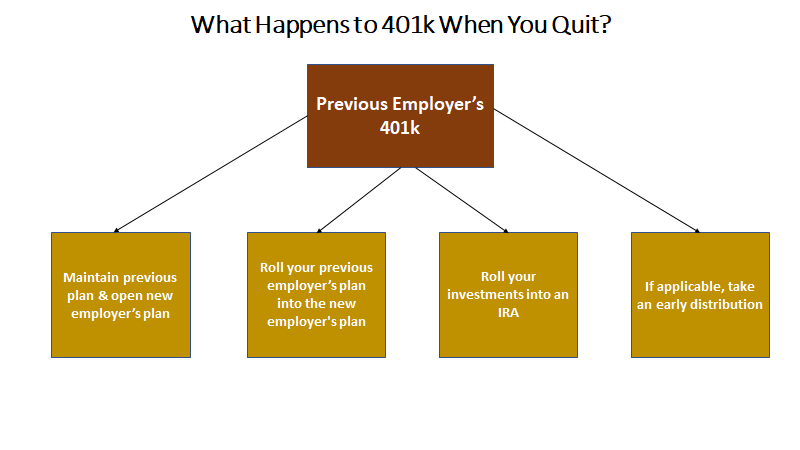
You’ve Got Four Main Options (And None Are Scary)
First up: you can leave it where it is. Yep, just let your old 401k sit in your former employer’s plan. It’s like leaving a favorite book on a shelf at a friend’s house—technically fine, but you might forget about it.
The downside? You can’t add more money to it, and you might get charged extra fees. Plus, you’ll have to remember to log into a separate account for the next thirty years. Not ideal, but it’s safe.
Option Two: Roll It Over into Your New Job’s Plan
This is the smoothest move, like transferring your entire vinyl collection to a new, bigger shelf. You just ask your new employer’s HR to “roll over” the money from your old 401k into their plan.
It’s super common, and it keeps everything in one place. You still get all the tax benefits, and you won’t lose track of that cash. Think of it as giving your retirement money a new home where it can keep growing.
Option Three: Roll It Over into an IRA (Your Own Private Savings Pod)
An IRA is like a personal shoebox for your retirement cash—you control it, not an employer. You open one at a brokerage (like Vanguard, Fidelity, or Schwab) and move your 401k money there.
This gives you tons of freedom to pick your own investments. It’s like going from a cafeteria menu to a buffet where you can grab whatever looks good. Just make sure you do a “direct rollover” so the money moves straight from your old plan to your new IRA.

If you take the money yourself first, even for a day, you’ll get hit with taxes and a penalty. Ouch. Don’t be that person.
Option Four: Cash It Out (Please, Don’t Do This)
This is the “I’ll just grab the cash and run” option. It’s tempting, especially if you need money for a new car or a big move. But here’s the kicker: the government will take a huge bite.
You’ll pay income tax on the full amount, plus a 10% early withdrawal penalty if you’re under 59½. Imagine pulling a $10,000 wad from your pocket, only to have $2,500 of it yanked away by Uncle Sam. That’s not a good feeling.
A friend of mine did this when he quit to travel. He ended up with a fraction of what he expected, and he still regrets it five years later. Don’t be that friend.
But Wait—What About My Employer’s Match?
Great question. If you haven’t worked there long enough, you might not keep the “match” portion. This is called vesting. Think of it like a gym membership—you only own the free protein bars after you’ve been a member for a certain number of months.
Check your plan’s vesting schedule. If you’re only 50% vested, you only keep half of what your boss put in. The rest goes back to the company. It’s a bummer, but it’s not your money yet. No need to panic—just know it’s part of the game.
Why Should You Even Care? (The Fun Part)
Here’s why this matters: your 401k is like a magic bean. If you plant it right (by rolling it over), it grows into a beanstalk that leads to a comfortable retirement. You could be sipping margaritas on a beach someday, thanks to that little bean.
If you ignore it or cash it out, you’re basically stepping on the bean. Suddenly, that beach trip turns into a bus ride to the grocery store at 70. Not the vibe you want, right?
Think of it this way: quitting your job is like packing up from a dorm room. You wouldn’t just leave your laptop and textbooks behind because you’re excited to move. Your 401k is your future laptop.
So, What Should You Actually Do?
First, don’t rush. You usually have 60 days after quitting to make a move without penalties. That’s two whole months to grab a coffee, call a financial advisor, or just google “IRA rollover” while wearing pajamas.
Second, decide if you like your current plan or want more freedom. If you’re happy with your old 401k’s options, leave it. If you want to design your own adventure, roll it into an IRA. Simple.
Finally, tell someone. Yell it to your partner, your mom, or your cat. Saying it out loud makes it real. “I’m rolling over my 401k to my new job next week!” Feels good, doesn’t it?
Because at the end of the day, this is your money for your future. Whether you’re leaving for a better job, a sabbatical, or just to escape that guy who microwaves fish in the break room, your 401k should come with you. Treat it like a loyal dog—don’t leave it tied up in the park.
Now go forth, quit that job, and take your retirement cash with you. Your future self—the one in hammock on a sunny beach—will thank you.