
Does Homeowners Insurance Cover Flooding
So, you’re chilling at home, maybe scrolling through your phone, when a freak rainstorm decides to turn your basement into a kiddie pool. Your mind races: “Does my homeowners insurance cover this?” The short, slightly frustrating answer is… probably not. It’s one of those surprising little secrets of home ownership that feels like finding out your favorite pizza place doesn’t deliver to your street.
The Great Divide: Water vs. Flood
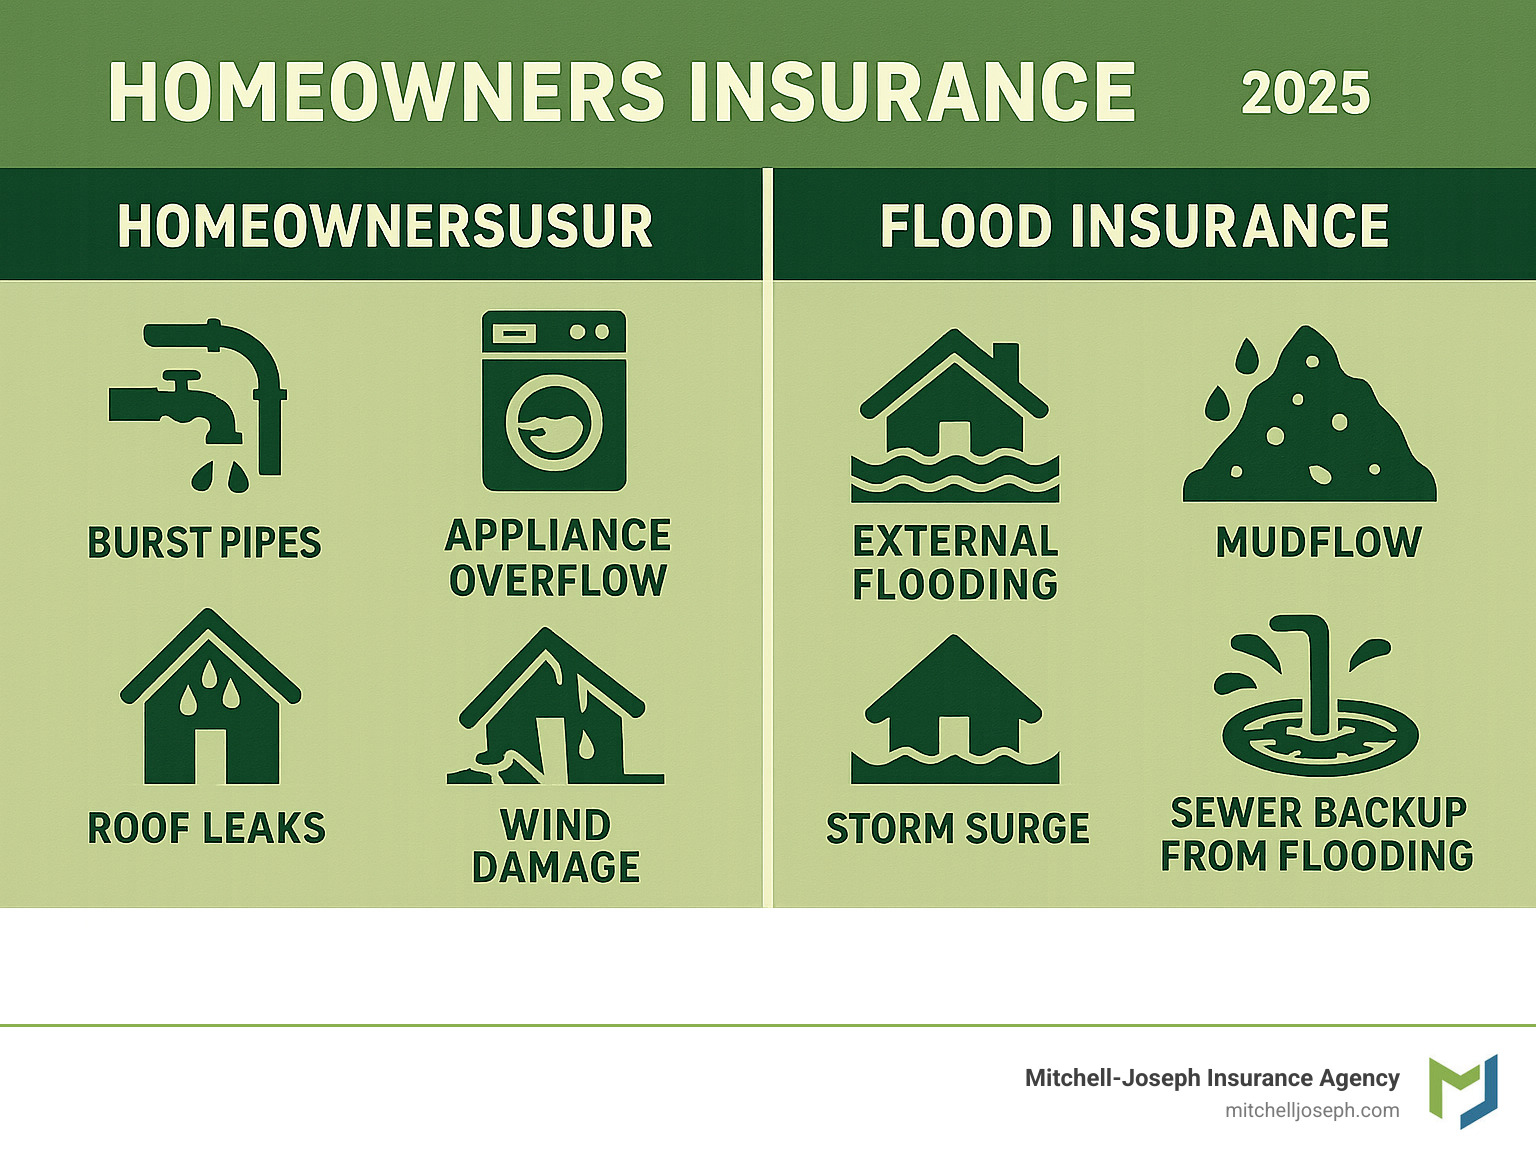
Here’s the core twist: standard homeowners insurance is a bit like a picky eater. It loves covering sudden, unexpected water damage, like a burst pipe or a leaky roof from a windstorm. That’s totally on the menu.
But flooding from outside—like a raging river, a storm surge, or relentless rain that seeps through your foundation—that’s a different creature entirely. Most standard policies treat this like uninvited guest who broke the door down and refuses to pay for repairs.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Think of it this way: your insurance is happy to clean up a spilled soda inside the house. But if the whole soda factory exploded next door and flooded your block? That’s a whole different policy—often called flood insurance—and you have to buy it separately.
Why Is Flooding Treated Like the Black Sheep?
It’s not because insurance companies are mean. It’s because flooding is weirdly common and catastrophic. The risk is so high and so widespread that regular home insurers would go broke trying to cover everyone. So, they politely say, “Nope, that’s a special club.”
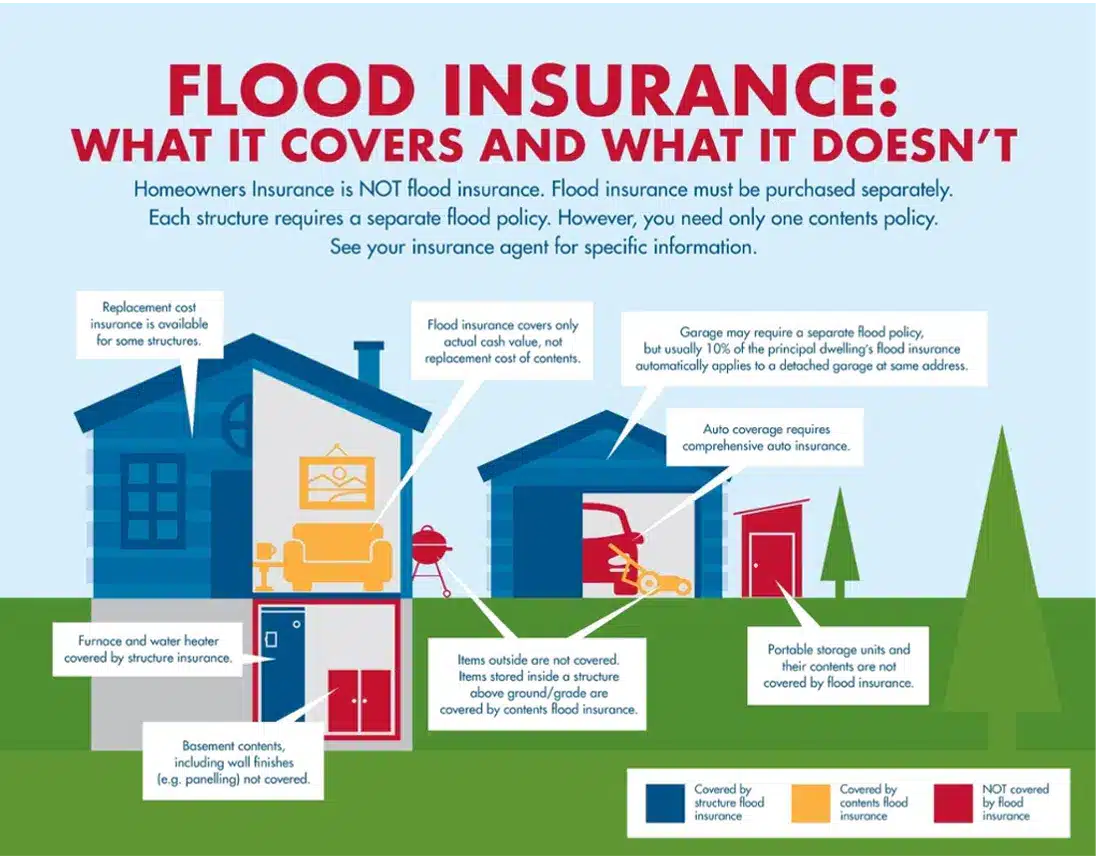
This is where the National Flood Insurance Program (NFIP) steps in, like a government-sponsored safety net. It’s basically a federally backed plan that lets you buy flood coverage, usually through the same agent who sells your home insurance. Kind of like ordering a burger and being told the fries are extra—but those fries could save your whole meal.
Interesting, right? It’s not a secret plot; it’s just that water from the ground up is treated differently than water from the roof down. One is a plumbing party foul, the other is a neighborhood-wide event.
When Does Regular Insurance Actually Cover Flooding? (Plot Twist!)
Okay, don’t lose hope. There are sneaky scenarios where standard coverage does help. Picture this: a tree crashes through your roof during a storm, and rain pours in. That’s wind damage first, then water damage—and your policy likely covers it. The water is a secondary problem, like a spilled drink after someone knocked over the table.
Another example: a water heater or washing machine suddenly explodes. Even if it floods your laundry room floor, that’s considered a sudden, internal event. Your insurance nods and says, “We got this.”
But if that same water heater flood is because a river overflowed its banks and seeped through your basement walls? Nope. Regular insurance waves goodbye. The difference is all about where the water came from—your pipes or Mother Nature’s tantrum.
What’s the Big Deal? Why Should You Care?
Here’s the cool part: this little distinction is actually kinda fascinating. It shows how insurance is designed to handle random, individual accidents (your broken pipe) but not systemic, community-wide disasters (a flooded neighborhood). It’s like how car insurance covers you hitting a deer, but not a meteor striking your whole city block.
Also, did you know that 25% of flood claims come from homes outside high-risk flood zones? Seriously. You might live on a hill, thinking you’re safe, then a flash flood decides your driveway is a creek. It’s a wake-up call, but a chill one—just something to be curious about.
So, what’s the takeaway? Don’t assume your homeowners insurance is a magical force field. It’s more like a loyal bodyguard for specific crises, but for floods, you need a separate specialist. It’s not boring bureaucracy—it’s a clever puzzle about risk, and you just solved the first piece.
Final Vibes: A Quick Checklist
If you’re feeling curious (and maybe a little nervous), start by checking your policy. Look for the phrase “surface water” or “flood”—if you see them under “exclusions,” you’re not covered. Then, call your insurance agent and simply ask: “Hey, what’s the deal with flood coverage?”
It’s a friendly chat, not a scary interrogation. And honestly, knowing this stuff makes you feel like a mini expert—like you just unlocked a secret level in the game of adulting. Stay dry, stay curious, and remember: insurance is weirdly poetic when you realize it’s all about where water decides to dance.