
What Credit Score Is Needed To Buy A Rv
So, you’ve got the dream. Rolling down the highway, coffee in hand, with a tiny home on wheels that doubles as a “gasoline-powered reality escape.” You want an RV. But before you start picking out throw pillows, let’s talk about the not-so-glamorous part: your credit score. Don’t worry, I’m not here to judge you for that one time you forgot a utility bill. I’m here to help you figure out if your credit is ready for the open road.
The Magic Number (Spoiler: It’s Not 850)
First, the good news: you don't need a perfect credit score to buy an RV. Lenders are surprisingly flexible here. While a home loan might demand a pristine 760, RV lenders are often more like a friend who’s okay with you being a little late for dinner—as long as you bring a good bottle of wine.
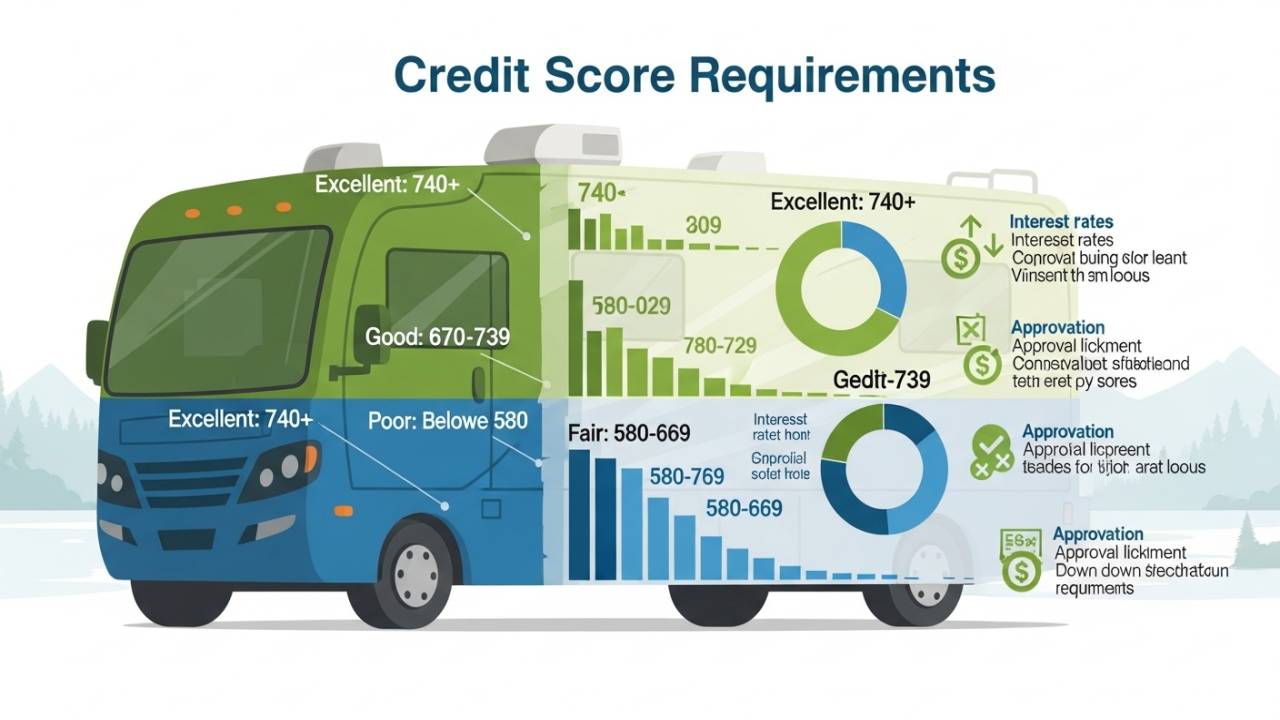
Generally, you’ll want a score of 660 or higher to get the best interest rates. Think of this as the “golden ticket” zone. If you’re in this range, lenders will essentially throw money at you and ask if you want a toaster with your loan.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
But here’s the kicker: you can still buy one with a score as low as 580. Yes, really. It won't be pretty, and your interest rate might be higher than a giraffe’s neck, but it’s possible. You just might be paying for that “Freedom Mobile” longer than you planned.
What About the “Bad Credit” Club?
If your score is below 580, don’t panic. You’re not doomed to a life of tent camping. You just need to make peace with a few things. First, expect a higher down payment. Think 20% or more. Lenders want to see that you’re serious, and cash talks louder than a blinker in a turn lane.
Second, get ready for a higher interest rate. We’re talking double digits sometimes. It’s not ideal, but hey, you’re still rolling. Pro tip: If you have a co-signer with great credit, you can instantly jump from “Budget Camper” to “Luxury Liner” without the financial hangover.
The Down Payment Dance
Let’s talk about the elephant in the room—or rather, the elephant-sized vehicle in the driveway. The down payment is your best friend when your credit is “meh.” If you can put down 10% to 20%, you instantly look more responsible than a golden retriever at a tennis ball factory.
Why? Because if you flake on payments, the bank can repossess your RV and sell it. A big down payment means they don’t have to worry about losing money. It’s like you’re saying, “I’m serious, please don’t repo my dream.” And the lender nods, respectfully.
And if you’re buying a used RV? Even better. The loan amount is smaller, so the bank relaxes a little. A used RV is like a “starter home” for your wanderlust—less pressure, more fun.
The “New vs. Used” Credit Trap
Here’s a little secret: new RVs depreciate faster than a banana in the sun. Lenders know this, so they might be stricter with your credit score for a shiny, $100,000 motorhome. If your score is average, they might say, “Sorry, we only approve new RVs for people who alphabetize their spice rack.”
But a used RV? That’s a different story. Lenders are more lenient because the loan is smaller. You could get approved with a score of 600 if you’re buying a gently-used camper. Plus, you won’t cry as hard when you scratch the side against a tree at your first campground. Life lesson learned.
The “Secret” Ingredients Lenders Actually Care About
Credit score is important, but it’s not the only thing. Lenders also want to see that you have a steady job. If you’ve been at the same gig for two years, they love you. If you’re a freelancer who lives off “vibes and PayPal,” they might want to see bank statements. Annoying, but fair.
They also look at your debt-to-income ratio. This is just a fancy term for “how much of your paycheck is already promised to other people.” Ideally, your total debt payments (including the new RV loan) should be under 43% of your income. If it’s higher, lenders start sweating—and so will you when you see the interest rate.
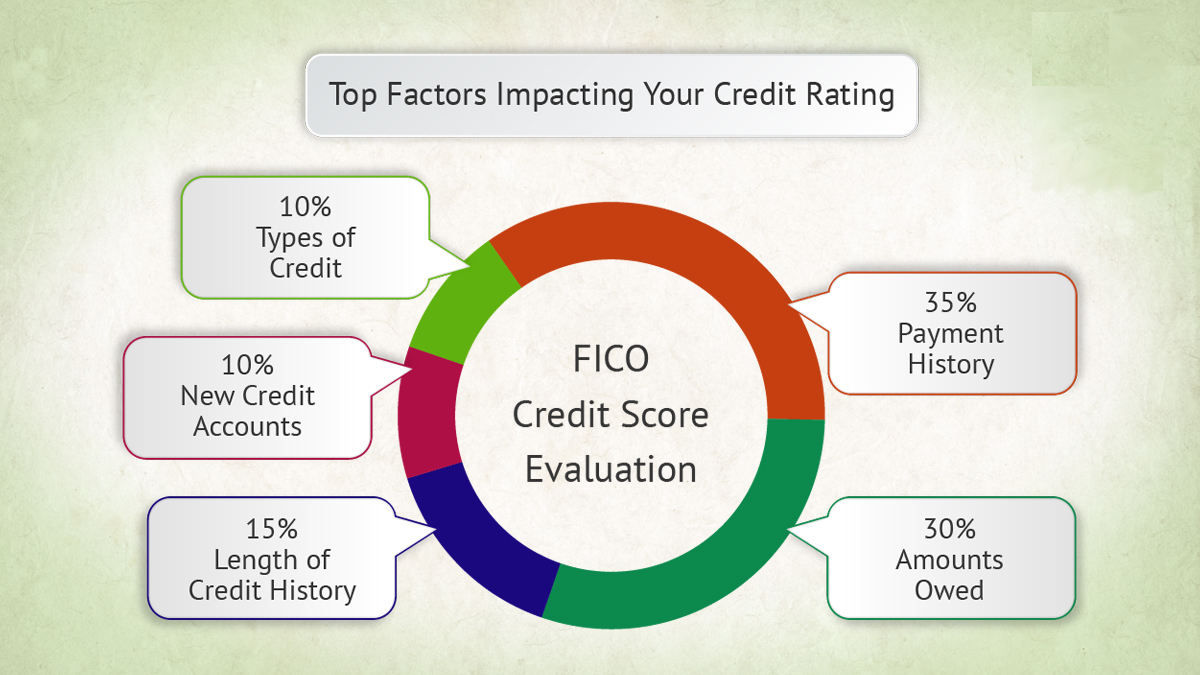
And finally, your payment history on other loans matters. Missed car payments? They’ll assume you’ll miss RV payments. Paid everything on time? You’re gold, baby. Moral of the story: Pay your bills, even the annoying ones.
A Quick Reality Check (With a Punchline)
I once met a guy who bought a $50,000 RV with a credit score of 620. How? He put down $15,000 cash and signed with a credit union that specialized in “adventure loans.” He now lives part-time in a forest, fixing his own plumbing. Legendary.
So don’t let a number define you. If your score is low, you have options: save a bigger down payment, find a co-signer, or shop at a smaller dealership that works with “non-prime” lenders. It’s not the fastest route, but it’s still a route. And routes lead to campfires.
The Uplifting Conclusion (You Made It!)
Buying an RV isn’t about having a perfect credit score. It’s about having a perfect mindset. You are trading four walls for four tires. You are swapping a boring backyard for endless horizons. And you are doing it because you deserve to park your home in places where the view is better than your TV.
So whether your score is 780 or 580, remember this: credit is just a tool, not a verdict. You can fix it, you can negotiate, and you can absolutely make the dream happen. And even if you have to wait a year to improve your score, that’s okay. The mountains aren’t going anywhere. The ocean will still be there. And when you finally pull into that campsite, you’ll smile, crack open a soda, and say, “I earned this.”
Now go check your score. Then go look at RVs. Adventure is calling, and it’s totally okay if you answer on credit. 🚐💨