
When Will My Car Insurance Go Down
You’re paying your car insurance bill, scrolling past that number, and wondering: When will this thing finally drop? It’s a universal question, like asking why avocados ripen at the exact moment you forget about them. Let’s break it down with a calm, modern attitude—no jargon, just real talk.
The Myth of the Magic Age
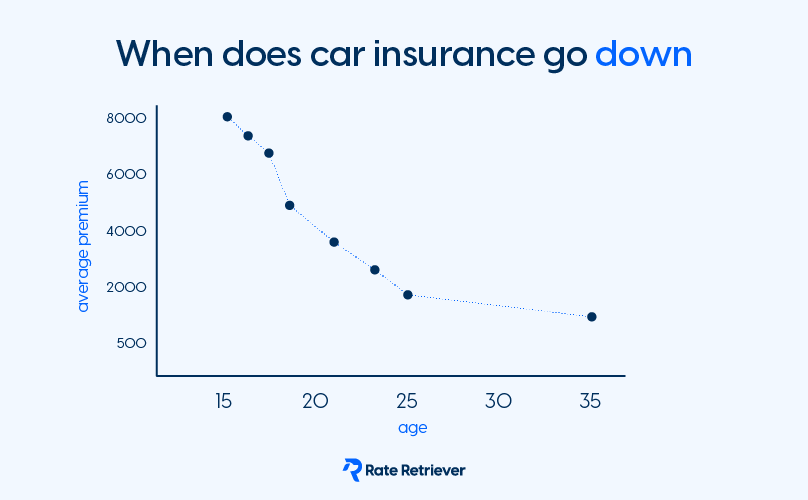
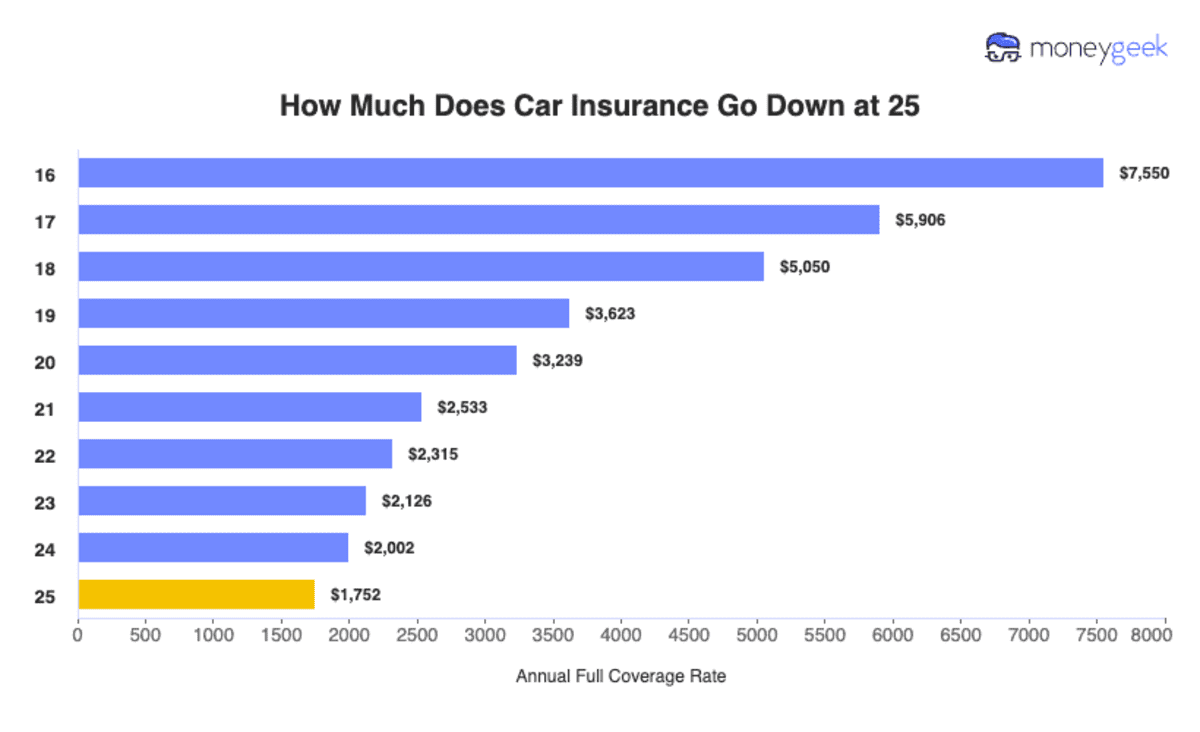
Everyone says your rate nosedives at 25. It’s true—but not because you suddenly become a zen master behind the wheel. Insurers see 25 as a statistical sweet spot where risk-taking behavior naturally calms down. Think of it as your prefrontal cortex finally sending its RSVP to the party.
But here’s the twist: if you have a clean record, your rate might start dropping as early as age 21. The real drop isn’t a birthday gift; it’s a reward for consistent good driving. So don’t wait for a candle count—focus on the road ahead.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Fun fact: In the UK, rates can plateau by 30, while in the U.S., the biggest dip often hits between 25 and 30. It’s like the insurance industry has its own time zone.
The Three-Year Rule You Didn’t Know
Most insurers use a three-year window to decide if you’re a liability. That means an accident or ticket today could haunt your premium until year three. But if you’ve been incident-free for 36 months, insurers start seeing you as a safer bet.
So, picture this: you got a speeding ticket in 2021—annoying, yes. By 2024, that little bruise fades into the rearview mirror. Patience is your co-pilot here. Keep your eyes on the road, and time does the heavy lifting.
Practical tip: Log into your insurance app and check your “violation history” right now. You might find a surprise—like a discount you forgot existed.
Lifestyle Hacks for Faster Rate Drops
Your car insurance premium isn’t a fixed fate; it’s a relationship. And like any good relationship, it rewards good behavior. Start by bundling your renters or homeowners insurance with your auto policy—that’s an instant 10–15% discount, no negotiation needed.
Then, consider a telematics device or a phone app that tracks your driving. Yes, it feels like having a backseat driver, but if you brake smoothly and avoid midnight joyrides, you could see a 20% cut in six months. It’s like a Fitbit for your car, minus the guilt.
Cultural reference: Remember that scene in “Ferris Bueller’s Day Off” where he fakes a mileage log? Don’t do that. Instead, drive less—many insurers now offer low-mileage discounts. If you work from home, you’re basically a gold mine for savings.
Credit Score: The Secret Ingredient
In most states, your credit score whispers to insurers about your reliability. A higher score often equals a lower premium—by as much as 30% in some cases. It’s not fair, but it’s a fact. Think of it as the fine print of adulthood.
Fun fact: The correlation is strong enough that insurance companies call it an “insurance score.” It’s like your GPA for financial trust. So, paying off that credit card isn’t just good for your wallet—it’s a direct line to cheaper coverage.
Practical tip: Check your credit score for free online. If it’s below 700, focus on lowering credit utilization before your renewal date. Small steps, big savings.
The Annual ‘Shopping Tango’
Here’s the thing: loyalty doesn’t always pay. Many insurers charge more to renew than to recruit new customers. So every 12 months, do a comparison shop like you’re hunting for concert tickets.
Get quotes from at least three different carriers. You don’t have to switch—just showing you have options can motivate your current company to lower your rate. It’s the dating app of insurance: stay fresh, stay open.
Cultural reference: It’s like that scene in “The Office” where Dwight negotiates his own salary by getting a fake offer from another company. Channel that energy, but with less beet-farming and more strategic savviness.

The Wild Card: Life Events
Getting married? Moving to a quieter suburb? Retiring a classic car from daily use? These can all trigger a rate drop. Insurers love stability, and marriage signals you’re less likely to do donuts in a parking lot at 2 a.m.
Also, if you’re no longer commuting to a busy downtown, update your mileage estimate. That 10-mile highway slog to work costs more than you think. Tell your insurer the truth—it might save you a latte a month.
Fun fact: In Japan, some insurers even offer discounts for cars with dashcams. It’s like having a witness who always sides with you. The tech trend is catching on globally.
When Will It Actually Happen?
So, the honest answer: Your car insurance will start to go down in three to six months following any major life change or clean-record milestone. If you just turned 25, wait three months after your birthday for the system to update. If you removed an accident from your record, mark your calendar for the month after it falls off.
But the bigger truth? It goes down when you actively manage it. Insurance is passive unless you nudge it. Set a calendar reminder for your renewal date, and treat it like a mini holiday. You’ll get a gift—a lower bill.
Practical tip: Use an app like Root or Progressive’s Snapshot for a trial period. Some people see a drop in just six weeks of gentle driving. Who knew being boring could be so lucrative?
At the end of the day, your car insurance is a mirror of your life’s rhythm. It drops when you slow down, when you stay steady, when you choose consistency over chaos. So breathe, drive kind, and let time and a few smart clicks do the work. Your future self—and your bank account—will thank you.