
When Does Insurance Get Cheaper
Let’s be real: insurance is that awkward friend who shows up uninvited, eats your snacks, and then asks for money. We all know we need it, but paying for it feels like throwing cash into a bonfire every month. The big question everyone whispers about at dinner parties is: when does this thing finally get cheaper?
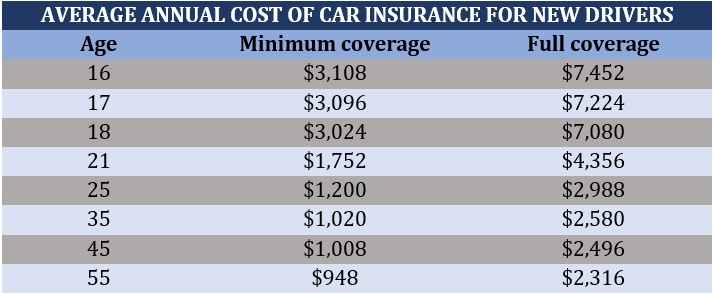
First, think about your age. When you’re twenty-five and invincible, insurance companies see you as a liability—a walking accident with a pizza stain. But around age thirty, something magical happens. You stop pulling all-nighters, your car stays in the driveway, and insurers suddenly think you’re a responsible human being. Your rates drop like a bad habit.
That sweet spot usually hits between your mid-thirties and early forties. By then, you’ve probably got a mortgage, a minivan, and a boring job. Boring is good for insurance. They love boring. It means you’ll probably spend Friday nights watching Netflix instead of skydiving.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The Driver’s License Retirement Plan
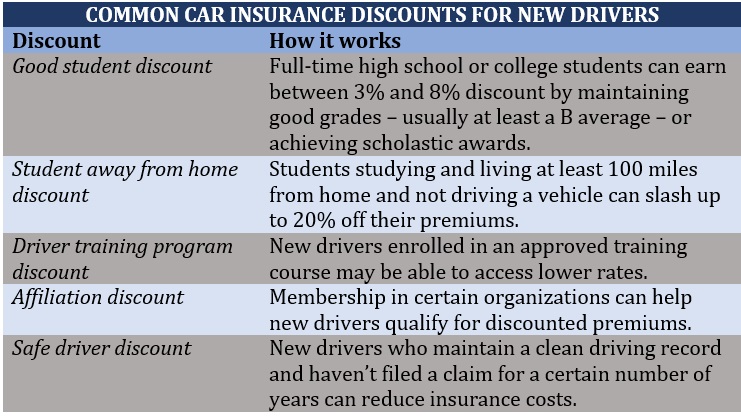
Your driving record is the real party trick. Get a speeding ticket at twenty-two, and your premium balloons like a hot air balloon with a leak. But if you go three years without a fender bender, the universe rewards you. Insurers actually pat you on the back with a discount.
I remember my own “clean driving” anniversary. I expected a parade, but instead got an email saying my car insurance dropped by eighteen bucks. I celebrated with a fancy coffee. Baby steps.
If you hit five years without a claim, you’re basically a saint in the insurance world. They’ll lower your rates just to keep you around. It’s like the company version of “please don’t leave us.”
The Homeowner’s Secret Handshake
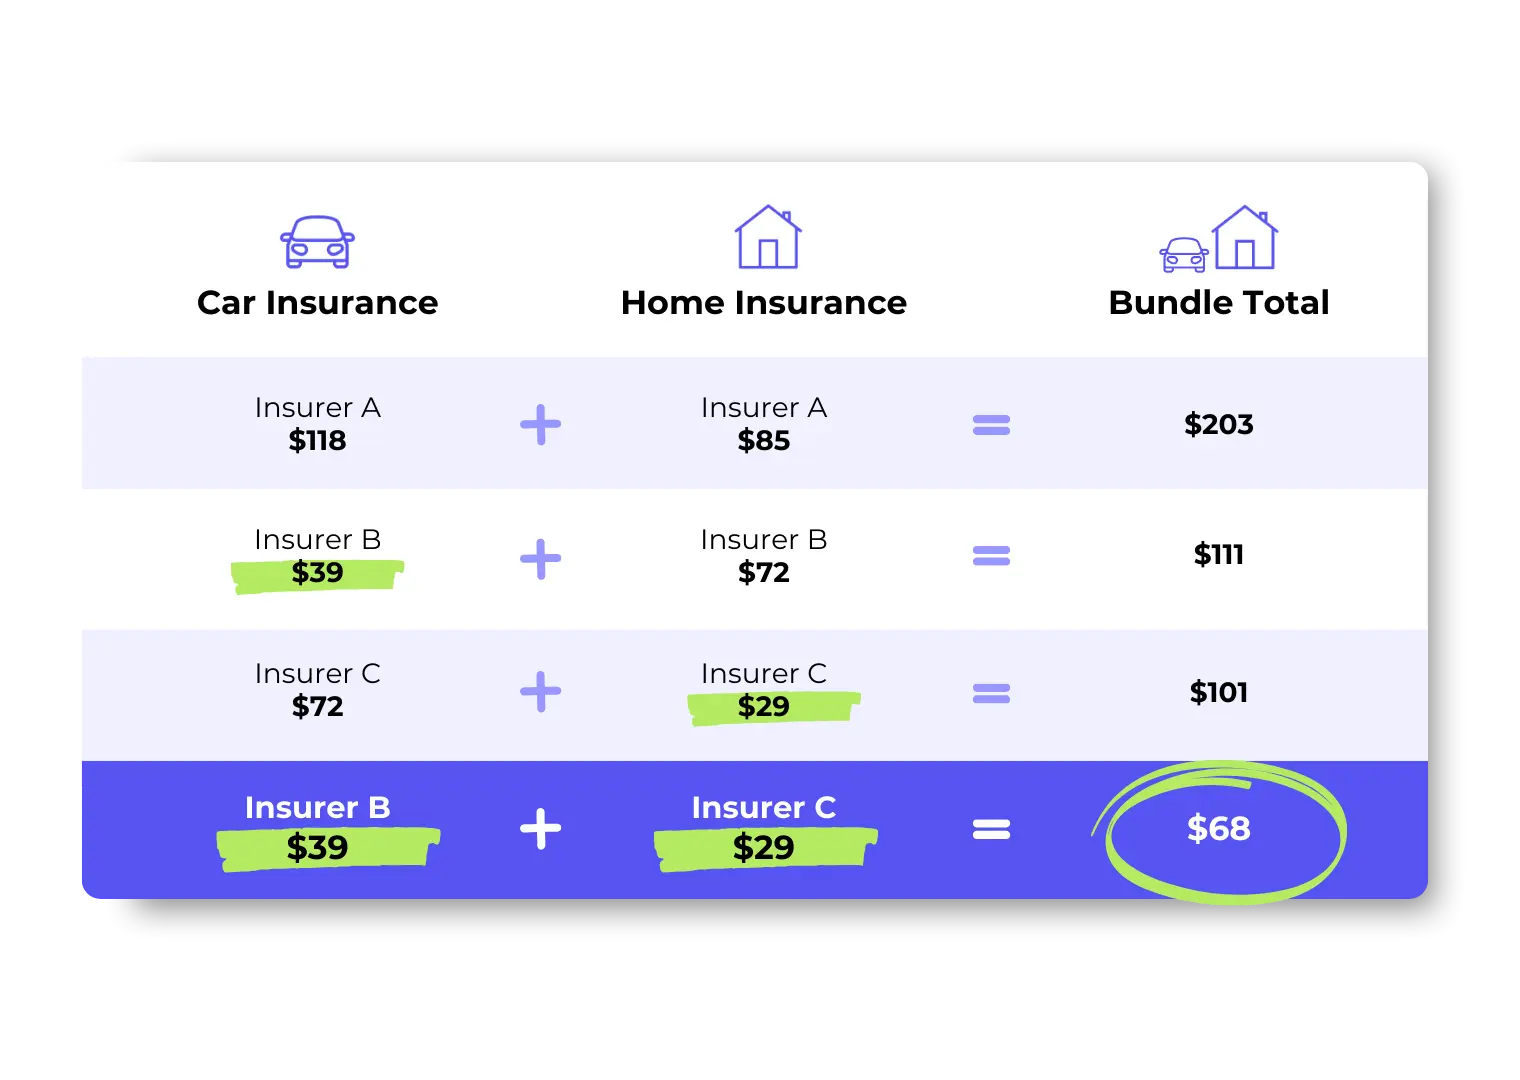
Buying a house is the single most boring purchase you’ll ever make for insurance purposes. Suddenly, bundling your car and home insurance feels like a power move that saves you hundreds a year. I bundled my policies last spring, and my agent called it a “marriage of savings.” I called it not having to eat ramen every Tuesday.
Here’s the funny part: your credit score plays a huge role, too. Apparently, paying your cell phone bill on time proves you won’t drive into a ditch. It’s weird logic, but it works. Improve your credit by fifty points, and your insurance might drop faster than your high school GPA.
The Great Marriage Discount
Getting married is romantic, but the real love story is the multi-policy discount. When you and your spouse combine car and renters insurance, it’s like the insurance gods smile down on you. I’m not joking—my wife and I saved enough for a weekend getaway. We called it our “honeymoon fund 2.0.”
If you stay married for five years without a divorce, your rates drop even more. Insurers think stability equals safety. They don’t care about your arguments over whose turn it is to take out the trash. They just love that you stick together.
The Middle-Aged Milestone
Here’s the biggest plot twist: turn fifty, and life insurance gets oddly affordable. That’s because you’ve survived the “danger years” of your twenties and thirties. You’re not as fun, but you’re alive, which is the main requirement.
Auto insurance follows a similar pattern. Once you hit fifty-five, many companies offer a “senior discount.” You’ve been driving longer than some of their employees have been alive. They trust you not to text and drive, even if you can’t read the dashboard without reading glasses.
The Elephant in the Room: Your Teen Driver
If you have a teenager, forget everything I just said. Your rates will skyrocket faster than a rocket launch. But here’s the good news: once that kid turns twenty-one and moves out, your premium breathes a sigh of relief. It’s like the final payment on a really expensive favor.
When my cousin’s son finally got his own insurance, my cousin called me screaming with joy. It wasn’t about the empty nest—it was about the $200 monthly savings. He bought a grill to celebrate.
The Sneaky Little Details
Sometimes insurance gets cheaper for weird reasons. For example, if you drive less than 7,500 miles a year (thanks, WFH life), you qualify for low-mileage discounts. It’s like being paid to be a homebody.
Also, if you drop collision coverage on an old car, you’ll save a chunk. Let’s be honest: your 2005 sedan with duct-taped bumper isn’t worth fixing anyway. Paying for full coverage on it is like buying a designer scarf for a goldfish.
So, When Does It Actually Get Cheaper?
The short answer: when you stop being a risk in their eyes. That usually happens around age thirty, after a clean driving streak, after buying a house, or after your kids move out. It’s a slow burn, like watching paint dry—but eventually, the wallet sighs in relief.
Until then, shop around. Get quotes every year or two. Insurers are like jealous lovers—they lower prices when they think you’re leaving them. I switch companies every few years, and I swear my current one sends me thank-you notes.
Remember, insurance isn’t a punishment. It’s a safety net that gets cheaper the more boring your life becomes. Embrace the boredom. It pays for your Netflix subscription. And that, my friend, is the real American dream.