
Will Car Insurance Ever Go Down
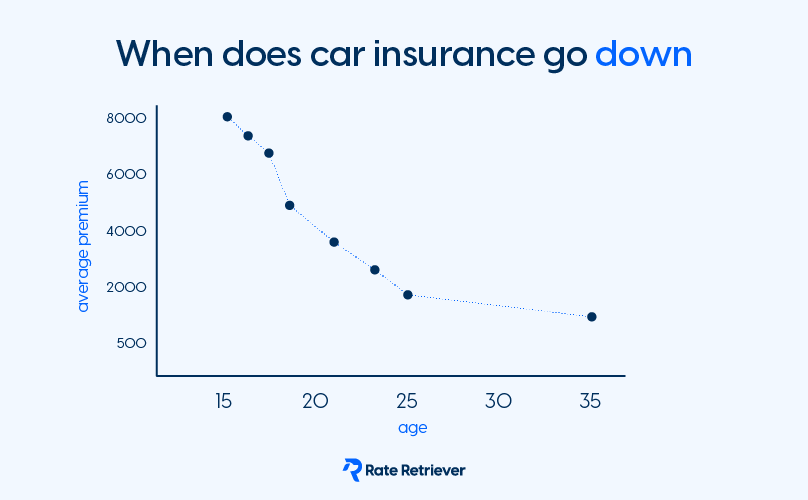
We’ve all been there. You open your car insurance renewal email, take a sip of coffee, and immediately choke. The number has gone up. Again.
It feels like a sneaky little tax on just owning a car, doesn’t it? You haven’t had a ticket in years, you drive like a careful grandma, and yet your premium still climbs higher than a squirrel up a tree.
So, the big question hanging over every driveway is this: will car insurance ever actually go down?
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The Short Answer: It’s Complicated (Like Your Family Reunion)
Let’s be real. Car insurance isn’t a subscription you can haggle down just by asking nicely. It’s a giant pool of money that pays for smashed bumpers, dented fenders, and the occasional rogue deer.
Right now, that pool is getting drained fast. Repair costs are through the roof because modern cars are basically computers on wheels. A new headlight can cost what your first used car did.
Plus, everyone seems to be driving a little more aggressively lately. Remember that guy who cut you off in the grocery store parking lot? He’s raising rates for all of us.
The Grim Truth About “New Normal” Prices
After the pandemic, we saw a huge spike. Parts were stuck on cargo ships, used cars cost a fortune, and insurance companies panicked. They hiked rates to cover their losses.
Now, inflation is the uninvited guest that won’t leave. Body shops charge more for labor, car rentals cost double, and even a simple fender bender can turn into a five-figure claim.
This means a “drop” back to 2019 prices is about as likely as finding a gas station with $2-a-gallon gas. It’s a nice dream, but don’t hold your breath.
But Wait—Here’s the Good News (Sort Of)
If you’re hoping for a universal, across-the-board price cut, I’ve got bad news. That’s not happening. But your personal rate? That’s a different story.
Insurance is like a high school popularity contest—it’s all about you. If you stop being risky, the companies might just smile at you again.
Think of it this way: if you were a speeding ticket magnet last year, your rate is a penalty for that bad behavior. Clean driving for a year? That’s your hall pass to lower prices.
Small Wins That Feel Like a Pay Raise
Here’s a little secret: you can force your insurance to go down, even if the market is stubborn. Shop around like you’re hunting for the best avocado at the store.
I once called my old insurer just to ask, “Hey, can you match this lower quote I got?” They said no. So I switched. My new rate was $400 less per year. That’s a fancy dinner out every month!
Also, check your mileage. If you’re working from home and your car mostly sits in the driveway, you might be overpaying for “commuter” coverage. Tell them you’re a weekend warrior, not a road warrior.
The Tech Factor: Are We Getting a Break?
There’s a shiny hope on the horizon: telematics. That’s the fancy word for letting a little app or gadget watch your driving habits.
If you’re the type who brakes softly, never texts at red lights, and drives the speed limit, these programs can save you a bundle. It’s like having a perfect attendance record in school.

On the flip side, safety tech in new cars (like automatic braking) is making crashes less frequent. Fewer crashes means fewer claims. Eventually, that should help prices level out.
But Don’t Hold Out for a Miracle
Will car insurance ever go down to where it was? Probably not. But will it stop climbing and maybe even take a little dip for you personally? Absolutely yes, if you play your cards right.
Imagine your insurance as a grumpy old neighbor. You can’t change the whole neighborhood, but you can mow your lawn, keep your dog quiet, and earn his respect.
That’s how you get the “neighborly” rate. Bundle your home and auto. Take a defensive driving course. Ask about low-mileage discounts.
Why You Should Care (With a Smile)
Let’s be honest: nobody loves thinking about car insurance. It’s about as fun as doing taxes or cleaning out the garage. But it’s money you’re throwing out the window every month.
A $50 drop a month is $600 a year. That’s a weekend getaway. That’s a new set of tires. That’s a whole lot of tacos from your favorite spot.
So, will car insurance ever go down? The market says “maybe slowly.” But your car insurance? That’s in your hands. Be a good driver, be a smart shopper, and don’t be afraid to switch lanes.
Because the only thing worse than a high premium is paying it without asking, “Is there a better deal out there?”