
Rv Financing Credit Score
Let’s be honest: dreaming about an RV is easy. You picture yourself sipping coffee in a national park, wearing novelty socks, and pretending you’re a rugged explorer. It’s the reality of financing that hits like a pothole on a dirt road.
Nobody wakes up excited to talk about credit scores. It’s like planning a root canal, but with more paperwork. Yet, here we are—because that three-digit number is the gatekeeper to your rolling castle.
The Credit Score Circus
Your credit score is basically a report card for your adulting skills. Remember that time you forgot to pay a library fine? The credit bureaus remember. They’re like that nosy neighbor who logs every time you bring takeout home.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
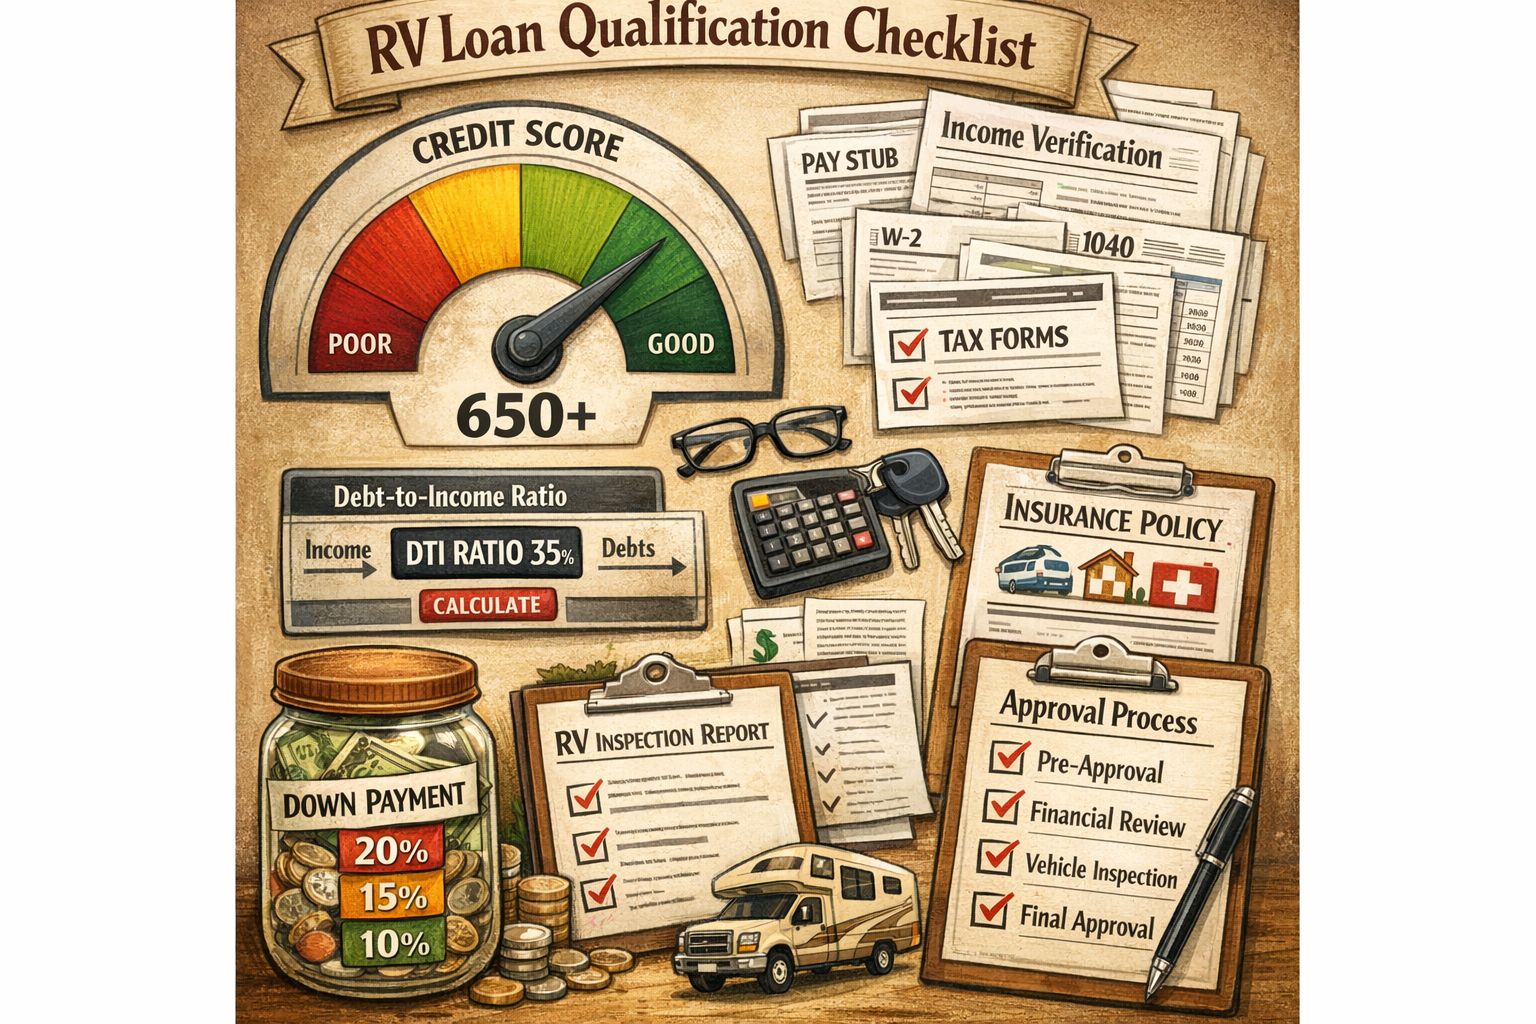
When you walk into an RV dealership, your score either gets you a parade or a pity party. A good credit score (think 740 and above) makes you feel like a financial rockstar. A low one? You’ll get interest rates that feel like you’re borrowing money from a loan shark named “Vinnie the Calculator.”
I once met a guy who tried to finance a used RV with a score of 580. The dealer offered him a 23% APR. That’s not a loan; that’s a financial hostage situation.
The Cash Flow Reality
Here’s the thing: RV lenders don’t care if you have a dream. They care if you have income and a history of paying bills. It’s like trying to borrow your buddy’s lawnmower only if you promise to return it with gas still in it.
Your debt-to-income ratio is just as important. If you already spend half your paycheck on avocado toast and subscriptions you forgot about, the lender will sidestep you like a puddle. They want to see that your RV payment won’t make you eat ramen for a decade.
And let’s not pretend you’ll rent out the RV on weekends to cover costs. That’s like saying you’ll buy a treadmill and use it as a clothes hanger—we all know how that ends.
Improving Your Score Without Losing Your Sanity
So you’ve got a score that’s “mediocre” at best. Don’t panic. You can fix it, but it takes time—like growing a beard or waiting for a slow Wi-Fi signal.
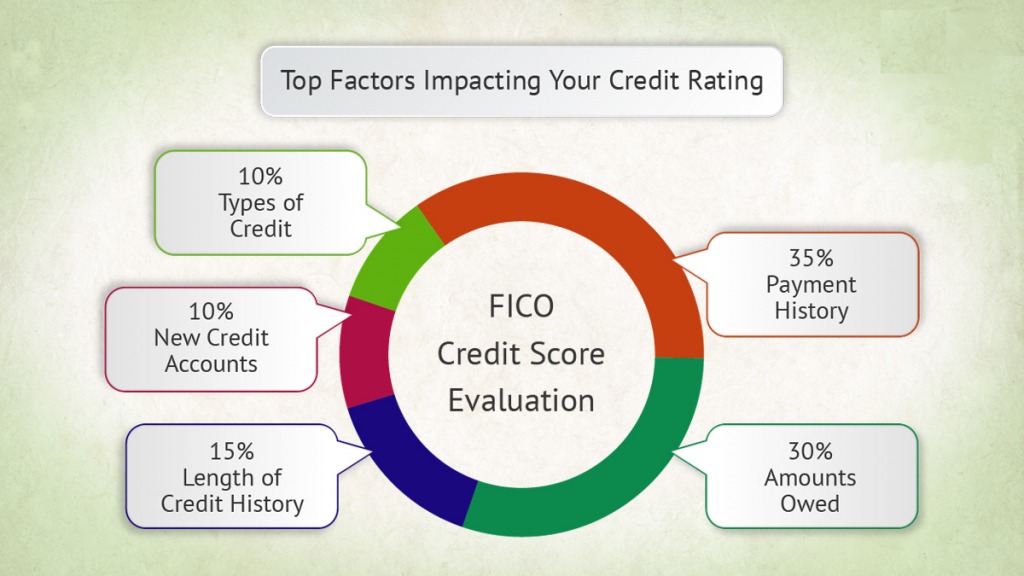
Start by paying your bills on time. That’s the golden rule. One late payment on your credit card is like showing up to a job interview in your pajamas. It’s a red flag, even if you’re qualified.
Also, don’t max out your credit cards. Lenders like to see you use about 30% of your available credit. If you’re using 90%, they think you’re one impulse buy away from applying for a clown college loan. Keep it low, and your score will thank you.
And whatever you do, don’t apply for a dozen credit cards in one week. That’s like speed-dating all the credit bureaus—they’ll compare notes, and you’ll look desperate. Pace yourself.
The Pre-Approval Dance
Before you fall in love with a shiny RV, get pre-approved. It’s like test-driving a car before promising to marry it. You’ll know exactly what you can afford, and you won’t get emotionally ambushed by a $600 monthly payment.

Dealerships love pre-approvals because it means you’re serious. Without one, you’re just a tourist with a dream and a cup of gas station coffee. They’ll show you the expensive models first, hoping you’ll cave and sign a 10-year loan with a payment that makes your wallet weep.
Pro tip: walk away if the monthly payment feels tight. Your future self will high-five you from a budget-friendly campsite.
The Funny Truth About RV Life
I know a couple who financed a $90,000 motorhome with a 720 credit score. They got a 5% APR and acted like they’d won the lottery. Then they spent the first trip stuck behind a slow truck, arguing about whether the GPS was wrong.
That’s the crux of it: the credit score gets you the RV, but it doesn’t buy you the experience. You’ll still have to fix a leaky faucet at 2 a.m. while mosquitoes treat you like a buffet. But you’ll do it in style—from your very own, financed-on-good-credit, home-on-wheels.
So, check your score. Pay down that credit card. And remember: even if your score is currently lower than your hopes, you can still get there. It just takes patience, discipline, and maybe a little prayer to the finance gods.
Now go forth and dream—but bring a calculator. Your RV future is waiting, and it might just come with a decent interest rate.