
What Happens When You Crash A Leased Car Without Insurance

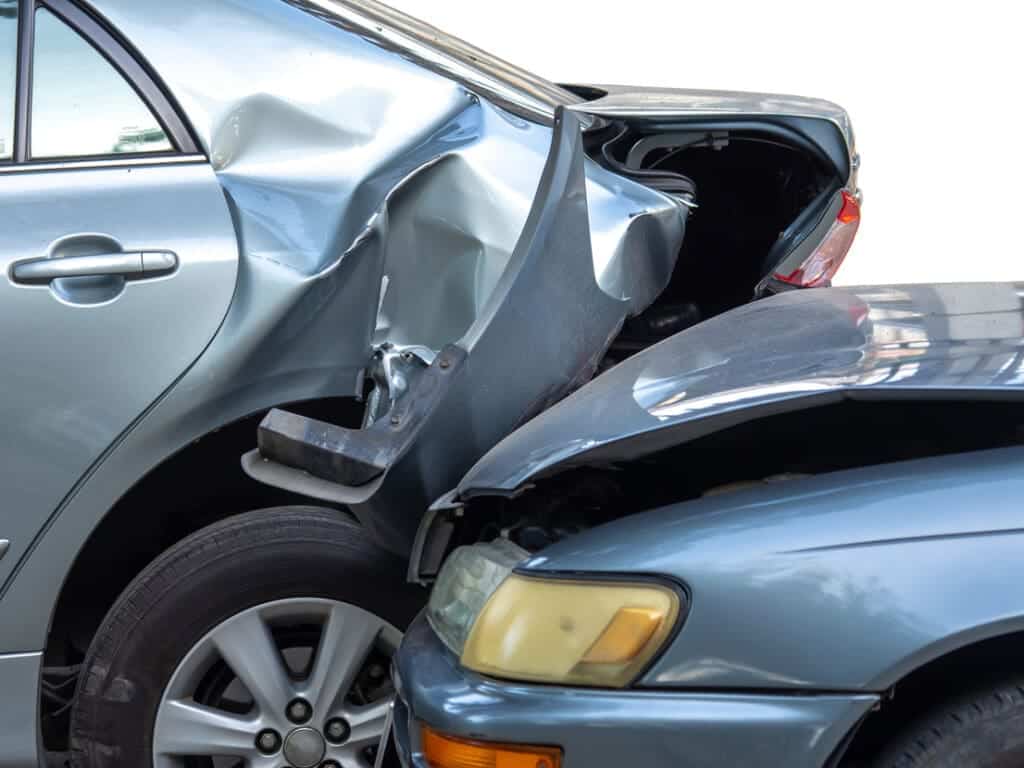
Imagine this: you’re cruising down the Pacific Coast Highway, sunroof open, playlist on shuffle, and you’re feeling like a movie star in your sleek, leased sedan. Then, in a split second, a rogue shopping cart or a distracted driver changes everything. You’ve crashed your leased car—and you have no insurance. Cue the dramatic record scratch.
Let’s be real: leasing a car is essentially a long-term rental with strict rules. You don’t own it; the bank or dealership does, and they expect you to treat it like a museum piece. When you sign that lease, you’re agreeing to maintain full coverage insurance. No exceptions, no “I’ll get it next week.”
So, what actually happens if you crash without that safety net? Buckle up, because the fallout is like a plot twist from a bad Netflix thriller—except it’s your wallet in the hot seat.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The Immediate Aftermath: Chaos and Legal Paperwork
First, the police show up, and you’re shaking as you hand over your license and registration. The officer asks for proof of insurance, and you stammer something about “forgetting to renew.” That’s when the first punch lands: a ticket for driving without insurance, which can cost hundreds to thousands of dollars, depending on your state.
If the accident is your fault, the other driver’s insurance will come after you personally. Your leasing company won’t be far behind, sending a very polite but terrifying letter demanding the car’s full value. Remember, the car isn’t yours—it’s a loan they expect back in perfect condition.
Pro tip: Never say “I’ll pay for the repairs out of pocket.” Leased cars require certified dealership repairs, and a single fender bender can easily cost $5,000 or more. You’re now the proud owner of a massive, unexpected debt.
The Financial Tsunami: Gap Insurance and the “Total Loss” Trap
Here’s where the fun really begins. If your leased car is totaled, you owe the leasing company the remaining lease payments plus the vehicle’s residual value. Without insurance, that’s on you—cash, credit card, or selling a kidney (not recommended). Most leases include gap insurance in the contract, but that only covers the difference between what you owe and the car’s market value—if you have a collision policy. Without it? You’re paying the full balance.
Think of it this way: you lease a $40,000 SUV, crash it after a year, and owe $35,000 left on the lease. The car’s market value is now $28,000. Without gap coverage, you’re on the hook for the full $35,000, plus towing, storage, and administrative fees. That’s not a car payment; that’s a second mortgage.
A fun fact from the Insurance Information Institute: nearly one in eight drivers in the U.S. is uninsured. Leasing companies know this, which is why they check your policy monthly. If you let coverage lapse, they’ll often force-place an expensive policy on your car—and bill you for it, with a hefty fine.
Legal Fallout: Lawsuits and Credit Score Horror Stories
If you can’t pay, the leasing company will sue you. They have lawyers, and you have a guilty conscience. A judgment against you can lead to wage garnishment, bank account levies, and a credit score that drops faster than a TikTok trend. Good luck leasing another car for the next seven years.
Worse, if someone was injured in the accident, you’re personally liable for their medical bills. Without insurance, you’re facing a potential lawsuit that could drain your savings and future earnings. This isn’t just a financial hiccup; it’s a life re-set.
Remember the scene in Breaking Bad where Walter White says, “I am the one who knocks”? In this scenario, the leasing company and the other driver’s lawyer are the ones who knock—on your bank account.
Practical Tips to Navigate This Nightmare
First, never panic-sell your belongings. Call a lawyer who specializes in auto finance or bankruptcy. Many offer free consultations, and they can negotiate a payment plan or even a settlement for less than the full amount. Yes, it’s awkward, but it’s better than ignoring the calls.
Second, know your state’s minimum insurance requirements. In Virginia, for example, you can pay an uninsured motorist fee to the DMV, but it won’t cover crash damage. In California, you must have liability insurance by law. Check your lease contract—most require $100,000 per person and $300,000 per accident in bodily injury liability.
Third, if you’re reading this before a crash, buy insurance today. Seriously, put down your phone and call Geico, Progressive, or a local broker. It’s cheaper than a single month of lease payments without coverage. A friend once told me, “Insurance is like a seatbelt—you don’t think you need it until you’re flying through the windshield.” She’s not wrong.
The “I Can’t Afford Insurance” Myth
Many people skip insurance because they think it’s too expensive. But consider this: the average full-coverage policy costs about $1,700 per year. Crash a leased car without insurance, and you’re looking at $35,000 in debt. That’s 20 years of premium payments. Which sounds more expensive now?
Also, some insurers offer “pay-per-mile” plans or low-mileage discounts for leased cars (since you’re limited to 10,000–15,000 miles a year). Shop around—you might find a plan for under $100 a month. That’s less than your streaming subscription and takeout habit combined.
A Final, Calming Reflection
In daily life, we often treat risk like a distant thunderstorm—we know it’s coming, but we assume we’ll be indoors when it hits. Crashing a leased car without insurance is that storm bursting through your roof at 3 AM. It forces you to confront a hard truth: the freedom of the open road comes with a responsibility to protect yourself and others.
The next time you slide into your leased car and hear that satisfying door thud, take a moment to appreciate the small luxury of being covered. Insurance isn’t just a boring bill; it’s a quiet promise that you can keep driving forward, even after a detour. So, make the call, pay the premium, and enjoy the ride with one less thing to worry about. Because the only plot twist you want in your life is a good one—with a happy ending.