
How Much Does Insurance Go Up After A Speeding Ticket
You’re cruising down the highway, maybe Dark Side of the Moon is playing at just the right volume, when a flash of red and blue appears in your rearview. Your heart drops into your stomach. That fleeting moment of lead-footed freedom is about to meet the cold, hard reality of your insurance premium.
Let’s be honest: we all know speeding is a bad habit, but the financial sting is what really gets our attention. The question isn’t if your rates will go up, but how much that little burst of velocity will cost you over the next few years. Buckle up—we’re about to run the numbers.
The Numbers Don’t Lie
According to industry data, a single speeding ticket can increase your annual premium by an average of 20% to 30%. That’s not just a slap on the wrist; it’s a full-on, wallet-hugging intervention.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
But wait, it gets spicier. If you were going 20 mph over the limit, you’re looking at a potential hike of 40% or more. In some states, that’s the difference between a gentle scold and a full-fledged insurance divorce, where your provider drops you altogether.
For context, a driver in New York might see a spike of around $600 a year, while someone in rural Ohio might only feel a $200 bump. Your location, your insurer, and your driving history are the secret sauce in this expensive recipe.
The “Date” That Haunts You
Here’s a fun little fact: insurance companies don’t forget. A speeding ticket typically stays on your driving record for three to five years, depending on your state. That means you’re paying for one bad decision with every monthly statement.
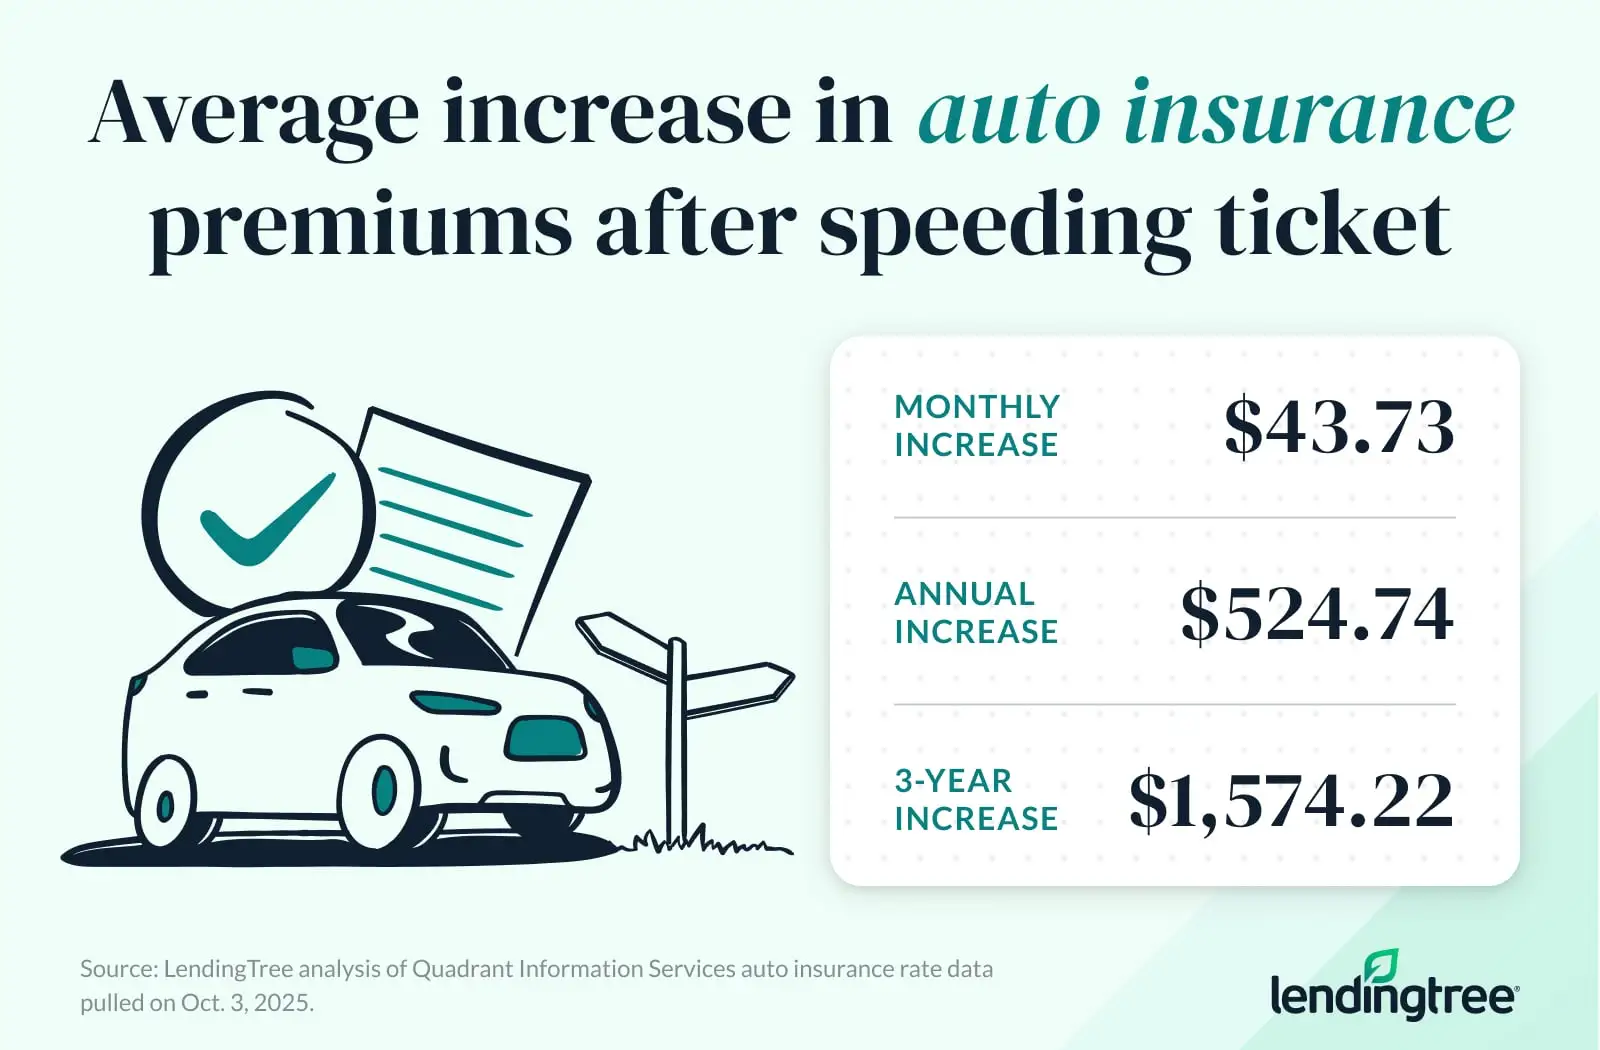
Consider this: if your premium goes up by $300 a year and the ticket stays for three years, you’ve just spent $900 on what was probably a two-minute thrill. That’s a week’s worth of groceries or a very nice pair of sneakers.
It’s a bit like that scene in Ferris Bueller’s Day Off where Cameron stares at the mileage on the Ferrari—except the odometer is your bank balance, and the car is your Honda Civic.
Practical Tips to Soften the Blow
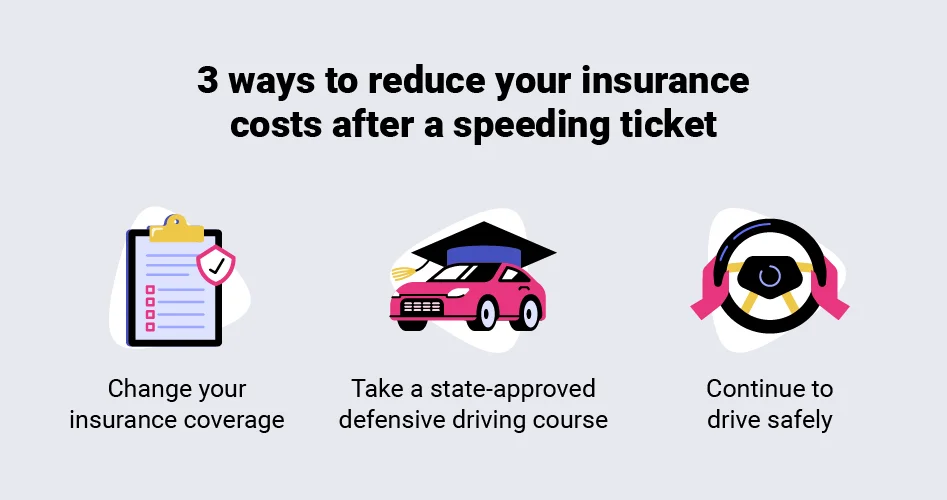
So, you got the ticket. It’s done. Now what? First, don’t just pay it blindly. In many states, you can take a defensive driving course to have the ticket dismissed or the points reduced. This is your get-out-of-jail-free card, and it usually costs less than the premium hike.
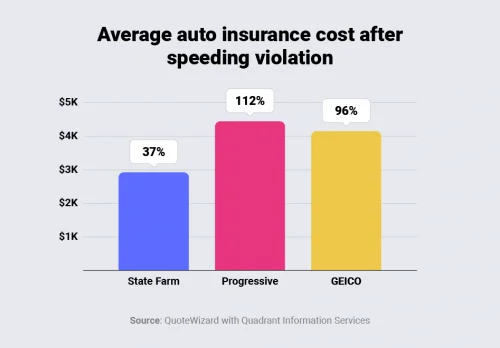
Second, shop around for a new policy after the ticket hits your record. Not all insurers treat speeders the same. Some, like GEICO or Progressive, are more forgiving than others, especially if you’ve been a loyal customer.
Third, ask about accident forgiveness or ticket forgiveness programs. Many companies offer these as add-ons for a few extra dollars a month. If you have a tendency to play “lead foot” at stoplights, this is your safety net.
The Cultural Speed Trap
You know who else understands this pain? The cast of Top Gun—Maverick might feel the need for speed, but he’d still cry when the insurance bill arrives. Pop culture romanticizes fast driving, but real life is about that spreadsheet.
There’s even a study that found men under 25 see the highest rate spikes, because insurance companies look at demographics like a stern uncle. It’s not personal; it’s math. If you’re a female driver over 40, your bump might be half that.
And here’s a weird twist: if you live in a state like Michigan or Louisiana, your rates are already sky-high, so a ticket might feel like adding a cherry to a sundae you never ordered. In Maine? That same ticket could feel like a financial earthquake.
The Hidden Costs
Don’t forget the ticket itself. Fines vary wildly, from $50 in some counties to $500 in others. Add court costs, potential lawyer fees, and the premium increase, and you’re suddenly funding a small vacation for your insurance company.
There’s also a psychological toll. Every time you drive past a cop, you tense up. You start checking your speedometer like it’s a trust exercise with your own sanity. It’s the mental equivalent of wearing a “kick me” sign.
But here’s the good news: if you can go 12 to 18 months without another ticket or accident, most insurers will start to lower the surcharge. It’s like a probation period where good behavior is rewarded with lower payments.
A Little Reflection for the Road
Life is a series of small decisions that compound over time. That extra five miles per hour you pushed on your way to work might have saved you two minutes, but it cost you two years of higher bills.
It reminds me of that line from Fight Club: “You are not your job.” You’re also not your speeding ticket. One slip-up doesn’t define your whole driving life, but it does define your insurance premium for a while.
So next time you feel the urge to race the yellow light, think about your future self sipping coffee, staring at a bill. Slow down. Your wallet, your blood pressure, and your insurance agent will thank you.