
How Much Does Insurance Go Up After Speeding Ticket
Okay, let’s be real for a second. You’re cruising along, maybe singing a little too loud to a song you’d never admit to liking, when you see those dreaded flashing lights in your rearview mirror. Your heart drops into your stomach faster than a bad relationship. We’ve all been there, and the first question that pops into your head isn’t “How do I fight this?”—it’s “How much is this going to cost me over the next three years?”
The short, not-so-sweet answer is: a lot more than the ticket itself. That slip of paper might sting for $150, but your insurance company is going to treat you like you just confessed to stealing their favorite lawn gnome. They’re going to raise your rates, and they’ll do it with the enthusiasm of a cashier counting your change for a penny.
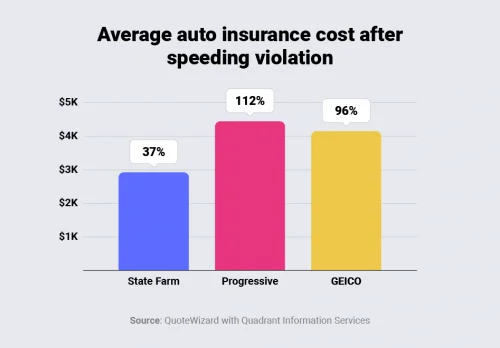
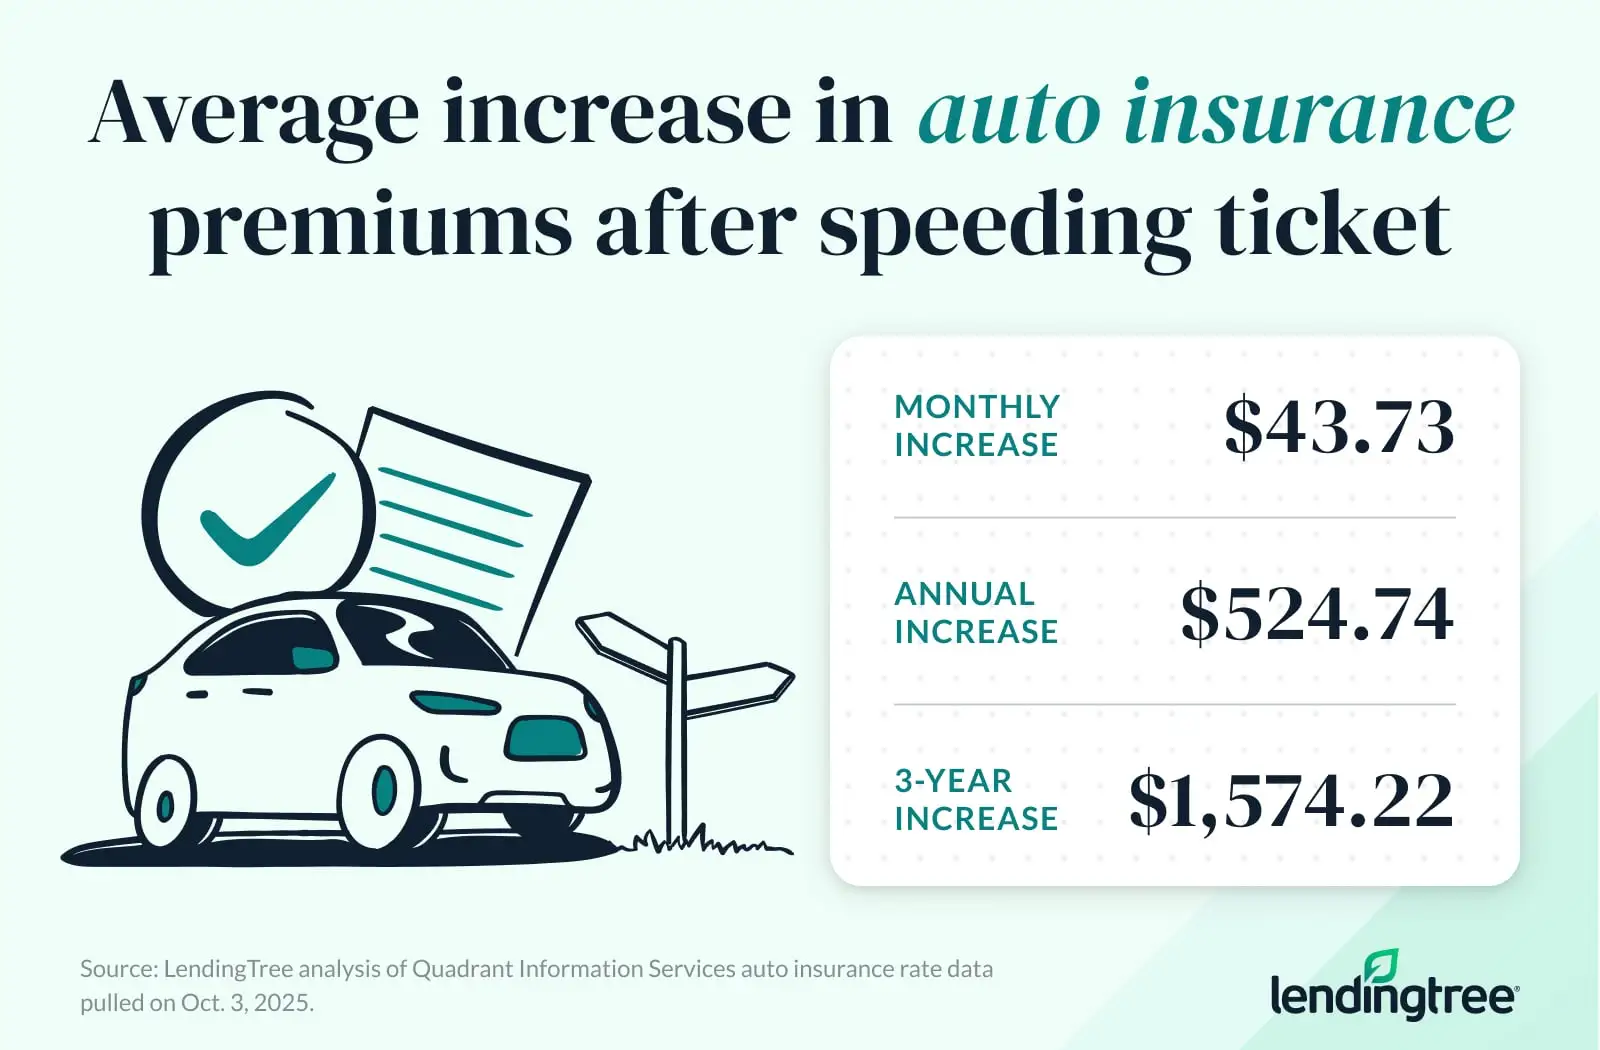
Let’s break it down without the boring jargon. On average, a speeding ticket can bump your annual premium by about 20 to 30 percent. If you were paying $1,500 a year, that’s an extra $300 to $450—every single year, for at least three years. It’s like paying for a gym membership you never use, except the payment is for something you actually did.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Why Do They Hate Speeders So Much?
Think of your insurance company as your super-strict, slightly paranoid aunt. She sees one little speeding ticket and suddenly imagines you doing donuts in a school parking lot. Statistically, speeders are riskier drivers, and insurance is all about betting on risk. You’ve just shown them you’re more likely to crash, so they’re raising your bet.
The actual number depends on how fast you were going. A “5 over” ticket is like forgetting to take out the trash—annoying but manageable. A “20 over” ticket is like setting the trash can on fire in the driveway. It’s a much bigger deal. Speeds over 20 mph can easily push your rate increase to 40% or more.
And here’s the kicker: it’s not just one bump. That increase typically sticks around for three to five years. You could buy a used car with that money. Or, you know, a really nice vacation to a place without speed limits, like a desert island.
The First-Timer vs. The Repeat Offender
If this is your first rodeo, you might get off easier. Some insurance companies offer a “first offense forgiveness” or a small slap on the wrist. It’s like your boss giving you a warning after you showed up late once. But if you have a history—well, then you’re the office clock-in at 10:15 AM every Monday.
For repeat offenders, the increase can double. I had a buddy who got two tickets in six months. His insurance went up so fast, he started walking everywhere and calling it “eco-friendly cardio.” He saved money, sure, but he also missed a lot of barbecues.
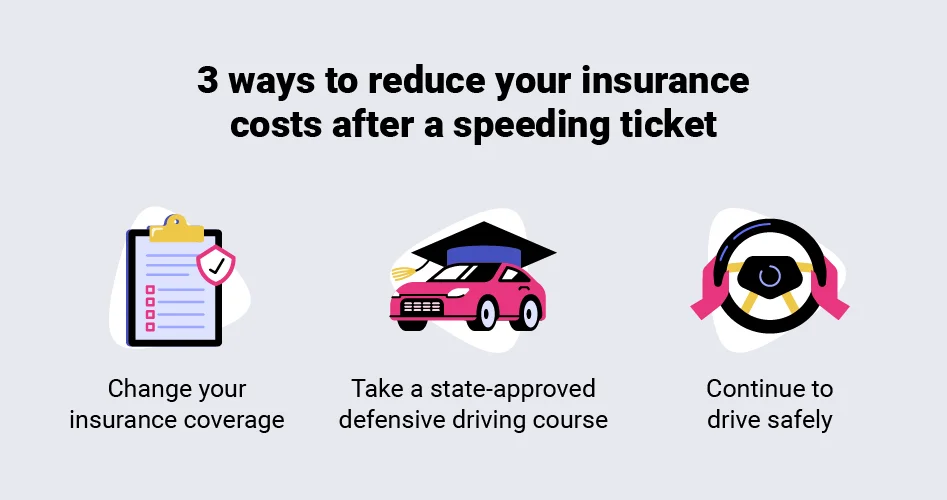
You might be thinking, “I’ll just take a defensive driving course!” Good news: it helps. Many insurers will reduce the surcharge if you complete a certified course. It’s like baking a apology cake for your aunt—it shows you’re trying. It won’t erase the mess, but it makes the room smell better.
How to Know Exactly What You’re In For
Don’t guess. Call your insurance agent and be honest. Say, “Hey, I got a ticket. Don’t judge me. What’s the damage?” They’ll give you a rough number. Alternatively, you can shop around. Insurance companies are like Tinder dates—some are grouchy about your past, and others are more forgiving if you have a clean driving record otherwise.
One more thing: points on your license matter. In most states, speeding tickets add points, and those points are like sneaker scuffs on a white carpet. Too many, and you might lose your license entirely. Then your insurance really skyrockets, because you’ll have to get a high-risk policy, which is basically the insurance version of a sketchy motel.
I remember a neighbor who bragged he’d never had a ticket. Then he got one for going 41 in a 35. His premium went up $200 a year. He still brings it up at block parties, shaking his head like he’d been framed by a traffic camera. We all have that friend.
The Bottom Line
So, how much does insurance go up? Expect a 20% to 40% increase for three years. But here’s the silver lining: if you avoid another ticket, the increase fades over time. It’s like a bad haircut—eventually, it grows out and no one remembers you looked like a confused poodle for six months.
Until then, maybe ease off the gas. Set your cruise control to exactly the limit. Pretend your grandma is in the passenger seat, holding a full cup of tea. Or just invest in a good radar detector—but I didn’t tell you that. Drive safe, or at least drive smart enough to afford dinner out.