
How To Get Out Of Car Finance With Negative Equity

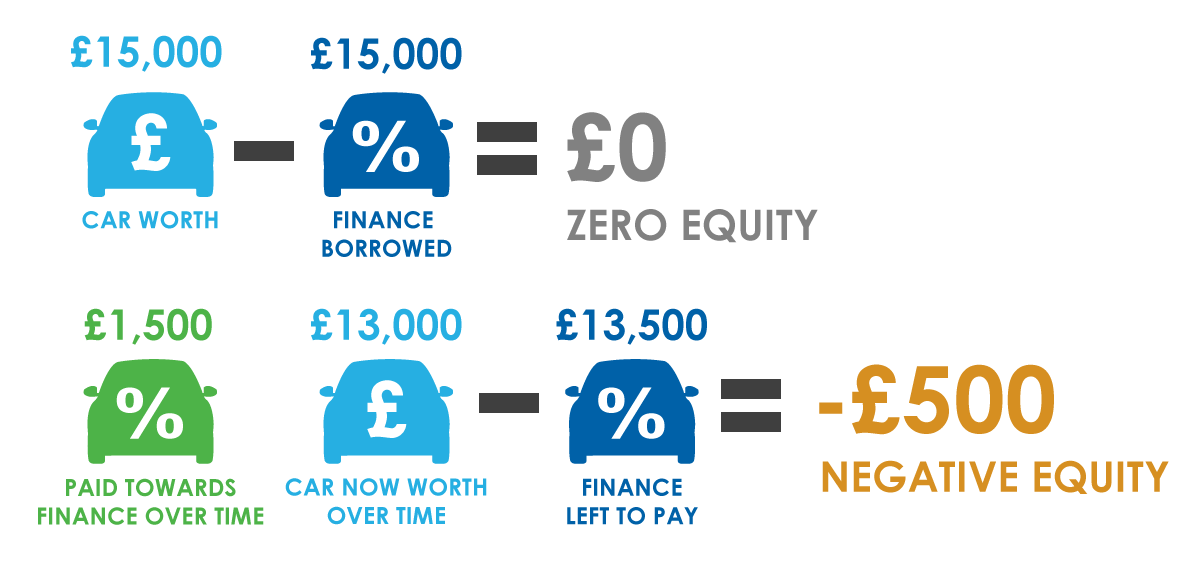
Okay, let’s be real for a second. You’re sitting there, staring at your car keys, and they feel more like heavy, iron shackles than freedom. You owe more on your loan than the car is worth—that sticky, awful thing called negative equity.
It’s like you brought a half-eaten pizza to a party and the host still expects you to pay full price. Don’t panic. We’re going to map out a few escape routes that don’t involve a magic wand or a time machine (though, wouldn’t that be nice?).
First, Take a Deep Breath. Seriously.
Negative equity feels like you’re trapped in a financial bear hug, but you’re not stuck forever. The most important thing you can do right now is stop ignoring the problem. It’s like that weird smell in your fridge—it only gets worse if you pretend it doesn’t exist.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Take a quick look at sites like Kelley Blue Book or NADA. Find out what your car is actually worth today. It might sting. It will probably sting. But knowing the number is your first step to freedom.
Option One: The “Ride It Out” Grin
This is the boring but brilliant option. If your car is reliable and not actively trying to self-destruct, keep driving it. Make your payments until the loan balance catches up to the car’s value. Think of it as a slow-motion race where you’re rooting for the turtle.
Every payment you make is a tiny victory. You’re chipping away at that negative equity lump of coal, and one day it’ll turn into a diamond... or at least a piece of shiny glass. Patience is free therapy here.
Pro Tip: Pay a Little Extra Each Month
If you can spare an extra $20 or $50 a month, do it. That extra cash goes straight to the principal, which is like hitting the fast-forward button on your negative equity escape. It’s not glamorous, but neither is eating ramen for a week.
Option Two: The “Save Up and Smash It” Move
Okay, so you want out, now. Fine. You’ll need to save up enough cash to cover the gap between what you owe and what the car is worth. This is called bringing money to the table, and it’s the adult version of paying your way out of a wet paper bag.
Let’s say you owe $15,000, but your car is worth $10,000. You need $5,000 in cold, hard savings. Start a side hustle. Sell old video games. Babysit a neighbor’s very needy cat. It’s not forever, and when you hand that check over, you’ll feel like a financial ninja.
Option Three: The “Trade-Down Tango”
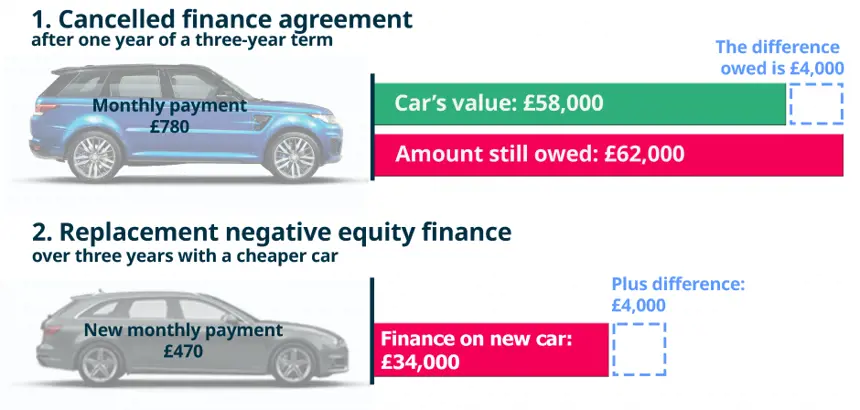
You walk into a dealership, trade in your car (with its negative equity), and buy a much cheaper car. This is the art of the “trade-down.” You roll the old loan’s balance into the new, cheaper loan. But here’s the trick: you want the new car to be so affordable that your monthly payment drops to something you can actually laugh about.
For example, trade a $30,000 SUV for a $12,000 used hatchback. You’re still paying off the old debt, but now your payment is $200 less per month. Magic? No. Math? Yes. Just don’t fall in love with a shiny new SUV in the showroom while you’re doing this.
Option Four: The “Refinance Rollercoaster”
If you have decent credit, refinancing might lower your interest rate. That means more of your monthly payment goes to the principal, and less gets eaten by interest. It’s like putting your loan on a diet—same calories, but more nutrition.
Be warned: you usually can’t refinance if the loan is hugely upside down. Lenders get nervous. But if you’re only a few thousand underwater and your credit score is above 670, it’s worth a ten-minute phone call. Worst they say is no, and you’re back to Option One.
Option Five: The “Voluntary Surrender” (The Sad Trombone)
This is the nuclear option. You call your lender and say, “I can’t pay. Come get the car.” They repossess it, sell it at an auction (for peanuts), and then sue you for the difference. Your credit takes a massive hit. It’s not a “fun” escape; it’s a trapdoor that leads to a swamp.
Do not do this unless you are truly staring down bankruptcy or a medical emergency. It should be a last, desperate resort. Think of it like eating that weird leftover casserole from the back of the fridge—you’ll probably survive, but you won’t enjoy it.
The Secret Sauce? Don’t Panic-Sell to a Private Buyer
You might think, “I’ll just sell my car to a stranger on Facebook Marketplace!” Great idea—except you still owe the bank. They have the title. You’d have to ask the buyer to pay you, you pay the bank, and then wait for the title. It’s clunky and stressful. Plus, strangers are weird.
If you do sell privately, only do it if you have the cash to pay off the loan immediately. Otherwise, stick to the options above.
The Uplifting Conclusion (You Knew It Was Coming!)
Here’s the truth: negative equity is a season, not a life sentence. It feels heavy because it is heavy, but you are carrying it with a full tank of gas and a engine that won’t quit. Every payment you make is a brick you’re removing from that wall.
One day, you’ll look at your loan statement and see a balance that matches your car’s value. And on that day, you’ll have the freedom to trade, sell, or keep that glorious machine with a smile. You are not your negative equity. You are a savvy, resilient human who just happens to owe a few extra bucks on a depreciating asset. You’ve got this.
So go ahead, give your steering wheel a little pat. Thank it for getting you this far. And then make a plan—because your next car story is going to be a happy one. Drive on, my friend.