
How Long Do Delinquencies Stay On Credit Report

So, picture this: my friend Dave—solid guy, always pays his share of the pizza—calls me in a panic last week. He’d applied for a car loan, got denied, and found out a missed payment from three years ago was still haunting him. He asked me, genuinely baffled, “How long do these things stick around, anyway?”
Well, Dave, you’re not alone. That little ghost of a delinquency—whether you forgot a credit card bill or ran into a rough patch—can feel like it’s glued to your financial life. But here’s the good news: it’s not forever. Let’s break it down—in plain, slightly sarcastic English.
The Seven-Year Rule (Yes, It’s That Long—But With a Catch)
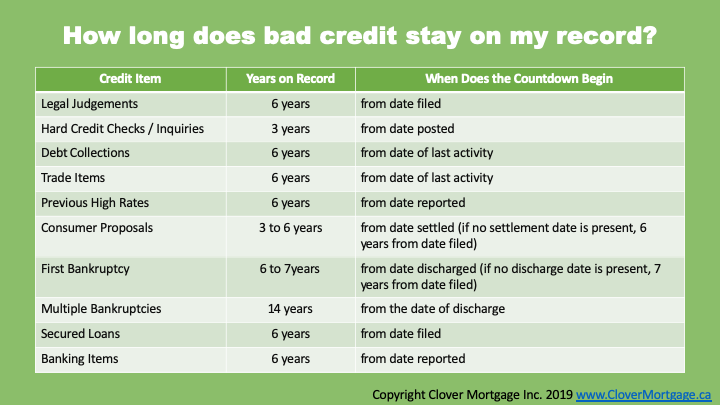
For most negative items—like late payments, charge-offs, or collections—seven years is the magic number. That’s how long they can legally stay on your credit report, counted from the date of the first missed payment (the “original delinquency date”).
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
I know, seven years sounds like a lifetime in internet years. But think of it this way: it’s less than a decade, and honestly, the impact fades over time. A missed payment from year one hurts way less than one from year six, because your recent good behavior starts to shout louder.
Hey, you know that saying “time heals all wounds”? Credit wounds are no exception—they just take a little longer than a scraped knee. And no, a new payment won’t reset that seven-year clock, so don’t worry about poking the bear.
What About Chapter 7 Bankruptcy or Tax Liens? (Spoiler: They’re Stickier)
Now, if you’ve had a Chapter 7 bankruptcy, that stays for ten years from the filing date. A Chapter 13 bankruptcy? That’s seven years, too, but sometimes lenders treat it more gently since you’re repaying part of the debt. (Ironic, right?)
Unpaid tax liens used to hang around forever, but as of 2018, the credit bureaus changed the rules. Now, paid tax liens disappear after seven years from the payment date. Unpaid ones? They can stay indefinitely—so maybe don’t ignore the IRS. Just a thought.
Oh, and student loan defaults? They follow the same seven-year timeline as other delinquencies, unless you rehab them. Default for nine months, and boom—that stain appears. But once you fix it, the clock starts ticking on the original mess.
The Good News: The Impact Diminishes Like a Bad Hangover
Here’s the ironic part: your credit score doesn’t hold a grudge forever. After about two or three years, a single late payment loses its sting, especially if you’ve been on time since. Lenders care more about recent behavior than ancient history.
Imagine you screwed up at work once in 2021. By 2024, if you’ve been killing it, your boss remembers you as the rockstar, not the slacker. Credit is the same way—new good habits outrank old mistakes. So don’t panic over one slip-up from five years ago.
But if you have a collection account that’s still unpaid? That can renew its seven-year window if the debt is sold to a new collector. Yeah, it’s annoying—like a guest who won’t leave the party. Check your report every year for errors, fam.
How to Check When It’s Finally Gone (Without Losing Your Mind)
You can pull your credit reports for free at AnnualCreditReport.com (the only official site—don’t get scammed by those “free trial” traps). Look for the “date of first delinquency” on any negative item. Count seven years from that month, and you’ll know when it’ll vanish.
Pro tip: Don’t trust the “delete by” date on some apps. They can be off by months. I once saw a report that claimed a 2015 missed payment would disappear in 2023—looked closer, and the original delinquency was in 2014. Always verify the dirty laundry, my friend.
And if you see an error—say, a delinquency from eight years ago still hanging around—you can dispute it with the credit bureau. They have 30 days to verify or delete it. I do this every year, like a digital spring cleaning.
What Can You Do in the Meantime? (Besides Crying Into Your Coffee)
While you wait out those seven years, pay everything on time—even your Netflix subscription (although Netflix doesn’t report to credit bureaus, but you get the vibe). The weight of your credit score comes from your most recent 24 months of payments.
Also, keep your credit utilization low—like under 30% of your limits. That alone can boost your score by 20–50 points, even if you have a delinquency. It’s like wearing a killer jacket to distract from a coffee stain on your shirt.
Finally, remember: you are not your credit report. Delinquencies are just financial bad hair days. After seven years, they fade like a bad dream—and by then, you’ll have built a shiny new record of responsible choices. Dave ended up getting a co-signer and a better rate six months later. You will, too.
So go ahead, check your report, count the years, and breathe. The clock is ticking—in your favor this time.