
What Is The Minimum Credit Score For An Rv Loan
So, you’ve been dreaming of hitting the open road, haven’t you? Maybe it’s the smell of pine trees, the sound of waves, or just the pure freedom of having your bedroom follow you anywhere. But then reality taps you on the shoulder with that one, slightly intimidating question: “What is the minimum credit score for an RV loan?”
Relax. Take a deep breath, because the answer is probably better than you think. While you might assume you need a flawless 800 (like some mythical credit king or queen), the truth is much more forgiving. Let’s break it down, road trip style.
The Magic Number (Spoiler: It’s Lower Than You’d Guess)
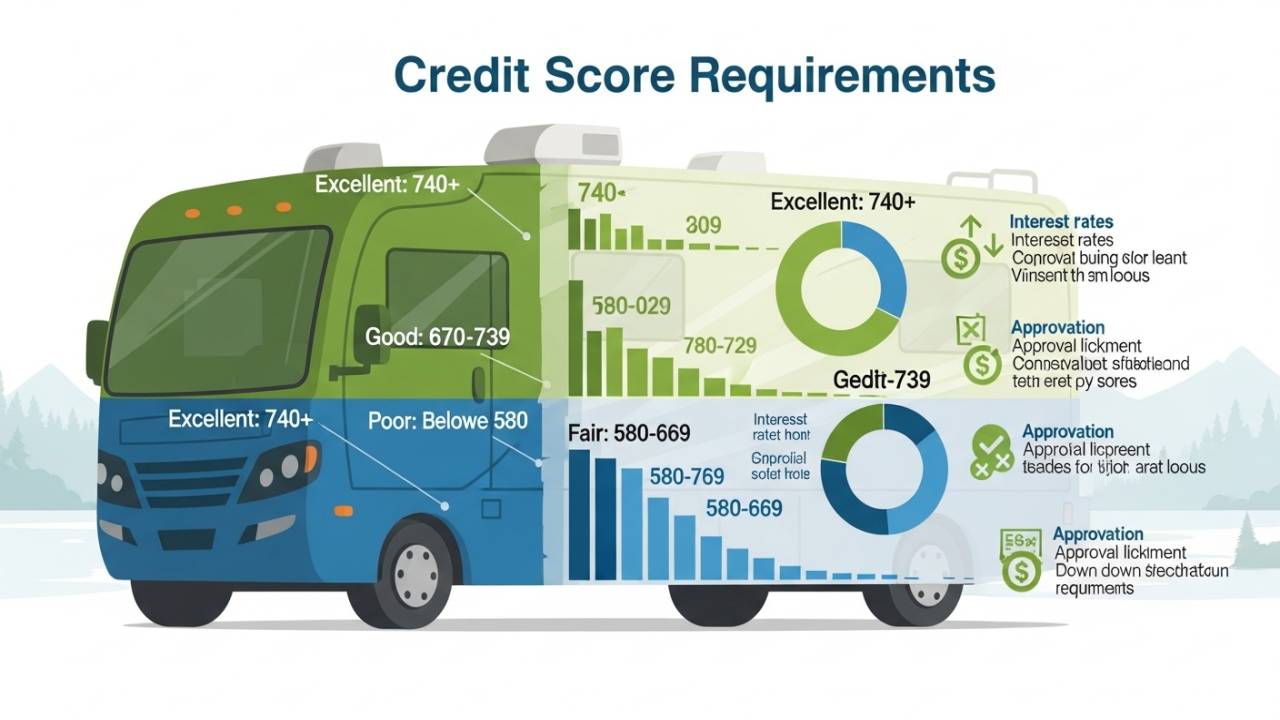
For a standard RV loan from a bank or credit union, the sweet spot starts around 660 to 700. That’s a “fair” to “good” score, not a perfect one. If your credit is hovering near 660, lenders will likely say “yes,” but you’ll probably get a higher interest rate. Think of it as the extra fee for the scenic route.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
But here’s where it gets fun—and inspiring. Have a score below 660? Don’t you dare give up yet. Many specialized RV lenders and dealerships work with scores as low as 580 to 620. Yes, you read that right. They know life happens—a late bill here, a surprise expense there—and they’d rather get you in a camper than leave you stuck in the driveway.
What About a “Zero” Score? (Don’t Do That)
If you have no credit history at all, that can be trickier than having a low score. Lenders like to see some track record, even if it’s a little bumpy. A 580 score says, “I’m trying,” while a blank slate says, “I have no idea what this person does with money.” So, if you’re credit-invisible, grab a secured card for six months first. It’s a tiny detour for a giant payoff.
Also, keep in mind that a $50,000 towable trailer is way easier to qualify for than a $200,000 motorhome. The cheaper the RV, the more lenient the lender. That’s just math, baby!
How to Give Your Score a Sugar Rush (Even This Week)
Let’s say your score is a 630 right now. You can boost it 20-30 points in just 30 to 60 days. How? First, pay down your credit card balances to below 30% of your limit. That “utilization” ratio is a huge factor. Second, dispute any tiny error on your credit report—a $25 medical bill you already paid can be a hidden anchor.
And here’s the golden rule: Don’t apply for any new credit cards or car loans for at least three months before your RV loan. Every hard inquiry dings your score a few points. Think of your credit file like a sleeping bear—don’t poke it with a stick until you’re ready to hitch up.
The “Boondocker’s Hack” You Need to Know
What if your credit is truly rough—say, below 540? You’re not out of luck. Many RV dealers offer “in-house financing” or partner with buy-here-pay-here lots. Yes, the interest rate will be higher (think 10-14%), but you’ll get the rig now. Then, you refinance the loan in 12-18 months after you’ve made all your payments on time. Boom. You’ve just upgraded your credit score AND your lifestyle.
Just remember: An RV is an asset that can lose value, so don’t borrow more than you absolutely need. But hey, if you’re buying a used Class C that costs $25,000, and your score is 580, the monthly payment might only be a few hundred bucks. That’s less than a nice apartment.

So, What’s the Real Minimum?
Here’s the honest, upbeat truth: There is no single “minimum.” It depends on the lender, the RV’s price, your down payment, and your income. If you put 20% down (that’s just $6,000 on a $30,000 camper), even a 580 score can get a thumbs up. If you have a solid job but a shaky score, lenders love that combo.
The real magic? Start the conversation. Call a local credit union (they’re usually nicer than big banks) and ask, “Hey, what’s the lowest you’ll take?” You might be shocked by their answer. I’ve seen people with 620 scores drive off in a shiny little travel trailer, grinning like they just won the lottery.
So, don’t let fear of a number keep you parked. Your credit score is not your destiny—it’s just a starting point. Maybe you’re not ready to buy today, but you can check your score for free, make a tiny plan, and start dreaming of where that first campsite will be. The road is waiting, and it doesn’t care about your score. It only cares that you show up.
Go ahead. Learn a little more tonight. Look up that used RV listing you’ve been secretly staring at. Tomorrow, check your credit. The next day, call a lender. Before you know it, you’ll be reading a different article—this one about the best national parks for boondocking. And you’ll be reading it from your very own driver’s seat. See you out there!