
What Credit Score Is Needed To Finance A Camper
So you’re dreaming of hitting the open road in a camper, right? Maybe you’ve already picked out the perfect little home-on-wheels. But then reality hits: you need a loan.
And that loan brings up everyone’s favorite party topic—your credit score. Let’s talk about what number you actually need without all the boring banker-speak.
The Short, Sweet Answer (Because We’re All Busy)
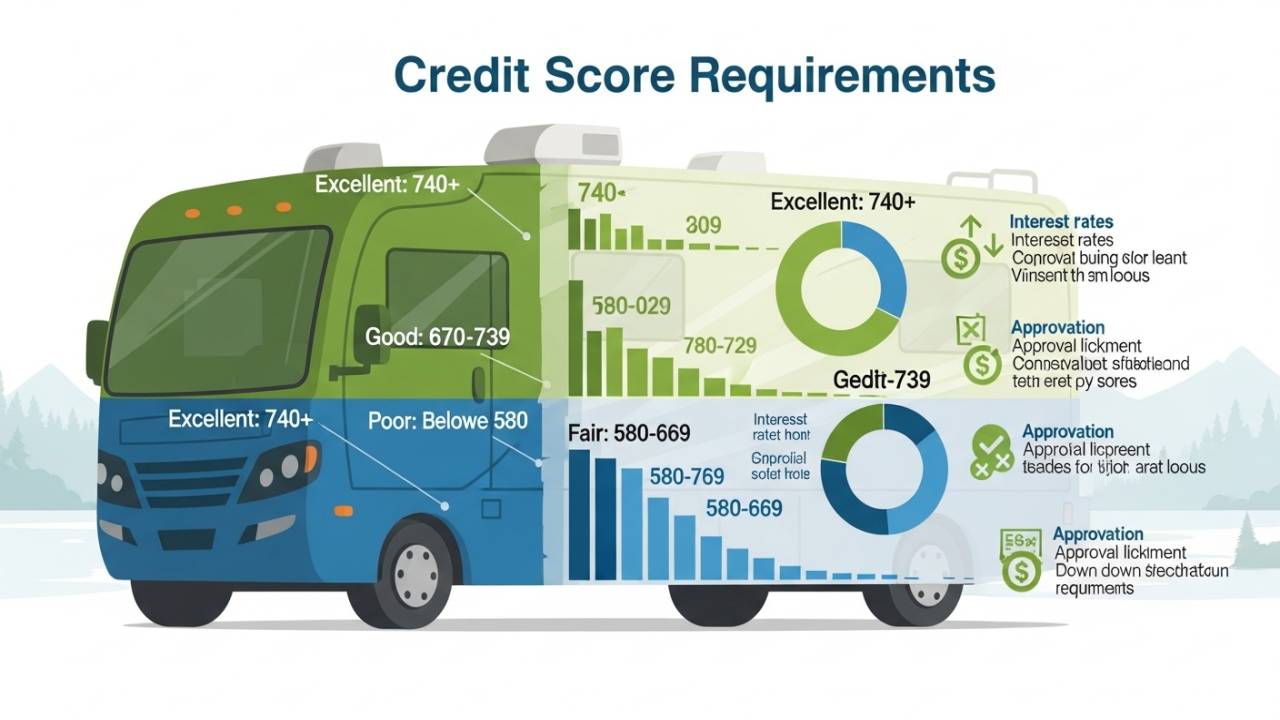
For a new camper, lenders usually want a score of 680 or higher. Yes, that’s a bit of a gatekeeper moment.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
For a used camper (the kind that’s already seen a few sunsets), they might be a little more chill—think 640 or above. Anything lower? You’re not out of luck, but you’ll pay for it.
Remember, a camper is recreational property. It’s not a house. Lenders treat it more like a fancy car that doesn’t come with a steering wheel to your job.
Why 680? What’s So Special About That Number?
Honestly? It’s the line where lenders stop worrying you’ll forget to pay. It’s like the bouncer at a club—680 is the “you’re in” level.
Below that, they ask for more paperwork, a bigger down payment, or a loan with interest rates that make you weep. I’m talking 12% or higher on a good day.
Don’t shoot the messenger. I’m just the person telling you that credit scores are weirdly powerful.
The Exceptions (Because Life Loves Curveballs)
What if your score is a 580? Should you just give up and rent a tent? Not so fast. Some lenders specialize in “subprime” loans. They’re out there.
But be ready: you’ll need a down payment of at least 20%. Also, your interest rate might make your camper payment feel like a second mortgage. Ouch.
Or you could get a co-signer. Someone with great credit who loves you enough to risk their score for your wanderlust. That’s a real friend.
What About “No Credit” People?
Ah, the invisible credit ghosts. If you have no score, lenders get nervous. They can’t judge you, so they default to “danger.”
Your best bet? Save up a huge down payment—like 30-40%. Or buy the camper from a private seller who doesn’t care about your FICO. Cash is king in this barter.
Just don’t be shocked if a dealer offers you a loan with a 20% interest rate. That’s their “I don’t know you” price.
The Type of Camper Changes Everything
Not all campers are created equal in the eyes of a banker. A tiny teardrop trailer? That’s a cheap loan, often with easier terms.
A giant fifth-wheel that costs $80,000? Now you’re in “luxury RV” territory. Lenders want a score of 700 just to consider you.
And a motorhome (the one you drive) is even stricter. It’s like a house and a truck had a baby, and that baby demands perfect credit.
Interest Rates: The Real Party Spoiler
Here’s a fun little chart nobody gives you. With a score of 760+, you might get 6% interest. Nice. With a 620 score? Try 15%.
On a $30,000 loan over 10 years, that difference is like throwing away $10,000 in extra payments. That’s a lot of s’mores you could buy.
So yeah, fixing your credit score before you buy is basically free money. Don’t skip that step.
How to Sneak Into a Better Score (Without a Time Machine)
You can’t magically boost your score overnight. But you can be smart for a few months. Pay off credit cards. Don’t open new accounts. Wait.
Oh, and check your credit report for mistakes! I once found a random $500 collection I never knew about. Removing it shot my score up 30 points. Free win.
If your score is 650, aim for 680. That’s the magic threshold where lenders start smiling instead of frowning.
The Down Payment Hack
Even with a decent score, a 10% down payment helps a ton. It shows the bank you’re serious. It’s like a handshake with a firm grip.
Put down 20%? You might not even need great credit. Some lenders will approve you with a 600 if you’re putting serious skin in the game.
Money talks. So does a down payment. Make it loud and proud.
Real Talk: Can You Finance a Camper with a 550?
Technically, yes. But it’s like asking if you can buy a pizza with pocket lint. You can, but the exchange is rough.
You’ll need a buy-here-pay-here dealership. They’re the pawn shops of the RV world. High rates, older campers, and contracts that could use a lawyer.
Honestly? If you’re at 550, take six months to fix your credit. You’ll save thousands. Your future camping self will high-five you.
Quick Cheat Sheet for Your Coffee Chat
Score 740+: You’re the king of the road. Get the loan with a 5% rate and go. Score 680-739: You’re fine, but shop around for rates.
Score 640-679: You can do it, but expect a higher payment. Score under 640: Time to work on that score or save cash.
And if you’re at 600? Maybe start with a pop-up camper from a private seller. Baby steps, my friend.
A Final, Honest Thought
Your credit score isn’t your whole life. It’s just a number that banks use to guess if you’re responsible. It’s dumb, but we play the game.
Don’t let a bad score stop you from planning your adventures. You can still camp. You can still dream. You just might have to wait a season or two.
And honestly? The best campers are the ones that come with a story, not a perfect loan. Now go check your score. You got this.