
Is Liability Insurance The Same As Workers Comp
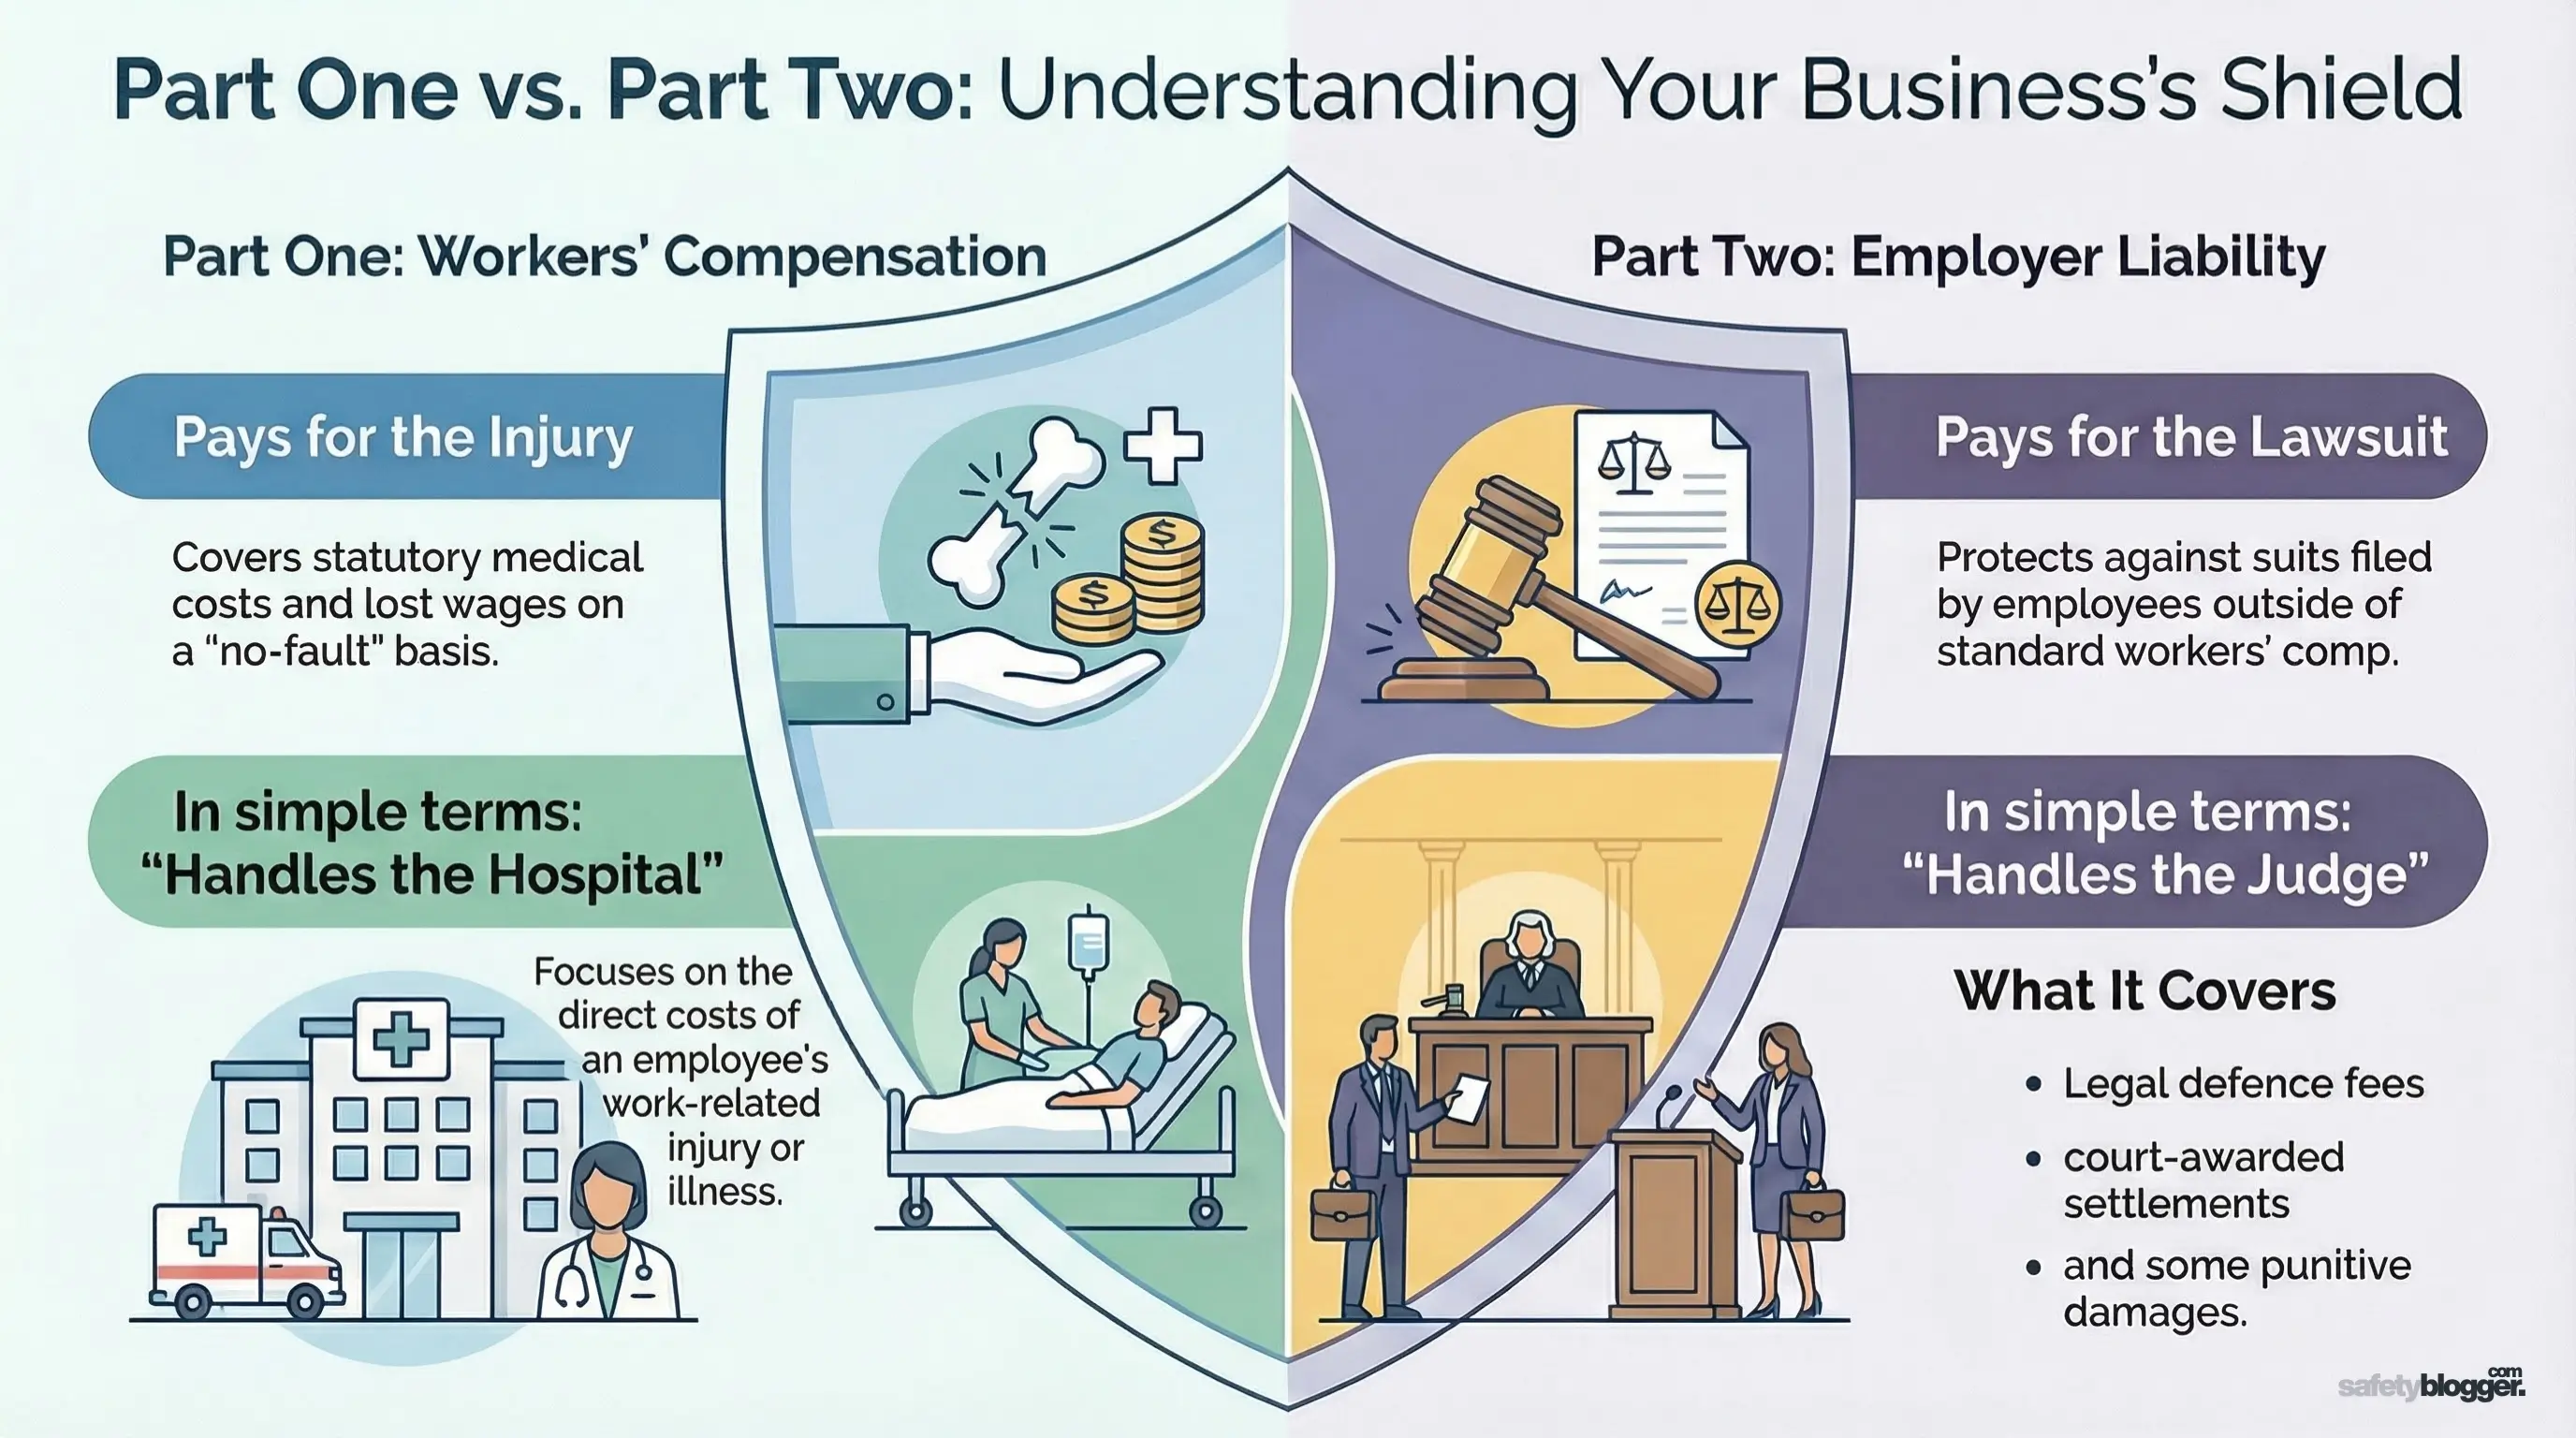
Let’s get one thing straight: liability insurance and workers’ comp are not the same thing. It’s like comparing a umbrella to a fire extinguisher. Both keep you dry in different disasters.
Liability insurance is the cool, collected peacekeeper. Workers’ comp is the frantic, loving nurse. They handle two very different kinds of messes.
The Showdown: Who Covers What?
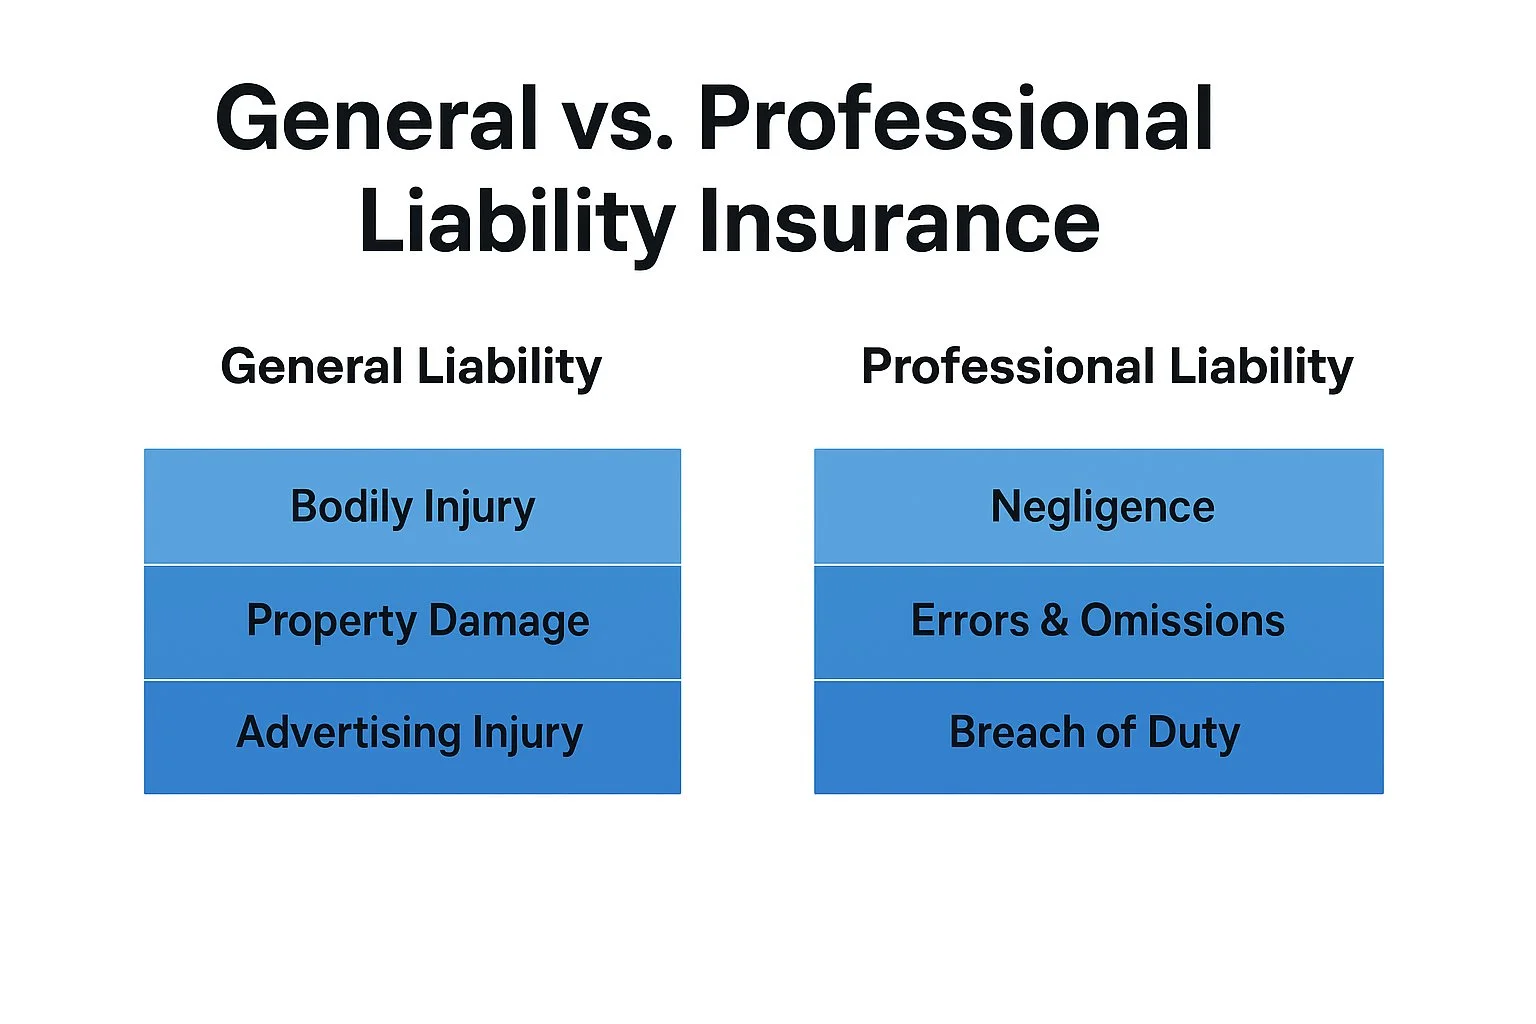
General liability protects you if you accidentally hurt a customer. Think: a slippery floor, a falling sign, or your dog bites a delivery driver.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Now, workers’ comp is all about your employees. It covers medical bills and lost wages when your team gets hurt on the job. Think: paper cuts, back strains, or a tragic office chair battle.
Here’s the funny part: if you spill hot coffee on a client, liability handles it. But if that same coffee spills on your assistant? That’s workers’ comp time.
A Quirky Fact That Will Blow Your Mind
In most states, workers’ comp is mandatory—even for one employee. Liability insurance is often optional, but skipping it is like tightrope walking without a net. Amazingly funny, until the wind blows.
Workers’ comp includes the “exclusive remedy” rule. This means an injured worker can’t sue you for pain and suffering. They just get their bills paid. It’s a weird trade-off: no drama, but no revenge lawsuit.

Liability insurance, however, loves a good court battle. It pays for lawyers, settlements, and that awkward moment you explain to the judge why your banana peel was on the floor for three hours.
Why People Mix Them Up (And Why That’s Hilarious)
Both policies involve accidents. Both involve money. So folks assume they’re twins. But that’s like saying a cat and a toaster are the same because they both sit on counters.
A classic mix-up: a small bakery owner bought only workers’ comp. Then a customer slipped on a muffin. The owner had to pay out of pocket while the employee got a spa day of medical care. Oops.
Another gem: a freelance graphic designer bought general liability. Then she sprained her wrist drawing a logo. Her insurance laughed politely. No coverage for self-hurt. Workers’ comp only covers employees, not solo artists.
The Fun, Ridiculous Details
Workers’ comp policies sometimes cover weird injuries. Like a worker who got stung by a bee while delivering mail. Or the guy who tripped over a cat at the office. Yes, that’s real.
Liability insurance once paid for a man who sued because a hotel’s parrot called him a bad name. Emotional distress, baby. Liability loves that stuff.
If you run a business, you need both unless you enjoy surprise bankruptcy. Think of them as peanut butter and jelly—great alone, but together they make a sandwich of financial safety.
The Bottom Line (In Three Sentences)
Workers’ comp covers inside people (employees). Liability covers outside people (customers, strangers, that one angry neighbor). Mixing them up is a comedy of errors—but not the funny kind.
So next time someone says, “Aren’t they the same?” You can wink and say, “Nope. But if you’re confused, just remember: workers’ comp is for the crew, liability is for the public. And always, always buy both before your cat trips the mailman.”