
How Much Does Insurance Go Up After A Ticket

So, you got a ticket. Ouch. We’ve all been there—cursing that speed trap or that “no right on red” sign you swear you didn’t see. Now comes the real question: How much does insurance go up after a ticket? Get ready. It’s a wild ride.
The Magic Number (It’s Not That Magic)
On average, your premium jumps about 20% to 30% after a single moving violation. That’s like paying for a fancy dinner every month—except the dinner is just your old car insurance with a grumpy face on it. For some unlucky folks, it can spike 40% or more, depending on your state and driver profile. Oof.
But here’s the weird part: no two tickets are alike. A “rolling stop” at an empty intersection might sting less than a “10 over” on the highway. Insurance companies use this secret math—called actuarial science—that treats your ticket like a crime scene sketch. Every detail matters.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The Speeding Ticket Hall of Fame
Let’s break down the worst offenders. Reckless driving? That’s the villain. It can jack your rates up by 80% or more—basically doubling your monthly pain. A DUI? Oh, honey. That’s a financial tsunami. Expect a 150% to 300% increase, plus a side of shame and mandatory classes.
But a simple “speeding 5 over” is more like a polite tap on the shoulder. Most insurers barely blink—maybe a 10% to 15% bump. Still annoying, but not a catastrophe. Think of it as a “fee for being slightly impatient.”
Why Your Ticket’s Secret Life Matters
Here’s a quirky fact: insurance companies don’t just look at the ticket—they look at you. Your age, your car, your zip code. A 19-year-old with a lead foot in a sporty coupe? That’s a triple threat. Your rates might scream like a fire alarm. A 50-year-old in a minivan with a clean record? That ticket is more like a gentle whisper.
Even the color of your car can matter! (Okay, not really—but it sounds fun, right?) What actually matters is your driving history. One ticket every five years is a hiccup. Two tickets in a year? That’s a red flag parade. Insurers love stability. They hate surprises.
The Ghastly Timeline of Rate Hikes
How long does this penalty last? Usually three to five years. That’s longer than most reality TV shows, but not forever. Some states are nicer than others. For example, California and Michigan have laws that cap rate increases for minor violations. Lucky ducks. Other places, like New York or Texas, let insurers go wild.
Fun fact: If you get a ticket in a state that’s not your own, your home insurer still finds out. They have a creepy database called CLUE (Comprehensive Loss Underwriting Exchange). Yes, it’s really called that. And no, it’s not a board game—it’s a tattletale.
Can You Cheat the System? (Sort Of)
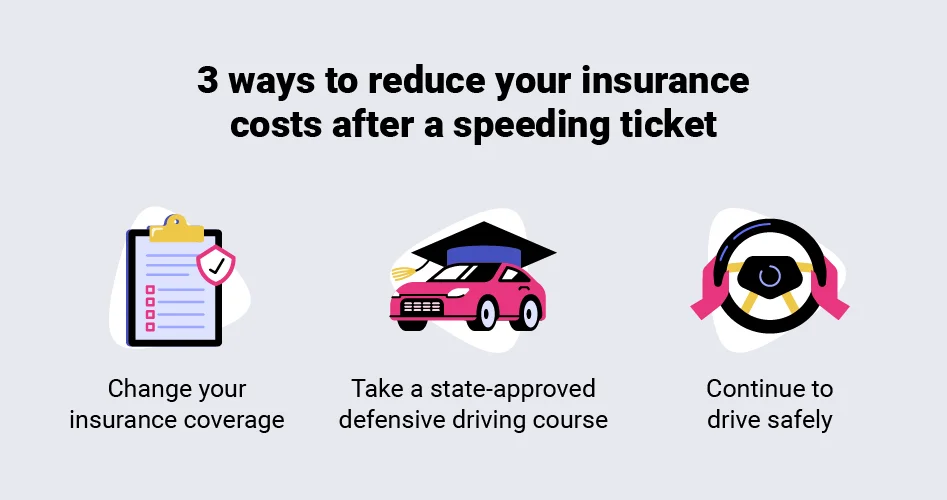
You’ve got options, and they’re actually fun to explore. First, fight the ticket. Hire a traffic lawyer. They’re like ninjas for your wallet. Often, they can get the ticket reduced to a “non-moving violation” (like a parking ticket), which has zero impact on insurance. You pay the lawyer, but you save hundreds in rate hikes. Sweet deal.
Second, take a defensive driving course. Many insurers give a 5% to 10% discount just for being a nerd about safety. It’s an hour of your life for a year of savings. Plus, you get to brag about your new “advanced driving” skills. “I can parallel park with my eyes closed!” (Please don’t.)
Third, shop around. Your current insurer might punish you, but a competitor might not care. Comparison sites exist for this very reason. It’s like dating—sometimes you just need a fresh start.

The Funniest Ticket Stories (Don’t Try This)
Here’s a gem: One guy got a ticket for driving too slowly in the left lane while eating a bowl of cereal. Yes, cereal. The cop wrote him up for “impeding traffic” and “open container of milk.” His insurance went up 25%. Don’t be that guy.
Another woman got a ticket for honking at a parade. She was happy. The cop was not. That counted as a “noise violation” on her record, and her rates went up 12%. Honk responsibly, people.
The Bottom Line: Relax, It’s Just Money
Look, a ticket stinks. But it’s not the end of the world. Most people see a temporary bump, then rates creep back down after a year or two of clean driving. The key is don’t panic. You’re still a good driver—just a slightly faster one.
And remember: insurance companies are just math nerds in suits. They calculate risk based on piles of data, not personal grudges. Your ticket is a data point, not a life sentence. So pay the fine, take the class, and keep your eyes on the road. Your wallet will thank you.
Now go drive safe—and maybe at least 3 mph under the limit, just to be extra annoying to the insurance gods.