
How Much Equity Needed For Reverse Mortgage
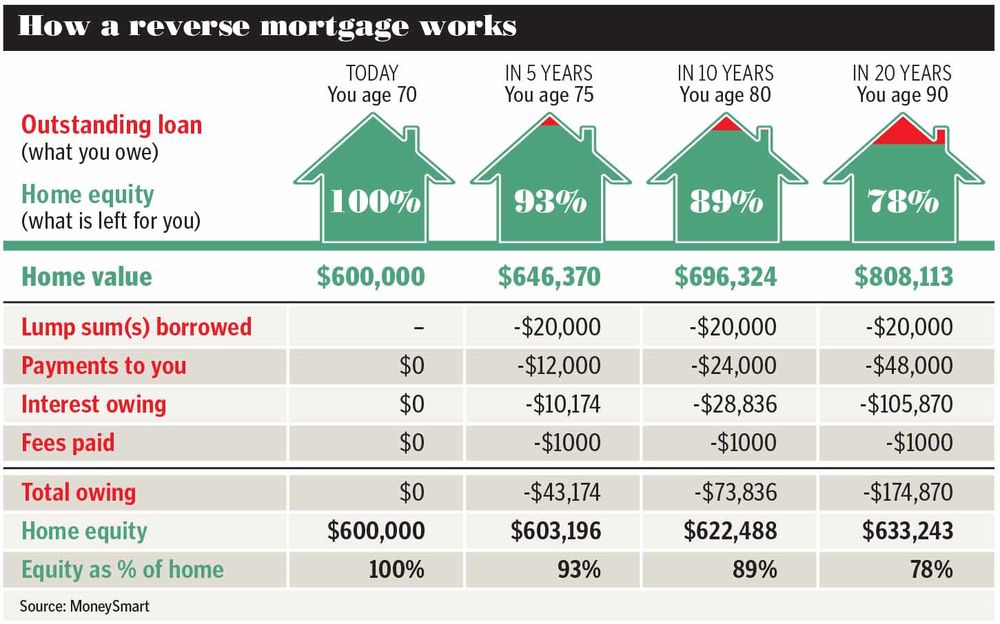
So, you’ve heard the term “reverse mortgage” floating around, and now you’re wondering: how much equity do I actually need to get one? Grab your coffee, because we’re about to untangle this little financial riddle together. And yes, I promise to keep the jargon to a minimum—no boring lectures here.
The Short Answer (Before We Get Fancy)
The magic number is usually 50% or more of your home’s value in equity. But wait—that’s not the whole story. The government (via the FHA) actually wants you to have at least 50% equity to qualify for a Home Equity Conversion Mortgage (HECM), which is the most common type.
Why 50%? Because lenders aren’t in the business of gambling. They need to be sure there’s enough cushion to cover your loan, interest, and fees. Think of it like this: if your house is a pizza, you need to own at least half the slices before you can trade them for cash.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
But here’s the kicker: more equity is even better. The more you own, the more cash you can pull out. It’s like having a bigger pizza—more slices to munch on.
Wait, What If I Own My House Free and Clear?
Oh, you lucky duck. If you have 100% equity (no mortgage left), you’re in the sweet spot. You can qualify for the maximum loan amount based on your age, interest rates, and home value. Imagine walking into a bank and saying, “I own this house outright,” and them basically handing you a check. That’s the dream, right?
But even with 100% equity, you won’t get 100% of your home’s value. The lender holds back a chunk for insurance and fees. It’s like getting a really good deal on a sale, but not a free lunch. Still, you’ll get a hefty lump sum or line of credit.
Pro tip: If you’re over 62 and own your home free and clear, you’re the reverse mortgage industry’s favorite customer. They’ll send you postcards. Probably.
What About That 50% Rule? Let’s Look Closer
Okay, so you only have 55% equity. Can you still play? Yes, but with limits. You might qualify, but the amount you can borrow will be smaller. Think of it as a “starter pack” reverse mortgage.
Here’s the annoying part: your age matters. The older you are, the more you can borrow, even with the same amount of equity. Why? Because life expectancy (sorry, not sorry) means the lender expects to pay you for fewer years. If you’re 73, you get more cash than if you’re 62—even if you both own 60% of the house.

And don’t forget the home’s value. A $200,000 house with 50% equity is different from a $500,000 house with 50% equity. The latter gives you a bigger check. It’s math, but not the scary kind.
So, How Do I Calculate My Exact Number?
You don’t. Please don’t try to do this in your head. Lenders use a formula called the “principal limit factor,” which is about as fun as it sounds. It takes your age, interest rates, and home value and spits out a number. Think of it as a secret recipe that only banks and calculators know.
But here’s a rough rule of thumb: if you have 50% equity at age 62, you might get 30-40% of your home’s value in actual cash. At age 70 with 50% equity, that might jump to 50-60%. See? Age is on your side—for once!
And if you have less than 50% equity, you’re likely out of luck. Sorry, but you can’t reverse mortgage a house you barely own. That’s like asking to borrow a car you only bought the tires for.
The Hidden “Gotcha” You Need to Know
Even if you qualify with 50% equity, you still have to pay off any existing mortgage with the reverse mortgage proceeds first. So if you owe $80,000 on a $200,000 house (60% equity), that $80k gets paid off. The rest—about $40k—is yours (minus fees).
Yes, fees exist. There’s an upfront mortgage insurance premium (2% of the home’s value), origination fees, and closing costs. Poof—$10k to $15k can vanish quickly. But you don’t pay it out of pocket; it’s rolled into the loan. So your equity gets a little haircut.
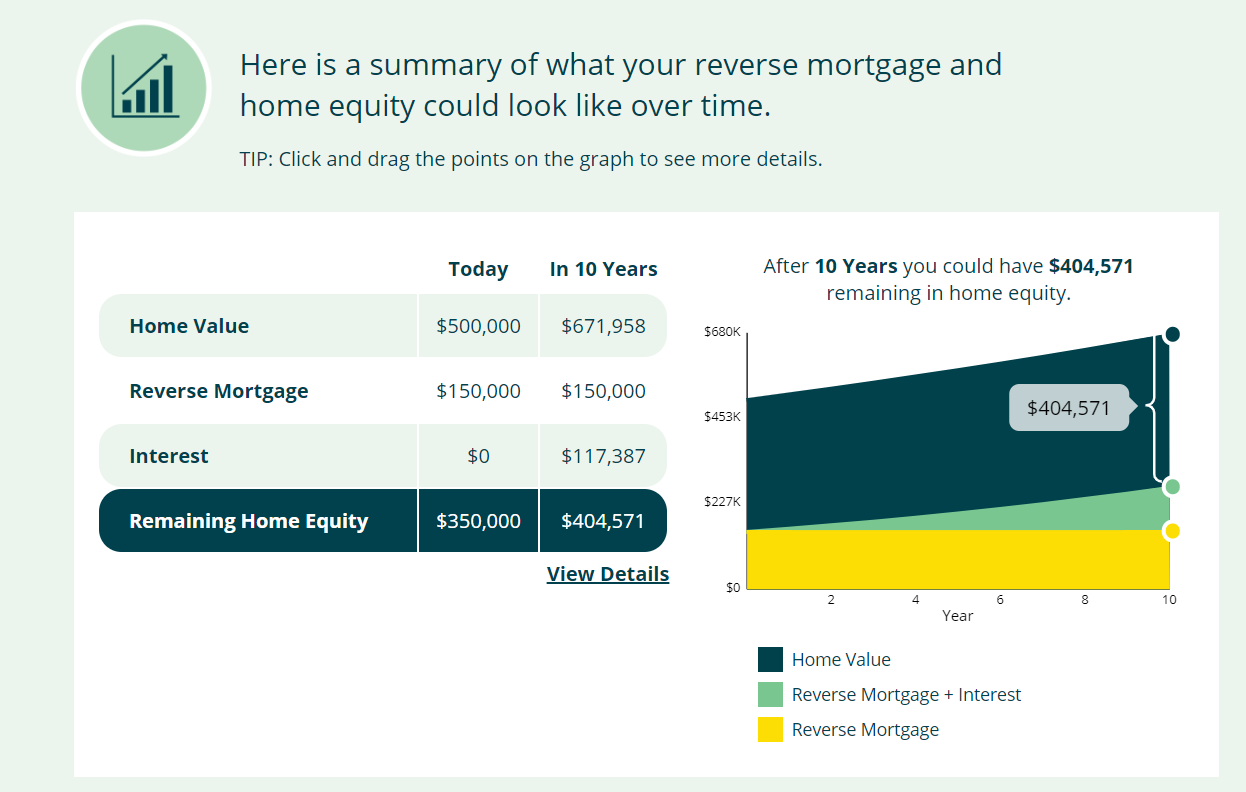
Translation: you need a bit more than 50% equity to walk away with meaningful cash. Aim for 60-70% equity to make it worth your while. Your future self will thank you.
What If I’m Not 62 Yet? (Or, “Why Am I Reading This?”)
If you’re under 62, stop right there. The government says you must be at least 62 to get a reverse mortgage. No exceptions. It’s like a nightclub for retirees—no ID, no entry.
But cheer up! You can still build equity while you wait. Pay down your mortgage, don’t take out new loans on the house, and watch your home value grow. By the time you hit 62, you’ll have a nice fat equity cushion.
And if you’re already 62+ but have less than 50% equity? Talk to a counselor (yes, HUD requires it). They might suggest a “HECM for purchase” or just tell you to pay down your mortgage first. Either way, don’t panic.
The Bottom Line (Because We All Love Bottom Lines)
You typically need 50% equity or more to qualify for a reverse mortgage. More is better, age helps, and fees will nibble away at your pile. If you own your house free and clear, you’re golden.
Still confused? That’s okay. This isn’t everyday stuff. Talk to a lender (or three) and a HUD-approved counselor. They’ll crunch the numbers for you—no coffee required, but it helps.
Now, go drink your coffee. And remember: reverse mortgages aren’t free money, but they can be a handy tool if you’ve got the equity. Just don’t let the fine print bite you in the you-know-what.