
Low Insurance Cars For New Drivers
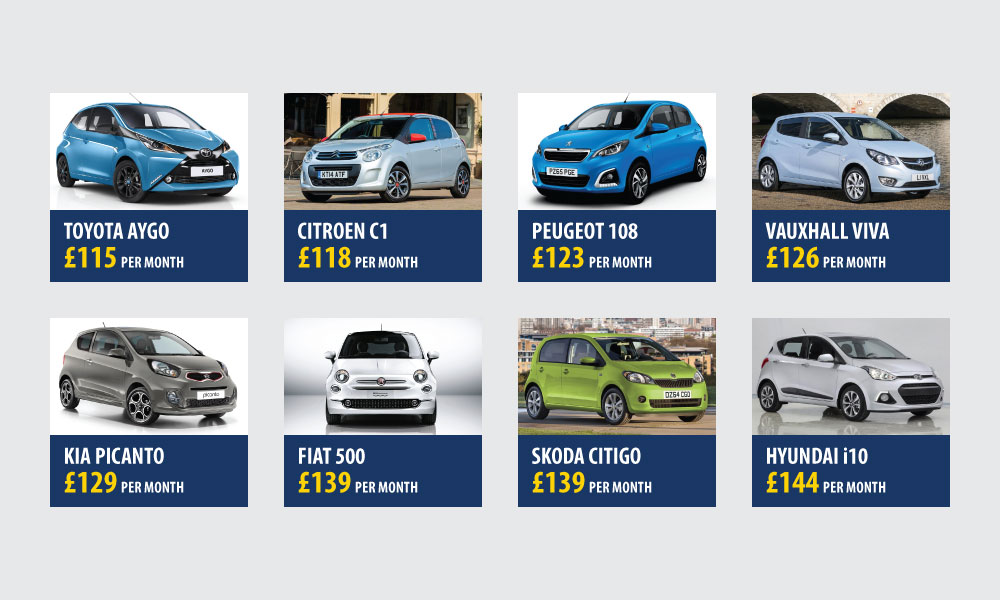
So, you just got your license. Congrats! The open road awaits, but first… insurance. Ugh, right? That part where you basically have to pay a second mortgage just to breathe near a car.
Let’s be real: being a new driver is expensive. Your premium is basically screaming “I’m a risk!” from the rooftops. And it’s not wrong. But we can game the system a little. We just need to find the right car.
Here’s the secret nobody tells you: insurance companies love boring cars. No, really. They do. The more boring a car looks, the cheaper it is to insure. It’s like a secret handshake for your wallet.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Why your dream car is a nightmare (for your bank account)
You want a sick sports car? A zippy little coupe? Yeah, stop right there. That shiny Mustang or used BMW? It’s begging for a speeding ticket. Insurance knows this.
They look at that car and see “jackrabbit starts” and “high repair costs.” And you see a premium that costs more than the car itself. Let’s avoid that, shall we?
The mortal enemies of cheap insurance: speed and flash.
Here’s what to never buy: anything turbocharged, anything with two doors, and anything German luxury. I’m sorry, Audi fans. Your four rings cost four figures to insure for a newbie.
Also, avoid the “boy racer” hatchbacks. Think Subaru WRX or a hot VW Golf. They’re fun, sure. But your insurance agent will laugh at you. Out loud. Into the phone.
Instead, you want a car that says: “I drive to the grocery store at exactly 35 mph. I enjoy NPR.” It’s not sexy. It’s smart.
The holy grail: low insurance cars for new drivers
Let’s get specific. You want a car that’s cheap to repair, slow, and safe. It should be as exciting as watching paint dry. Here’s your shortlist.
First up: Honda Civic (base model, no spoilers). I know, it’s the “boring choice.” But it’s also the best choice. Parts are everywhere, and thieves don’t want it.
Next: Toyota Corolla. This car is invincible. It will outlast your will to live, and it costs peanuts to insure. It’s the sweatpants of the car world. Comfortable, reliable, and nobody judges you.
Then we have Mazda3 (think 2015 or older). It’s a little more fun to drive than the others, but still cheap. It’s the “cool boring” car. Like wearing a plain t-shirt but with nice shoes.
Don’t forget the hatchbacks (the safe ones).
A Kia Rio or Hyundai Accent are tiny little boxes. They’re about as exciting as a microwave. But you’ll pay less for insurance than you do for Netflix. It’s a trade-off.
Also consider a Subaru Outback (if you need space). It’s the official car of “I have a dog and hike occasionally.” It’s slow. It’s safe. And insurance companies adore them.
One weird trick: buy used, not new
Here’s a curveball. A brand new car? Higher insurance. Always. A car that’s five or six years old? Way cheaper. The value is lower, so the payout is lower. That’s good for you.
But don’t buy anything flashy even used. No convertibles. No “special edition” nonsense. Insurance doesn’t care about your style. It cares about statistics. You are a statistic.
Let’s flip the script. Think of it this way: you’re not buying a car. You’re buying a low insurance premium that happens to come with wheels. It’s a mindset shift.
Avoid these like the plague.
Have you heard of a Ford Mustang? Avoid. A Nissan 370Z? Run. Any Jeep Wrangler? Oh, honey. No. Those are theft magnets and rollover risks. Your premium will be a nightmare.
Also stay away from Minivans. Yes, they’re boring. But they’re also expensive to insure because they carry kids. You’re a new driver. You don’t need a rolling daycare.

And for the love of all that is holy, don’t buy a Tesla. I don’t care if your uncle gives you a deal. The repair costs are absurd. Your insurance will be higher than your car payment. Hard pass.
The boring-car paradox
Here’s the funny thing. Once you buy a cheap insurance car, you’ll actually enjoy it. It’s stress-free. You don’t freak out about door dings. You don’t care if you spill coffee.
You’ll have extra cash for actual fun things. Like gas. Or snacks. Or that noise box you call a stereo. And after a year or two of clean driving, your rates drop. Then you can get the cooler car. But wait.
“But what if I hate the car?” you ask. Good question! You might. But you’ll hate paying $400 a month for insurance more. Trust me. I’ve seen it.
Final word (before I let you go)
Look, I get it. You want to make a statement. A car is an extension of your personality. But right now, your personality should say: “I am a responsible adult who doesn’t crash.”
Get a Corolla. Get a Civic. Get a Mazda3. Drive it like a grandma for two years. Then upgrade. It’s like a video game where you grind levels before fighting the boss. This is the grinding phase.
And hey, if your friends laugh at you for driving a “grandpa car”? Let them laugh. You’ll be laughing all the way to the bank. While they’re crying over their insurance bill. You’re welcome.
Now go find your boring chariot. And please, drive safe. I need you alive to use my insurance advice later.