
Is The Tax Free Allowance Going Up
Alright, grab your coffee and a slightly stale biscuit, because we need to talk about something that affects every single one of us: the tax-free allowance. You know, that magical number that decides whether you get to keep your money or if HMRC gets to buy a new fountain pen with it. The big question on everyone’s lips is: is it going up?
Let’s be honest, the current personal allowance feels a bit like a toddler’s bedtime—it hasn’t changed in forever, and we’re all just pretending it’s fine. For the tax year 2024/25, it’s stuck at £12,570. That’s the amount you can earn before the taxman starts tapping his foot impatiently. But with inflation eating your lunch like a hungry hippo, that number feels smaller every day.
The Political Ping-Pong Match
Now, every time a budget looms, rumors start flying like confetti at a wedding. “The allowance is going up!” shouts one politician. “We’re freezing it forever!” whispers the Treasury. It’s like watching a tennis match where the ball is your paycheck. The current government has actually frozen the allowance until April 2028, which is a fancy way of saying “you’ll be paying more tax as your wages grow.”
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Think about that: if you get a 3% pay rise, you don’t suddenly feel richer. You just move closer to the taxman’s new go-kart fund. It’s called fiscal drag, which sounds like a really bad club in Ibiza but is actually just a sneaky way to tax more people without anyone noticing. Surprising fact: in 1990, the tax-free allowance was just £3,005. That’s less than a used car from that era!
The Great British Tea Break Debate
So, will it go up? Honestly, it’s about as likely as finding a parking spot in central London on a Saturday. The Chancellor keeps hinting at “difficult decisions,” which is code for “we’re keeping your cash.” But wait—there’s always a twist. In the spring budget, the government sometimes tweaks the allowance for pensioners or low earners, like adding a tiny sprinkle of sugar to a bitter tea.
Here’s the kicker: if the allowance did rise to £14,000, you’d save about £286 a year. That’s enough for a nice dinner out—or four trips to the dentist, depending on your luck. But don’t hold your breath. The freeze is already pulling almost £40 billion extra from our wallets by 2027-28. That’s enough money to buy every single person in the UK a solid gold kazoo.
What You Can Actually Do (Besides Crying into Your Cereal)
First, don’t panic. The allowance isn’t going up, but clever tricks exist. Use your tax-free savings accounts (ISAs) like a secret stash under the mattress—but legal. You can save up to £20,000 a year in an ISA, and the taxman can’t touch a penny. Surprising fact: 39% of UK adults don’t use their full ISA allowance. That’s like leaving a free slice of pizza on the table.
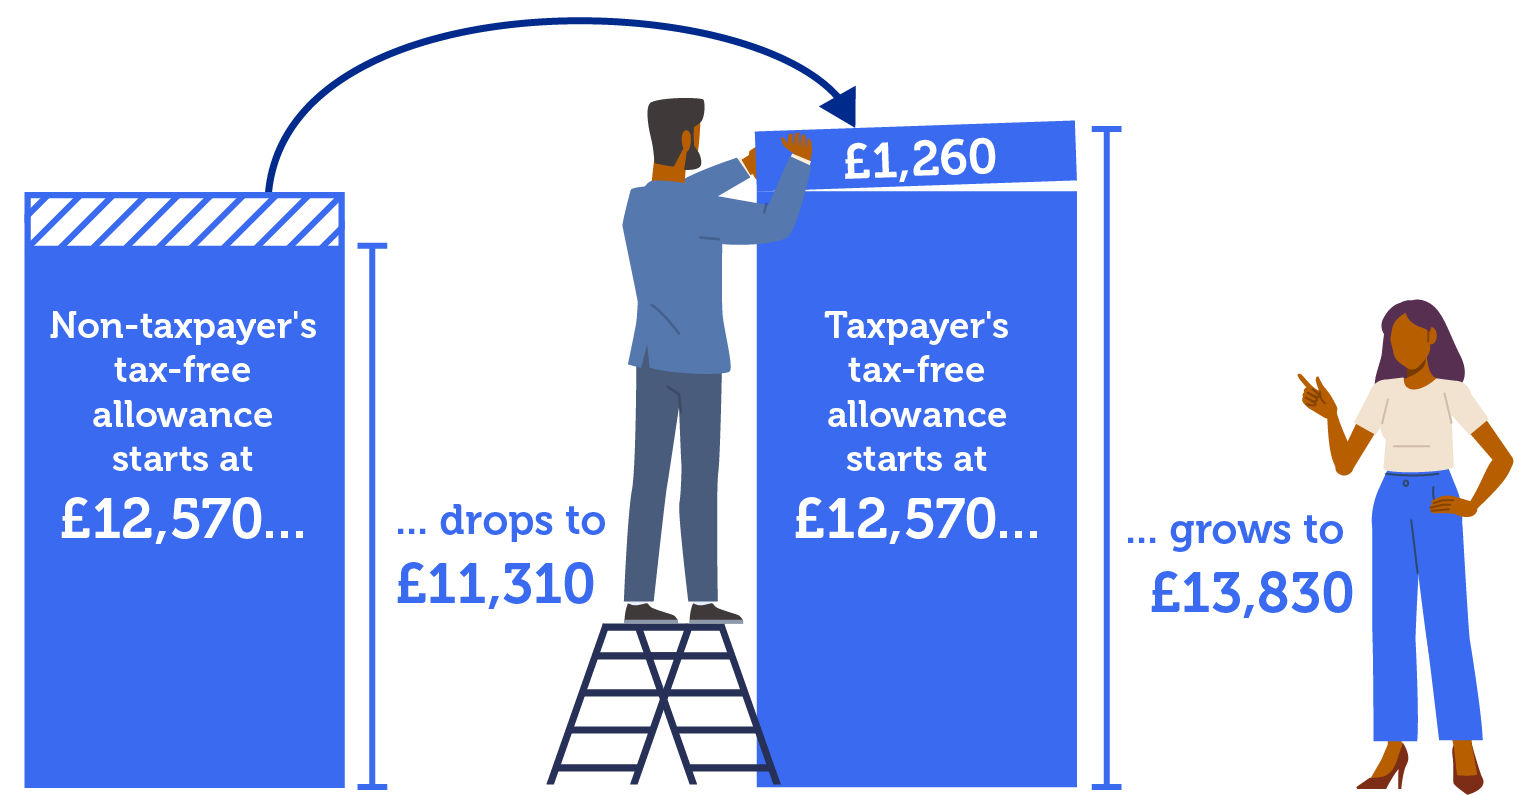
Second, check if you’re eligible for the Marriage Allowance. If you’re married or in a civil partnership, and one partner earns less than the personal allowance, you can transfer £1,260 of their allowance to the higher earner. That saves you up to £252 a year. It’s not a lottery win, but it’ll buy you a very nice cheese platter.

The Bottom Line (and It’s a Bit Wobbly)
Let’s be real: the tax-free allowance going up is like waiting for a bus in the rain—it might eventually show up, but probably later than you’d like. The government has made it clear: they need the cash. So while you’re dreaming of a raise that keeps all your money in your pocket, remember that the frozen allowance is here to stay for a few more years.
But hey, here’s a joke to lighten the mood: Why did the tax accountant break up with the calculator? Because it couldn’t count on future allowances. Sorry, that was terrible. But at least you’re not paying tax on your sense of humor—yet.
In the meantime, stay smart, save where you can, and whisper a quiet thank you to your 1990s self who only paid tax on £3,000. Times have changed, but your ability to complain about it remains legendary. Cheers to that.