
Best Time For Car Insurance Quotes
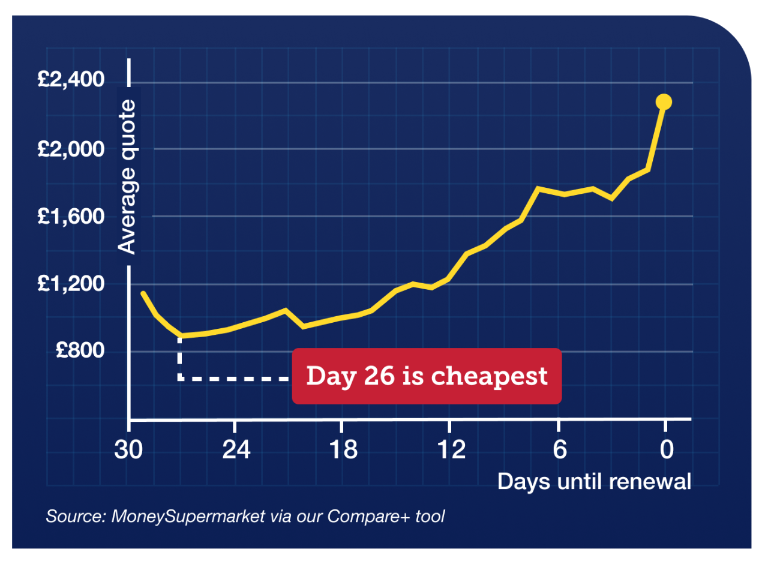
Let’s be honest: shopping for car insurance usually ranks somewhere between folding fitted sheets and updating your LinkedIn profile on the fun scale. But what if we told you the timing of your quote hunt could be your secret weapon? Finding the best rate isn’t just about your driving record; it’s about knowing when the insurance gods are most likely to smile upon you.
The Calendar is Your Co-Pilot
Think of the insurance market like a farmers’ market—prices fluctuate with the season. The single best time to get a quote is generally one to three weeks before your policy expires. Insurers love proactive shoppers and often reserve their best introductory rates for those who aren’t scrambling at the last minute.
Don’t wait until the 11th hour. Getting a quote on the exact day your policy ends is like showing up to a Black Friday sale at 5 PM—the good stuff is gone, and you’re left with overpriced impulse buys. Give yourself a cushion so you can compare without the panic sweats.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The Monthly Sweet Spot
Here’s a fun fact that sounds like a Wall Street secret: Tuesdays and Wednesdays are statistically the quietest days for insurance inquiries. Less demand means you get a calmer, more representative quote without the weekend warrior surcharge baked in.
Also, aim for the mid-month window. Most people shop for insurance during the first week of the month (when bills are due) or the last week (before the next payment cycle). You want to be the cool, calm shopper in the middle, not part of the frantic crowd.
The Cultural Calendar Counts
Ever notice how everything gets more expensive right before a holiday? The same logic applies to insurance. Avoid quoting during major holidays like Thanksgiving, Christmas, or the Fourth of July. Insurers often run limited-time promos, but the base algorithms can be skewed by seasonal driver data.
Think of these times as “rush hour” for the industry. Instead, treat yourself to a quote-hunting session on a rainy Sunday afternoon in February. It’s low season, you’re already cozy, and you’ll get a rate that reflects your actual risk—not your desperation to buy before New Year’s.
Your Life Timeline Matters More
While calendar dates help, the real best time is when your life changes. Got married? Moved to a new zip code? Turned 25? These are golden opportunities. Insurers love stability, and a new marriage or a safer neighborhood can drop your rate faster than you can say “rice cake.”

Pro tip: If you’ve recently paid off a car loan, get a quote immediately. Full-coverage requirements evaporate, and you can switch to liability-only—a move that feels like finding a $20 bill in last year’s coat. Don’t assume your current insurer will automatically adjust your rate; they’re not mind readers.
The Tech Trick: Set a Timer
Here’s where modern life meets old-school strategy: book a 15-minute window on your phone calendar. Treat it like a haircut appointment—non-negotiable but quick. The best time isn’t just a date; it’s a mental state where you’re not hungry, tired, or distracted by Netflix.
Fun fact: The average person saves 30% just by switching providers, but most people only compare prices every 4-6 years. That’s like never checking if your phone plan got better. Set a recurring reminder every six months to do a five-minute check. Small habit, huge payoff.
The “Reverse” Halloween Strategy
Insurers often release their best new customer rates in the fall (September to November). Why? Because they’re gearing up for the winter driving season and want to lock in safe drivers. It’s the insurance equivalent of back-to-school sales—everyone’s trying to look good on paper.
Meanwhile, spring is the least ideal time. That’s when accident rates spike thanks to rain, potholes, and drivers who forgot how to merge after winter. Insurers hike base rates in April like coffee shops hike prices during pumpkin spice season. Avoid it.

Your Algorithm, Your Rules
Remember: the worst time for a quote is when you’re angry or stressed. Never comparison-shop right after a fender bender or a bad breakup. Your brain will prioritize “cheap” over “smart,” and you’ll end up with a policy that covers less than a beach towel.
Instead, create a ritual. Brew a good cup of coffee, put on a playlist (lofi beats, not death metal), and open three tabs. Compare quotes from a national brand, a local broker, and an online-only company. It’s a 20-minute investment that could save you enough for a nice dinner out.
And here’s a wild statistic: your credit score can affect your car insurance rate by up to 60% in some states. So, before you even type in your ZIP code, check your credit report. A simple error removal might be the real time-saving hack you needed all along.
The Reflection: It’s Not Just About Money
At the end of the day, timing your insurance quote is about peace of mind. It’s less about gaming the system and more about aligning your busy life with a moment of clarity. You’re not just saving dollars; you’re saving the mental energy that comes from knowing you’re protected without overpaying.
So the next time you’re waiting for your coffee to brew or sitting in a parking lot, pull out your phone and grab a quote. The perfect moment isn’t some cosmic alignment—it’s whenever you decide that you deserve a better deal. Go ahead, roll down your window, take a deep breath, and click “get started.” The road ahead just got a little smoother.