
When Can You Withdraw Lifetime Isa
So, you’ve been diligently stashing cash into your Lifetime ISA—good for you! Maybe you’ve even started dreaming of that first home or a sun-drenched retirement. But let’s be real: the burning question is, when can you actually get your hands on that sweet, government-boosted money? Relax—we’re about to make this fun, not financial jargon hell.
The Golden Rule: The Perfect Timing
First things first: you can withdraw your Lifetime ISA penalty-free only under two very specific circumstances—and they’re both pretty awesome. The first is when you’re buying your first home (up to £450,000). The second is when you hit age 60, at which point the money is yours with no strings attached.
Think of it like a treasure chest that unlocks at two magical moments. You’re not just saving; you’re scheduling your future joy. And the best part? The government gives you a 25% bonus on every pound you put in—up to £1,000 a year. That’s free money, folks!
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
What About Emergencies? (The “Oops” Exception)
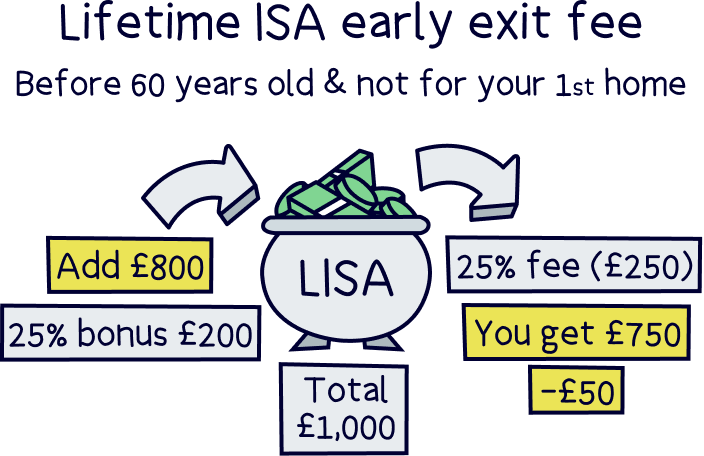
Life happens—maybe you need the cash for a medical bill, a job loss, or a spontaneous trip to the Maldives (hey, no judgment). If you withdraw for any reason other than a first home or age 60, you’ll lose the 25% bonus and pay a 25% penalty on the withdrawal amount. Ouch, right?
But here’s the twist: that penalty actually claws back a bit less than the bonus you received. You won’t lose your original deposit—just the extra interest. So, it’s not a total disaster, but it’s definitely a “think twice” moment. My advice? Treat your Lifetime ISA like a favourite new pair of jeans—you can’t just rip them open whenever you feel like it.

The Real Fun: Planning Your Life Hacks
Here’s where it gets exciting. You can withdraw your bonus money to buy your first home, which means you’ll dodge that awkward conversation with your parents about borrowing for a down payment. Or you can wait until 60 and use the pot for a dream retirement—maybe a camper van or a wine tour of Italy.
And because you can contribute up to £4,000 per year, each year is a mini celebration. You’re not just saving pennies—you’re stacking bricks of freedom. Imagine: every time you deposit, a little government elf adds £1,000 to your pile. Yes, that’s imaginary, but the math is real!
One More Thing: The “What If” Scenarios
What if you change your mind about buying a home? You can transfer your Lifetime ISA to a different provider without penalty. Just don’t withdraw the cash—move it directly between ISA accounts. This keeps your bonus intact and your future options wide open.
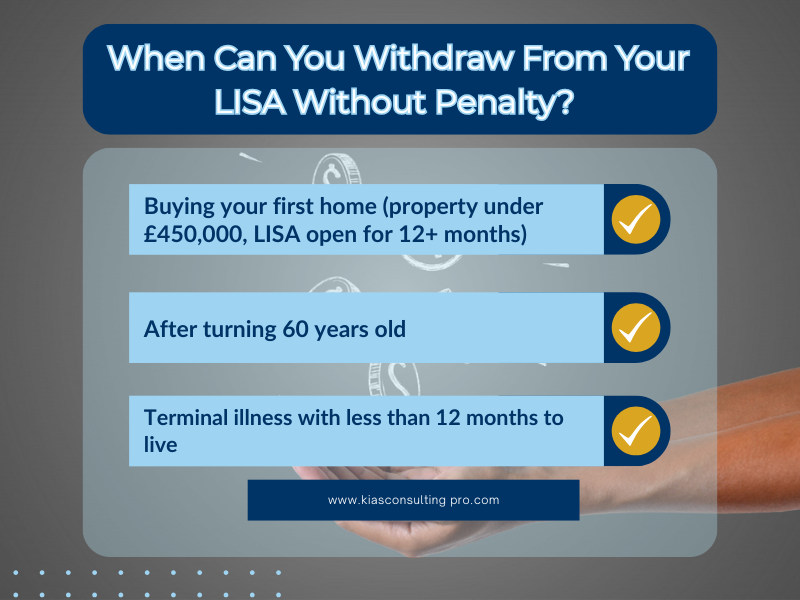
Also, you can’t withdraw for a second home or a holiday cottage. The rules are strict, but they exist to protect your bonus. Think of it as the government’s way of saying, “We trust you with this money, but please be wise.”
The Uplifting Note You’ve Been Waiting For
Here’s the beautiful truth: a Lifetime ISA isn’t just a savings account—it’s a promise you make to your future self. Every pound you put in whispers, “I’ve got your back, future me.” The government adds a bonus because they believe in you too. How cool is that?
So go ahead—open that account, max out your contributions, and dream big. Whether you’re buying your first place or sipping espresso in a beach hut at 65, that money will be there, waiting. You’ve already taken the first step by reading this. Now, take the next: explore more. Every financial journey starts with a single, joyful decision. Yours begins today.