
Cheapest Cars To Insure New Driver
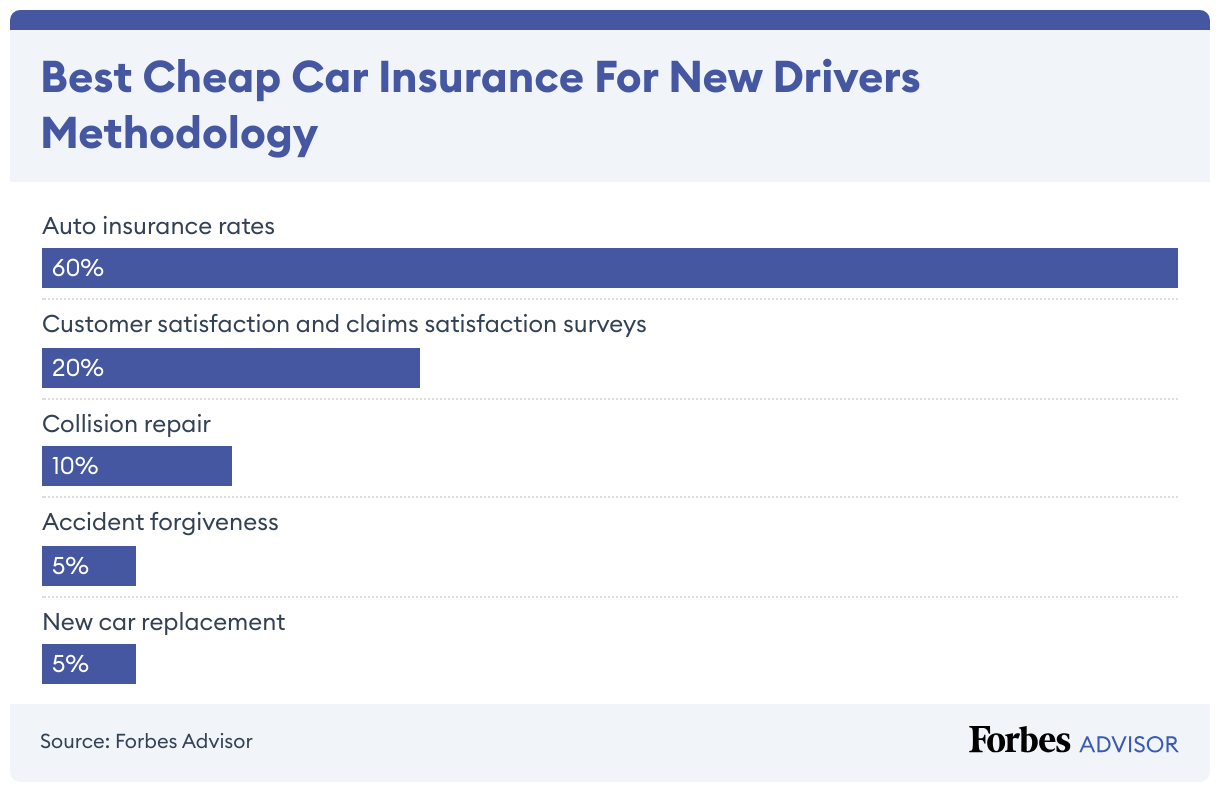
So, you’ve finally got your license. Congratulations! That feeling of freedom is like the first time you successfully parallel parked without sweating through your shirt. But then reality hits: insurance quotes that look like the national debt of a small country.
Don’t panic. I’ve been there, staring at my screen wondering if I should just stick to riding the bus with the friendly, but smelly, city pigeons. The good news? Some cars are basically insurance magnets for low rates. Let’s find you one.
Why your car choice matters more than your driving record (for now)
Insurance companies are a bit like that overly protective friend who judges your life choices. They don’t care that you just passed your test; they care about the car you’re driving. A flashy sports car screams "I will zoom and crash." A sensible hatchback whispers "I will drive to the grocery store and buy yogurt."
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Your premium is based on risk. New drivers are risky enough without adding a powerful engine to the mix. That’s why the cheapest cars to insure are usually the ones that are cheap to fix, hard to steal, and not very fast. It’s not sexy, but your wallet will love you.
The Usual Suspects: The "Boring" Heroes
Let’s talk about the Honda Fit. This little box on wheels is like the golden retriever of cars: loyal, unassuming, and everyone loves it. Parts are everywhere, and thieves would rather steal a bicycle. You can park it anywhere, and it’s so practical you can move a small sofa in it.
Then there’s the Mazda2 (if you can find one). Think of it as the quiet kid in class who actually gets good grades. It’s fun to drive without being dangerous, and it’s remarkably cheap to insure. It sips gas like a fine tea, not a thirsty elephant.
Don’t forget the Subaru Impreza. Yes, it has all-wheel drive, which sounds fancy. But because it’s not a WRX turbo rally beast, insurance companies treat it like a mild-mannered librarian. It’s safe, reliable, and perfect for rainy days or getting to your part-time job at the coffee shop.
The "Uncool" Cars That Save You Real Cash
I once laughed at my friend for buying a Kia Rio. It was beige. I called it “The Toaster.” But guess who was paying $80 a month for insurance while I was shelling out $200? The Toaster owner. That car was so unexciting that insurance agents probably yawned when typing it in.
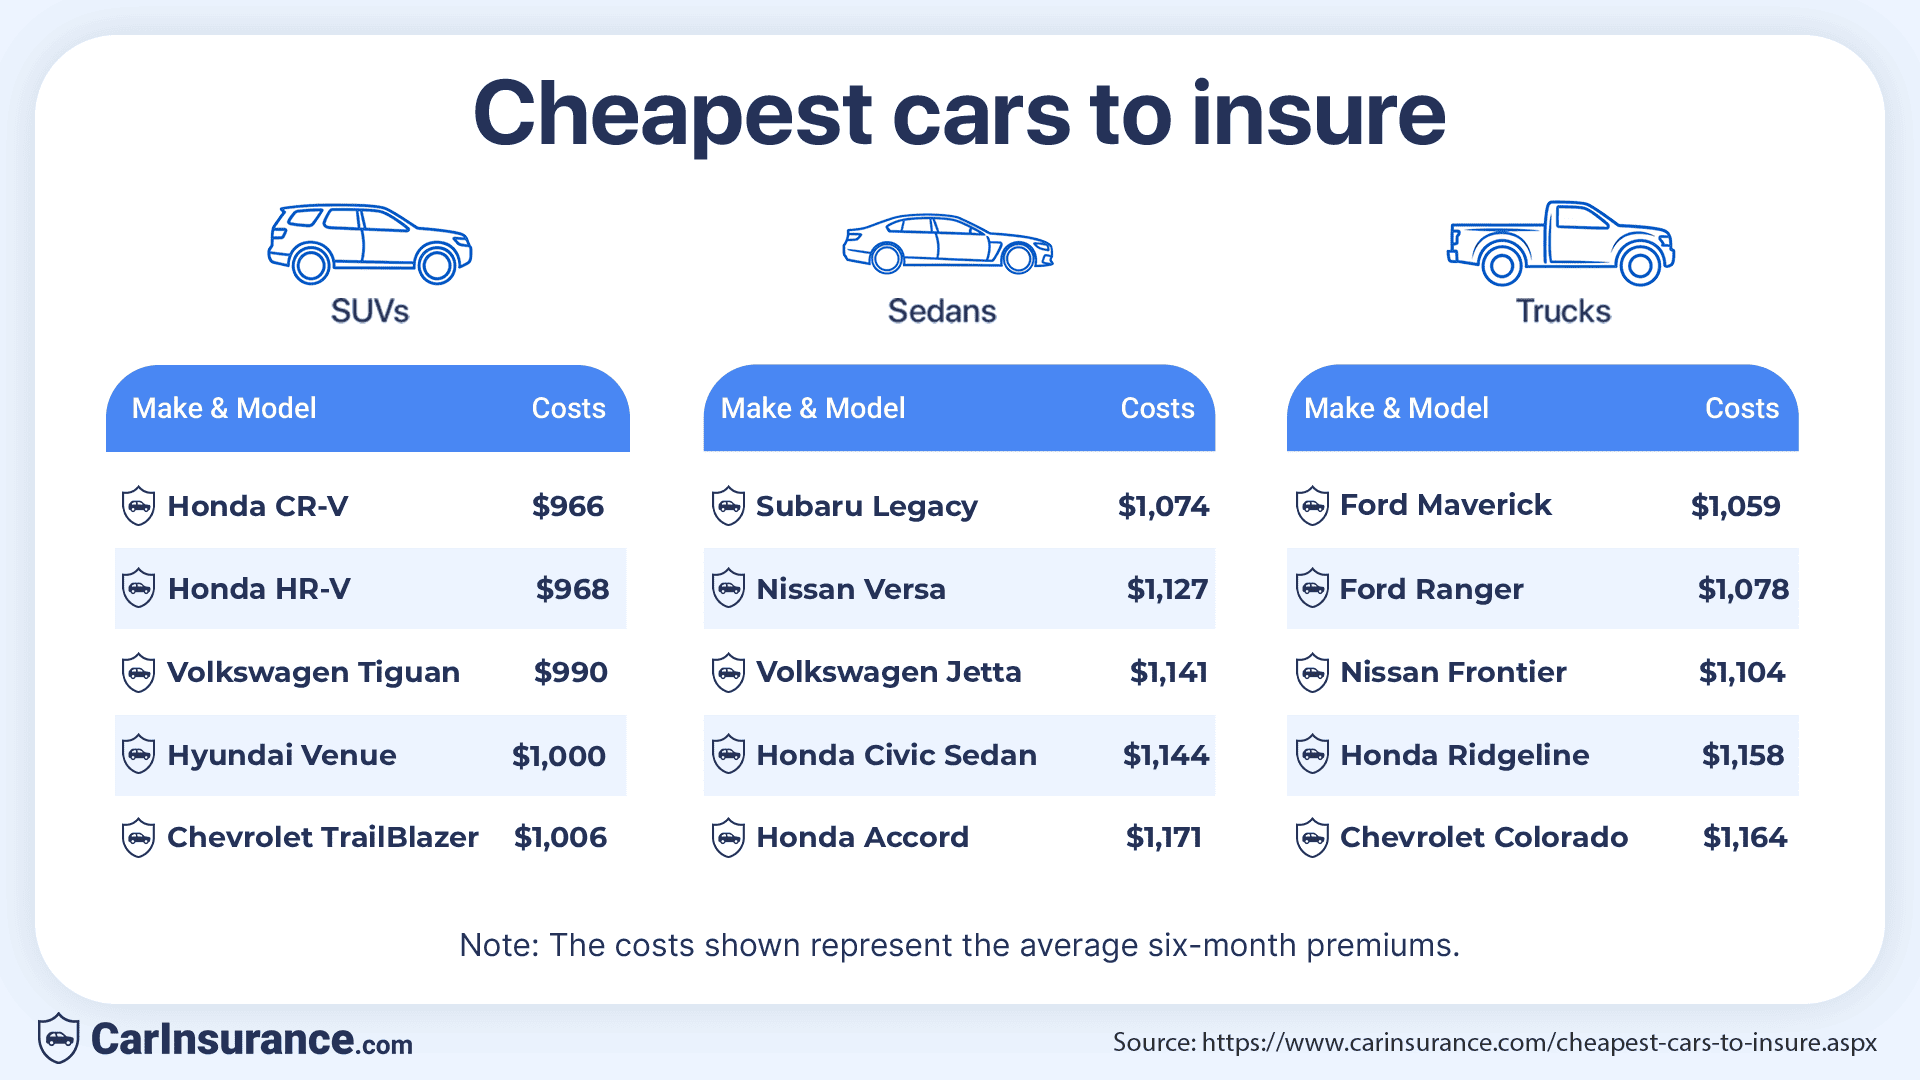
Similarly, the Hyundai Accent is a champion. It’s the car equivalent of a plain bagel with cream cheese. Nothing fancy, but it gets the job done and nobody gets hurt. It also comes with great warranties, which means if something breaks (unlikely), it’s fixed for free.
And let’s whisper the name of the Nissan Versa. It’s often the cheapest new car you can buy. Insuring it often feels like a rounding error on your rent. The interior is basic, but your bank account will do a happy dance every month.
What about the "Almost New" Secret?
Here’s a trick nobody tells you: a car that’s three to five years old is the sweet spot. It’s cheap to insure because it’s not carrying that brand-new car premium. For example, a 2019 Toyota Yaris might cost you less to insure than a brand-new one, but it still has modern safety features like backup cameras.
Safety features are like magic spells against high insurance rates. Automatic braking, lane-keeping assist, and airbags everywhere make insurers smile. They think: "Ah, this new driver might crash, but at least they’ll do it gently."
Real talk: How to actually lower the bill
Getting a cheap car is step one. Step two is being a smart teenager (or young adult). Take a defensive driving course. It’s an afternoon of learning how to avoid deer and idiots, and it knocks 10% off your rate. That’s like finding a $20 bill in an old coat.
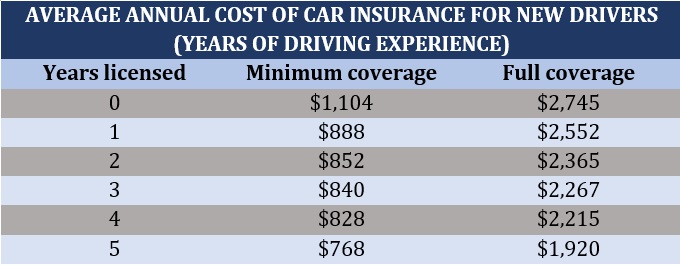
Also, get on your parent’s policy if you can. I know, it’s not cool. But adding a cheap car to an existing family policy is like splitting the check with a millionaire—you pay very little. And you can reclaim your independence by paying them the difference each month.
Finally, pay annually instead of monthly. I know, it hurts to drop a lump sum. But insurance companies charge a fee for the privilege of paying monthly. It’s like a "convenience tax" for not being rich. Save up, pay once, and watch the savings roll in.
The bottom line (with a smile)
Look, no new driver wants to drive a beige 2005 Honda Civic. It’s not a head-turner. But do you know what is a head-turner? A bank account that isn’t empty. Driving a boring, slow, cheap-to-insure car for a year or two is a rite of passage.
After your first accident-free year, your rates will drop. Then you can upgrade to something faster. But for now, embrace the sensible choice. You’ll have more money for pizza, movies, and gas. And trust me, that’s way cooler than a car you can’t afford to drive.
So go forth, find a used Toyota Yaris or a humble Kia Rio. Your insurance agent will high-five you. Your wallet will thank you. And your future, slightly wealthier self will look back and laugh at how smart you were.