
What Happens To Pension If You Die
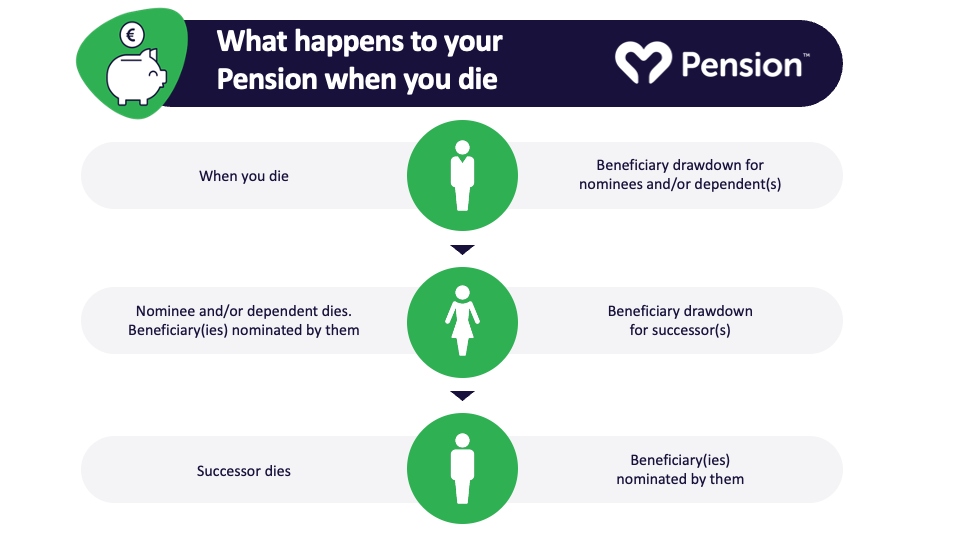
Alright, let’s talk about a morbidly fascinating topic: what happens to your pension if you kick the bucket? I know, I know—it’s not exactly dinner-table chat. But trust me, it’s way less grim than it sounds, and there’s even a little good news tucked in there.
First off, the answer isn’t one-size-fits-all. It depends on the type of pension you have and the choices you made while alive. Think of your pension like a pizza: you can order it with extra cheese (benefits for your spouse) or go plain (just for you).
The Two Main Types of Pensions
Defined Benefit Pensions (The “Old School” Kind)
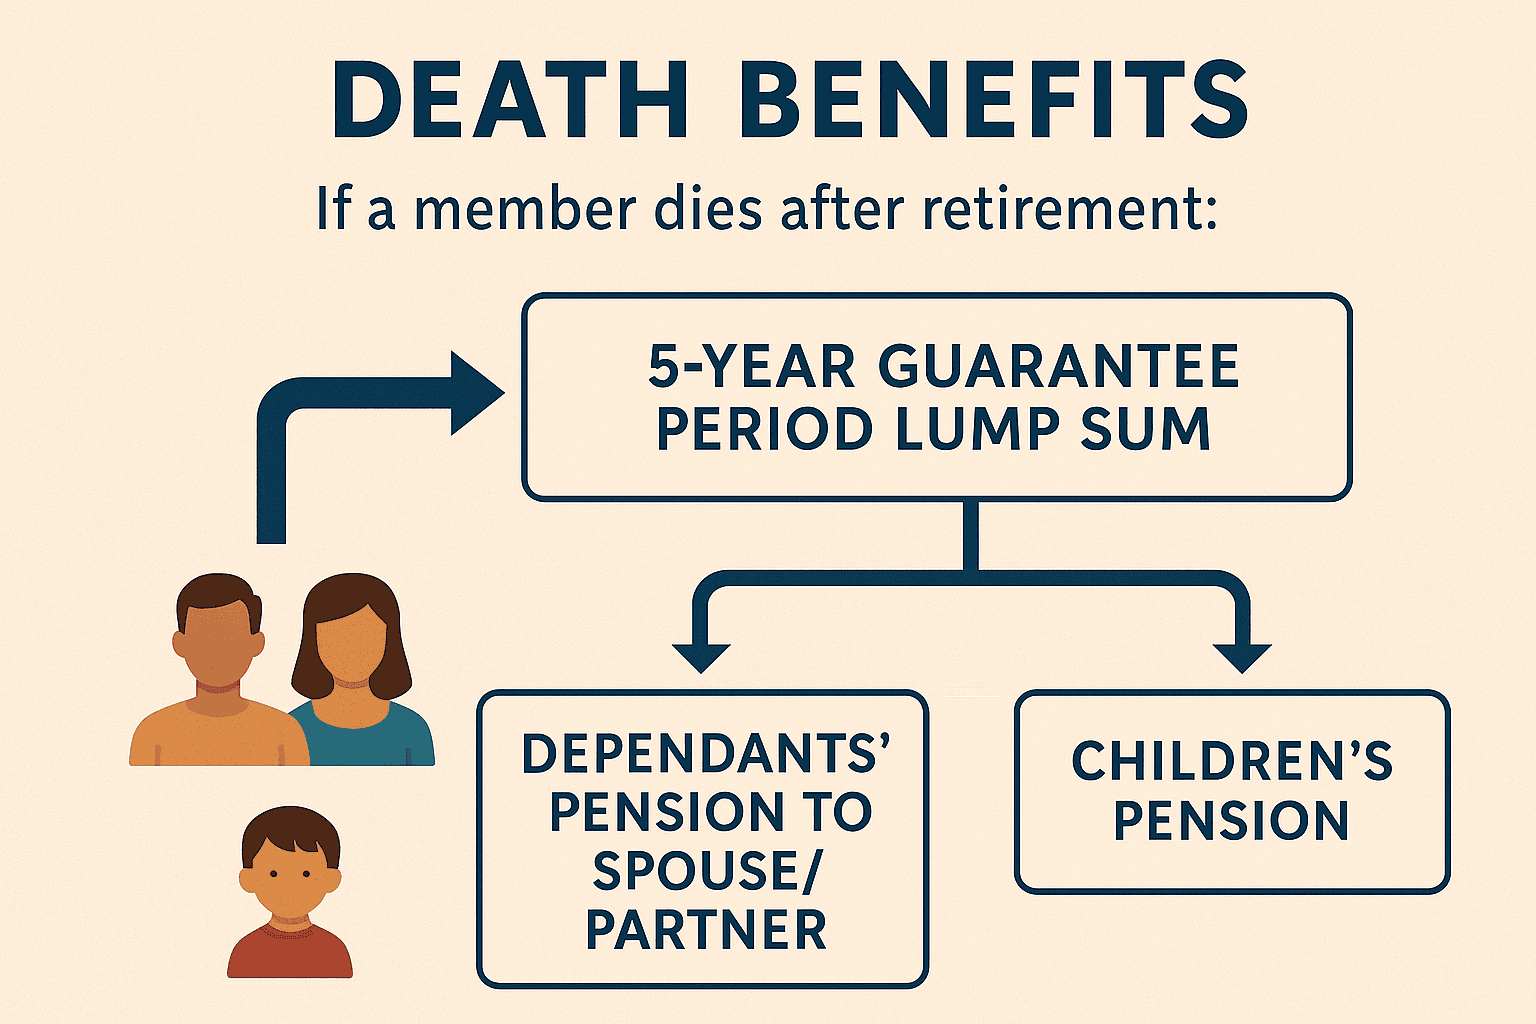
These are often called “final salary” pensions, and they’re like the luxury sedans of the retirement world. If you die before retirement, your spouse or dependents might get a lump sum or a reduced monthly payment. But—and this is a big, juicy “but”—it’s not automatic; you usually choose a “survivor benefit” option when you retire.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
If you picked the right option, your partner could get, say, 50% of your pension for life. If you didn’t? Poof. The money vanishes back into the pension fund like a ghost. Moral of the story: read the fine print before you kick the bucket.
Defined Contribution Pensions (The “DIY” Kind)
These are things like 401(k)s or personal pensions. Here, you’ve got a pot of money you’ve been building up, and it’s all yours. When you die, that pot doesn’t disappear—it goes to your beneficiary, usually your spouse or kids. No drama, no mystery.
And here’s the fun part: in many countries, that inheritance is tax-free if it goes to your spouse. Your partner gets a nice little financial hug from beyond the grave. Not bad, right?
What If You Die Before Retirement?
This is where it gets weirdly good. If you’re still working and die, many pensions pay out a lump sum equal to the value of your contributions. That money goes straight to your family. It’s like they’re sending a “sorry you’re gone” check in the mail.
Some employers even have a “death in service” benefit: they’ll pay out a few years’ salary, too. So if you were planning to die on the job (please don’t), your family might get a really nice bonus.
But What About the Government Pension?
Ah, the good ol’ state pension. Depending on where you live, your spouse might be able to inherit a portion of your payments. In the UK, for example, a widow might get a small percentage of their late partner’s state pension. In the US, Social Security has survivor benefits, too.
But here’s the kicker: if you’re single with no kids, your state pension usually disappears into the government’s wallet. It’s like you were paying into a club that closes when you leave. Party’s over, folks.
The Tax Man Cometh (But He’s Not That Scary)
Inherited pensions are generally not taxed as income—at least not right away. If your spouse gets your pension, they might pay some tax when they withdraw it, but it’s usually lower than you’d expect. For kids or other heirs? There could be a tax bill, but often it’s way smaller than the money itself.
And in some countries, like Australia, if you die after age 60, the whole thing is tax-free for your beneficiaries. Hello, tax-free granny’s bonus!
What Happens If You Forget to Name a Beneficiary?
Oh, this is the awkward part. If you didn’t fill out that little “beneficiary” form, your pension goes into probate. That’s a fancy legal word for “your family fights over money while lawyers get rich.” It can take months or years, and Uncle Sam might take a bite.
So, for the love of all that is holy, name a beneficiary. It takes five minutes, and it saves your loved ones from a headache the size of a pension fund.
A Few Surprises (The “Oh, Really?” Moments)
Did you know some pensions let you sell your death benefit? Yep, you can trade your survivor benefits for a bigger monthly payment while you’re alive. But if you die soon after, your spouse gets nothing. It’s a gamble, like betting on how many birthdays you’ll see.
Also, if you remarry after retirement, your ex might still be entitled to your pension. Sorry, new spouse—old love wins the pension lottery. That’s why you should always check your “pension nomine” rules with a fine-tooth comb.
How to Make Your Pension a Happy Ending
Here’s the uplifting part: with a little planning, your pension can be a gift that keeps giving. Talk to your partner, your financial advisor (or your cat—they’re good listeners), and choose options that protect the people you love. Name beneficiaries, pick survivor benefits wisely, and don’t be shy about updating your forms.
And remember: your pension isn’t just for you. It’s a little love letter you leave behind, saying, “I was prepared, and I wanted you to be okay.” That’s beautiful, honestly.
So, what happens to your pension if you die? It can become a lifeline for your family, a tax break for your spouse, or a mystery for the courts. The choice is yours—while you’re still breathing. And hey, if all else fails, you could always spend it all on a giant rubber duck before you go. Now that’s a legacy.