
When Does A Woman Get State Pension
So, you’re wondering when the state pension finally rolls in, right? It’s a bit like waiting for that last slice of pizza—you know it’s coming, but the timing can feel like a cosmic joke. Let’s untangle this together, no jargon, just the good stuff.
The Big Rule: It’s Not 60 or 65 Anymore
First, forget what your grandma told you about retiring at 60. The state pension age has been doing the cha-cha over the last decade. For women, it now depends on when you were born.
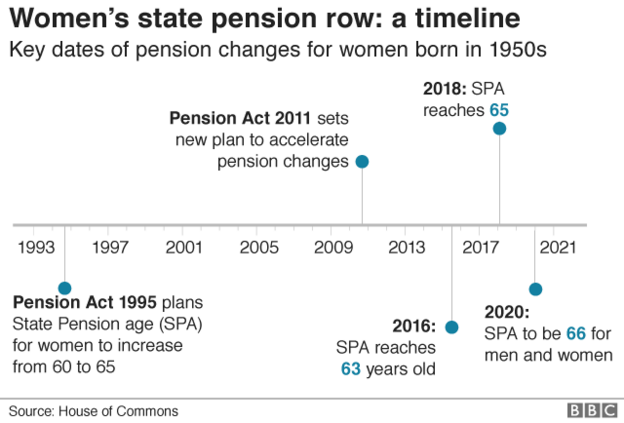
If you were born between 6 April 1950 and 5 April 1953, your state pension age was already 60 and 63-something. But if you’re younger than that, the goalposts moved—and they moved again in 2010 and 2018.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
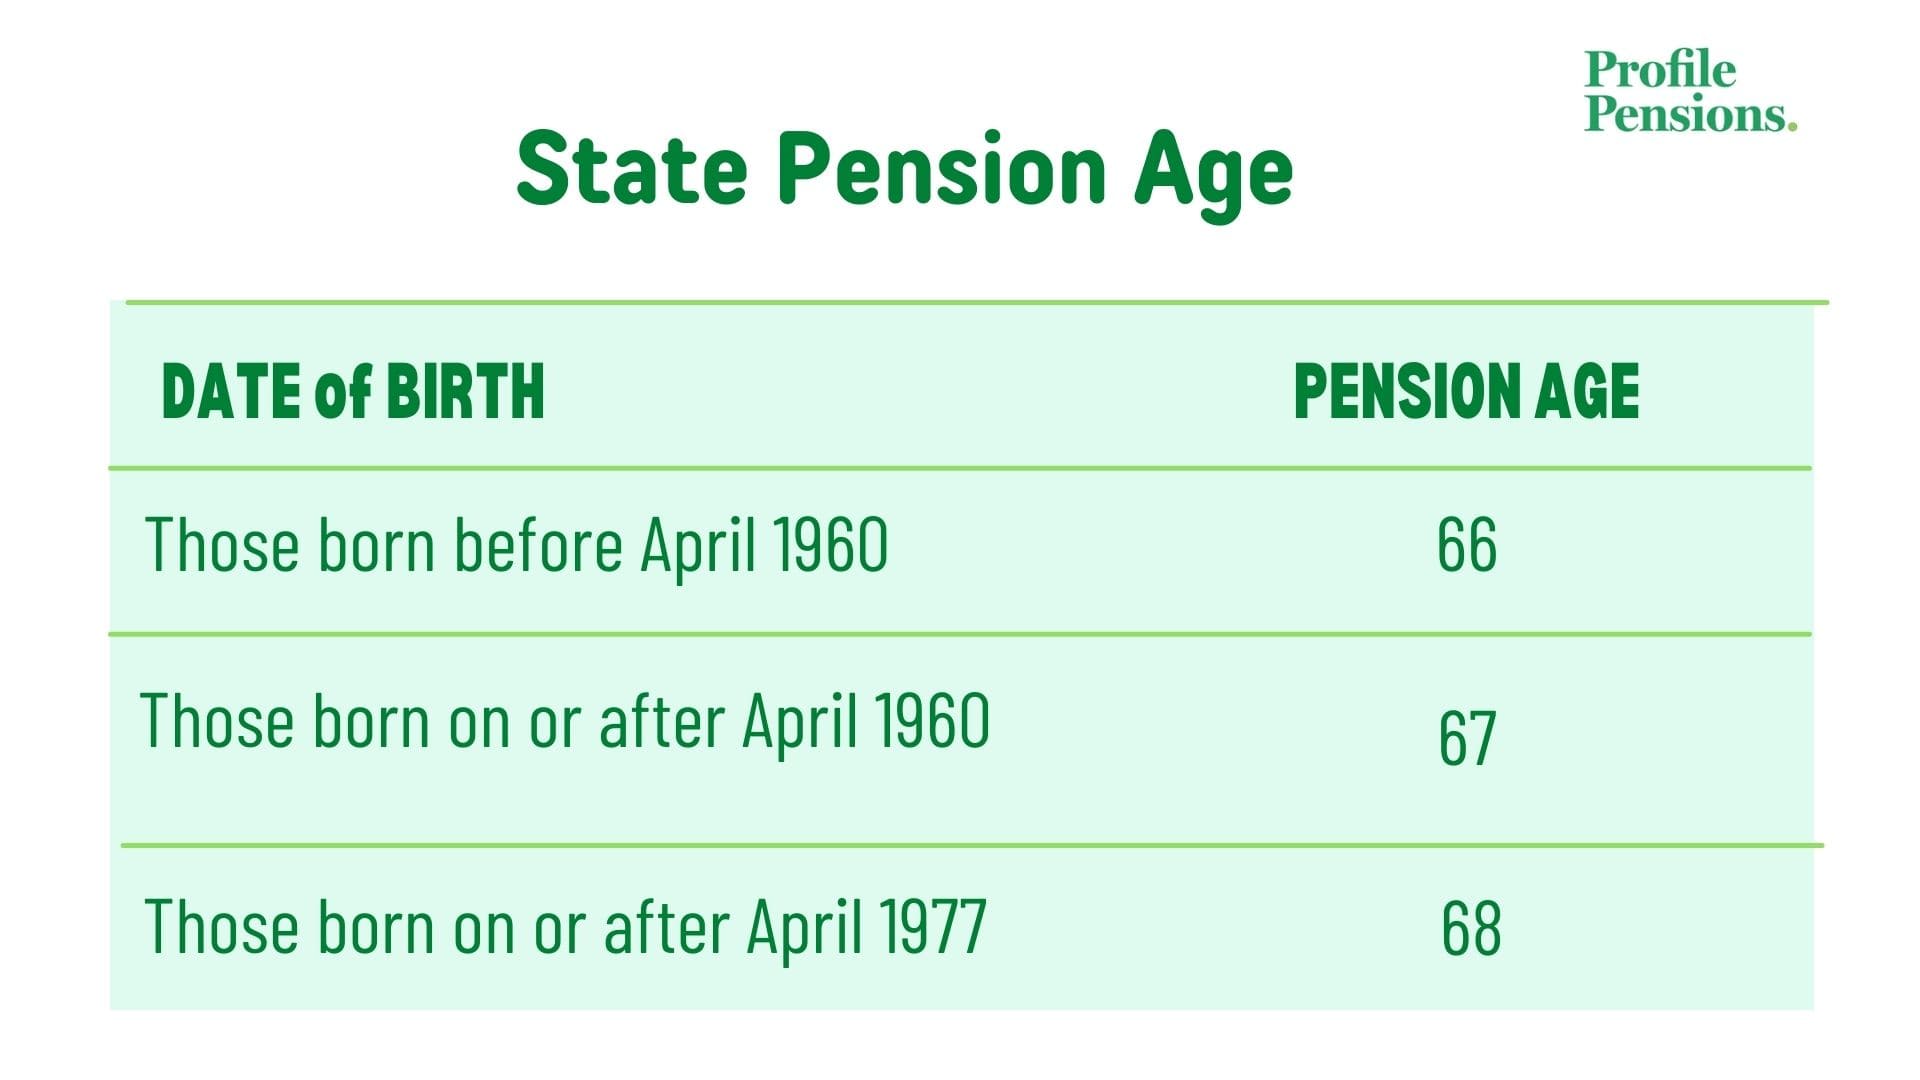
Today, for most women, the state pension age is creeping up to 66, and soon 67. Yes, it’s like the universe is telling you to keep those walking shoes handy a little longer.
Quick Cheat Sheet by Birth Year
Born between 6 April 1970 and 5 April 1978? Your state pension age is 67. Yep, you’ll be waiting until your late 60s to get that cheque—sorry, direct deposit.
Born after 6 April 1978? Brace yourself—it’s 68. I know, I know. But hey, think of all the extra time you’ll have to perfect your sourdough starter.
The government’s official tool (gov.uk/check-state-pension-age) is your bestie here. Punch in your date of birth, and it’ll tell you exactly when the pension fairy knocks.
What About the New State Pension (2016+)?
If you reached state pension age after 6 April 2016, you’re on the new state pension. It’s like the fancy, streamlined version—more predictable, but still a bit fiddly.
The full amount is currently about £221.20 a week (as of 2025). But here’s the kicker: you need 35 qualifying years of National Insurance contributions to get the full whack.
Fewer years? You get less. More years? Lucky you—but you won’t earn extra beyond 35. It’s like a loyalty card that maxes out faster than you’d like.
The National Insurance Gap Trap
If you took time off to raise kids or care for someone, you might have gaps in your National Insurance record. Don’t worry—National Insurance credits can fill those holes.

You can claim credits for child benefit if you’re under 12 and caring for a child, or for being a carer. It’s like getting a free pass for life’s detours—grab it.
Check your record online. Seriously, it’s easier than deciding what to watch on Netflix. A few clicks, and you can see if you’re on track or need to top up with voluntary contributions.
But Wait—What If I’m Married or Divorced?
If you’re married or in a civil partnership, you might be able to claim a pension based on your partner’s record. But this only applies if you reached state pension age before 6 April 2016.
For the new system, it’s all about your own record. So being a power couple won’t boost your pension—sadly, no romantic pensions here.
Divorced? Your ex’s contributions can help if your marriage ended and you haven’t remarried before pension age. It’s a little legal hug from the past.
When Does the Money Actually Arrive?
Your state pension doesn’t start the day you turn 66—it starts the first day of the next full week after your birthday. So if you’re born on a Wednesday, you wait until the following Monday.
Think of it as the universe’s way of testing your patience. You’ve waited decades—what’s four more days?
You’ll get payments every four weeks, directly into your bank account. No more chasing cheques in the rain.
You Can Delay It (For Fun and Profit)
Don’t need the cash right away? You can defer your state pension. Every week you delay adds a little extra—like compound interest for grumpy cats.
Delaying for a year boosts your weekly payment by about 5.8%. That’s enough for an extra latte or two each week—totally worth the wait.
But be careful: if you defer while still working, you might pay tax on the boosted amount. Talk to a financial advisor, or just ask your mate who’s really good at spreadsheets.
One Last Curveball: The 1950s Women
Women born in the 1950s got hit hardest by the changes. The pension age jumped from 60 to 66 in a few years, leaving many caught off guard. It’s like planning a beach holiday and ending up in a ski resort—confusing and a bit chilly.
The government did a review and offered some transitional payments in 2024. Check if you’re eligible—it’s not a full refund, but it’s a nice “we’re sorry” gift card.
If you’re in this group, do not bury your head in the sand. Call the Pension Service or visit a citizens advice bureau. They’re surprisingly nice when you’re not shouting at them.
The Uplifting Bit (You Made It!)
Look, the state pension is a safety net, not a golden parachute. But it’s your safety net, woven from years of work, caring, and surviving Mondays. That’s nothing to sneeze at.
Every woman deserves a retirement that feels like a long, happy sigh. Whether you’re knitting, traveling, or just sleeping in until 10 AM, you’ve earned it.
So grab that calculator, check your birth year, and smile. The pension is coming—eventually. And when it does, it’ll feel like winning a slow-motion lottery, paid out in weekly giggles and cups of tea. You’ve got this.