
What Happens To Your Pension If You Die Before Retirement

Let’s talk about death. Specifically, your death. Before you say “yikes,” hear me out. It’s actually pretty interesting (and a little hilarious) what happens to your pension if you kick the bucket before collecting a single dime.
The Big, Grim Question
You spend decades stuffing money into a pension pot. It’s magic money you can’t touch until you’re old and gray. Then, poof—you die at 59. What happens to that fat stack of cash? Good news: it doesn’t just evaporate into the ether.
That pile of savings is yours. Your pension is not a vampire that dies when you do. It’s more like a stubborn cat—it definitely has a will of its own.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The “Free Money” Myth
Many assume the pension company just pockets your cash. That’s deliciously wrong. The government loves rules about this stuff. They want your money to go somewhere—usually to someone you love or someone you mildly tolerate.
But here’s the kicker: it depends entirely on what kind of pension you have. Think of it like choosing your death date’s wardrobe—totally different outfits for different plans.
Your Defined Contribution Pension (The Rolling Suitcase)
This is the most common one today. It’s like a big suitcase you pack yourself. You saved it, you invested it. Your family inherits it, no questions asked.
If you die before touching it, that lump sum goes to whoever you named as beneficiary. Your brother, your best friend, your cat (if you put them on the form). It’s your money, and the taxman wants a tiny piece, but your kin get the rest.
Quirky fact: In the UK, if you die before age 75, that entire pot is tax-free for the beneficiary. That’s right—they get a fat, untaxed check. Your death becomes their windfall. Fun for them, awkward for you.

What About Defined Benefit Pensions? (The Ancient Promise)
This is a classic “gold watch” pension. You get a monthly check for life. But you died too soon. Now what? These plans are stingier. They usually give nothing to your family unless you signed up for a survivor’s benefit.
If you chose the “single life” option (paying you more while alive), your spouse gets zilch. Cue sad trombone. If you chose the “joint life” option, your partner keeps getting a reduced check. You basically paid for their future wine budget with a lower pension today.
Funny detail: Some plans force you to decide years before you die. It’s like booking a hotel room in 1998 for a trip you might take in 2040. “Would you like the breakfast option for your ghost?”
The Spouse Trap (And Tax Trick)
Spouses usually get first dibs. No spouse? Children get a slice. No children? It goes to your estate, which is basically a big legal blender that outputs cash to whoever your will says.
Here’s the wild part: pensions often bypass your will entirely. They have their own little will called a “nomination form.” If you forgot to update it after divorcing your ex, guess what? Your ex gets the money. Oops. That’s a great way to haunt someone—financially.
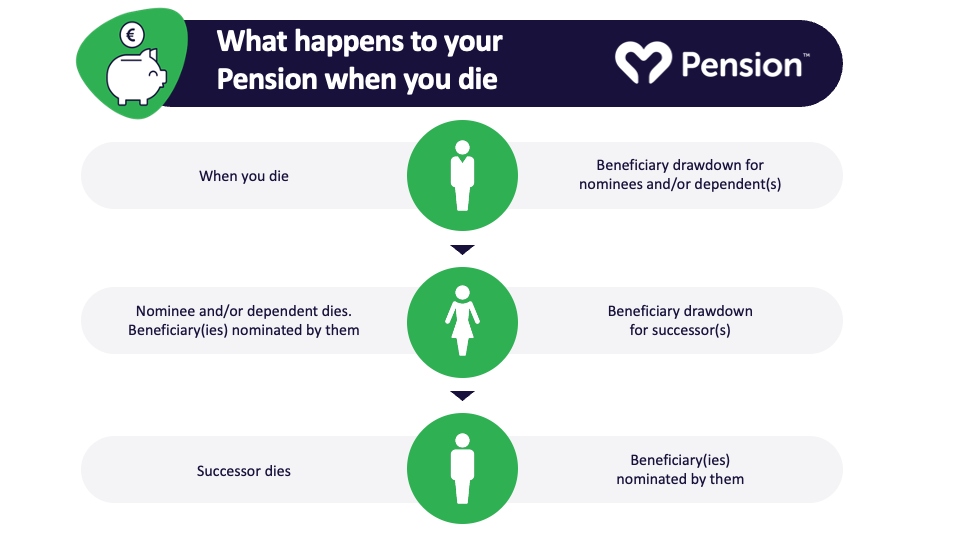
The “Gift That Keeps on Giving”
Some pensions let you take a lump sum cash-out before retirement. If you die in the middle of that process? Chaos. The money might be considered a “debt to the estate.” Your heirs get to argue with the pension company about whether you actually clicked “submit.”
Quirky fact: In Australia, the term is “death benefit.” It sounds morbid, but it’s basically a retirement account with a parachute. And in Canada, if you die with a locked-in pension, the government might force your spouse to buy a new annuity. Bureaucracy loves a sequel.
The Takeaway (Don’t Panic)
You won’t lose your pension to the “great void.” It will go somewhere. The real lesson? Fill out your beneficiary forms. Now. Go dig them out of your sock drawer or your email archive.
Also, consider this: dying before retirement is a financial teachable moment. It means you never have to watch your 401(k) tank during a recession. Silver lining! You beat the system by checking out early.
So relax. Your pension is fine. It’s waiting for your loved ones to have a very weird, slightly lucrative day. And remember—you can’t take it with you. But you can leave it behind in a tax-efficient, bureaucratic, and surprisingly funny way.