
Uk Government Announces 40 Loan Scheme For New Home Buyers

The UK government just dropped a plot twist that might make renting feel a little less like a bad rom-com sequel. Announced this week, a fresh 40 Loan Scheme for new home buyers is designed to help first-timers step onto the property ladder without selling a kidney. Think of it as the financial equivalent of a supportive friend who spots you for takeaway—except this loan covers up to 40% of the purchase price on new-build homes.
Here’s the gist: you buy a newly built house, and the government effectively becomes a silent investor. You don’t pay interest on the loan for the first five years, and you only repay when you sell the property or after 25 years. It’s equity loan meets the “buy now, panic later” vibe, but with a safety net that actually makes sense.
How does this actually work?
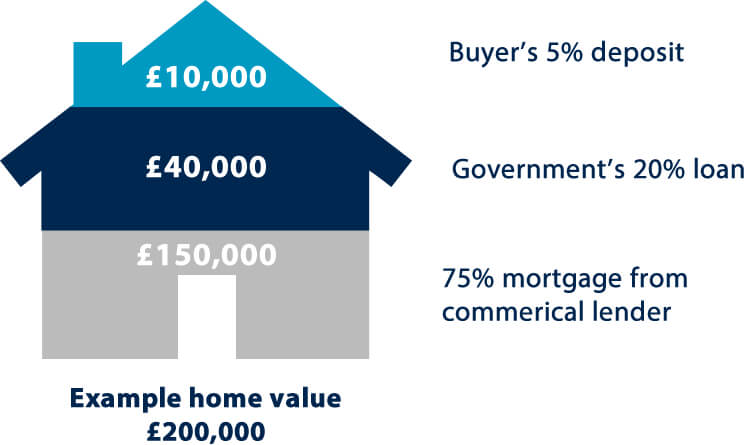
The scheme, officially part of the expanded Help to Buy initiative, targets first-time buyers with a 5% deposit. Instead of scrambling for a massive down payment, you chip in your 5%, get a standard mortgage for 55%, and the government loans you the remaining 40% via an equity loan. No interest on that slice for the first half-decade—just pure, sweet breathing room.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Of course, there’s a catch—because life isn’t an IKEA flat-pack that assembles without a fight. The loan applies only to new-build homes priced under £600,000 (or £300,000 in some regions). Think of it as the government’s way of saying, “We’ll help you buy a shiny new flat, but not that Victorian fixer-upper on Pinterest.”
Practical tip: The deposit dance
Still need to stash that 5%? Try the “coffee cup challenge”—skip one latte a day for a year and you’ll save around £900. Pair that with a Lifetime ISA (which adds a 25% government bonus) and you’re closing in on that deposit faster than a Deliveroo rider on a Friday night. Fun fact: The average first-time buyer deposit in the UK is now 15%, so this scheme slashes that requirement to a fraction.
Another hack: negotiate with developers. Many new-build brokers offer deposit contributions or legal fee waivers if you use their recommended solicitor. Don’t be shy—ask for it like you’re haggling at a car boot sale for a vintage vinyl.
The cultural angle: Owning vs. renting
Let’s be honest—renting in the UK has become the housing equivalent of dating a guy who still lives with his ex. The average rent in England hit £1,200 a month in 2023, while a mortgage on a similar property could be £800. This scheme isn’t just about buying a home; it’s about buying stability. Remember the scene in Notting Hill where Hugh Grant’s character lives in a charming but precarious flat? That’s the vibe this scheme tries to avoid—except you won’t have to share your bathroom with a sardonic Welshman.
Also, fun little fact: The original Help to Buy scheme helped over 350,000 households since 2013. That’s more people than the entire population of Newcastle. So yes, you’re joining a pretty big club.
Practical tip: Know your numbers
Before you start browsing Rightmove at 2 a.m. (we’ve all done it), get a Decision in Principle from a lender. This tells you how much you can borrow without a credit check ding. Also, factor in stamp duty—first-time buyers get relief on homes under £625,000, but new-build often attracts full rates. Use a stamp duty calculator like it’s your new best friend.
Don’t forget ground rent and service charges for flats. Those “affordable” new developments sometimes come with fees that creep up like a subscription you forgot to cancel. Ask the developer for a full breakdown before you sign.
The fine print: What could go wrong?
If you sell the property before 25 years, you repay the loan as a percentage of the sale price, not the original amount. So if your home goes up in value (say, from £200k to £250k), you owe the government £100k instead of £80k. It’s a gamble—like betting on a horse named “House Prices Only Go Up.” Historically, they do, but never say never.
Also, you can’t rent out the property or use it as a holiday home. The scheme is for owner-occupiers only. Imagine buying a gorgeous flat in Manchester, then realizing you can’t Airbnb it during the Eurovision final. Tragic, but fair.
Practical tip: The exit strategy
Plan to make overpayments on your mortgage during the first five years, because the government loan is interest-free. That chunk of cash you save on rent? Put it toward the mortgage principal. Fun fact: Overpaying just £100 a month on a £200k mortgage could save you over £15k in interest over 25 years. That’s a nice holiday to Bali—or a deposit on a second property.
Also, shop around for lenders who specialize in equity loan mortgages. Some big banks love this scheme; others treat it like a suspicious stain on a carpet. A good broker is worth their weight in tea and biscuits.
Reflection: A daily life lens
Last night, I unlocked my front door (a rented flat with a sticky lock) and realized the key to feeling “home” isn’t the address—it’s the freedom to paint a wall without asking a landlord. This loan scheme isn’t a magic wand; it’s a stepping stone. It whispers, “You can have a garden, a mortgage, and a cat named Gerald.” And honestly, in a world where everything feels rented—from movies to WiFi—owning a little chunk of earth matters.
So go ahead, open that spreadsheet, calculate the 5% deposit, and dream about the shelf where you’ll display your succulents. The door is ajar. The 40 Loan Scheme just handed you the key—it’s up to you to turn it.