
Savers Are Moving Record Funds Into Tax-free Accounts Rapidly
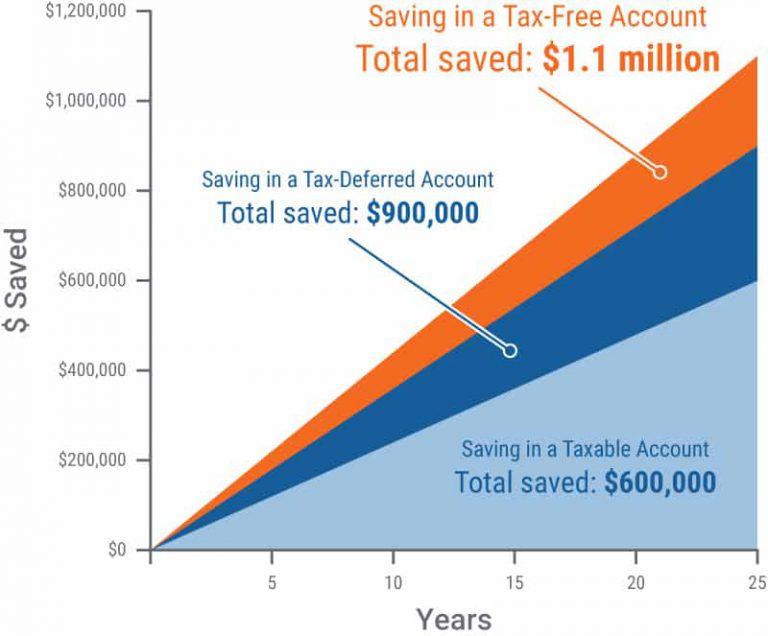
My buddy Mark called me last week, practically giddy. He’d just moved his entire emergency fund—a sum he usually guards like a dragon hoarding gold—into a tax-free account. "I know, I know," he said, "but the fear of missing out on those gains is stronger than the fear of a leaky roof right now." I laughed, but then I checked the latest data, and Mark isn't alone. He’s part of a quiet, massive tidal wave.
Savers are moving record funds into tax-free accounts at a pace we haven't seen in years. We're talking billions, not just spare change from couch cushions. It’s like everyone suddenly woke up and realized that Uncle Sam’s slice of their pie is getting way too generous.
The numbers are staggering, and frankly, a little ironic. Remember when saving money felt like a boring chore? Like eating your financial vegetables? Now it’s a hot new hobby. People are treating these accounts like a Black Friday sale where the discount is 0% future tax.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
Why the big rush? It’s not just high interest rates.
Sure, higher yields are part of the story. A 5% return on a savings account sounds nice, but a 5% return you never have to pay tax on? That’s the real magic trick. That after-tax return suddenly becomes the belle of the ball.
But let’s be real: there’s also a healthy dose of paranoia driving this. People see the national debt, hear about potential tax hikes down the line, and think, "I better lock in my gains now before they come for my lunch money." Can you blame them? I can almost hear them whispering, "You can have my old 401(k) match, but this Roth IRA is mine, all mine!"
The shift is so dramatic that banks and brokerages are scrambling. They’re offering bonuses, slashing fees, and sending out cheerful emails that sound like they’re selling you a dream vacation. "Open an ISA (or Roth IRA in the U.S.) and feel the financial freedom!" they chant. And we’re clicking "accept" faster than a teenager on a free app offer.

The "Stealth" Millionaire Moves
What fascinates me is who is moving the money. It’s not just the high-flying investors. It’s your neighbor the teacher, the guy who fixes your car, and that friend who still uses a flip phone. They’re all shoveling cash into vehicles like a Cash ISA or TFSA (if you’re in Canada). They’ve realized that the best tax break is the one you don’t have to file paperwork for.
One survey I saw noted that a huge chunk of these new deposits are coming from "emergency funds." You know, the traditional "six months of expenses" that used to sit in a boring 0.1% account? Yeah, that money is on the move. People are treating their tax-free wrapper like a high-velocity savings closet.
And here’s the kicker—which might make you chuckle: Some financial planners are actually worried. They say, "What if people need that money quickly and the market dips?" To which the average saver replies, "Have you seen my grocery bill? I need all the help I can get, risk be darned!"
The fine print (there’s always fine print)
Let’s be honest for a second. Not all tax-free accounts are created equal. Some have contribution limits. You can’t just dump a winning lottery ticket into them (though, please invite me if you do). And if you over-contribute? The taxman will give you a stern, cold stare and probably a penalty fee.
But the mass psychology here is crystal clear: people are betting that taxes will be higher in the future. They’re making a preemptive strike. "I’ll take my 20% tax rate today on my regular earnings, but this pile of savings? Oh no, not this pile. This pile is destined for tax-free islands of bliss."
The other irony? We’re doing this rapidly. It’s not a slow, considered march. It’s a stampede. The speed suggests a collective "click-before-I-change-my-mind" impulse. You know what that feels like, right? That split-second where you hit "transfer" and a little thrill runs down your spine.
So, what does this mean for you? Well, if you haven’t moved your funds yet, you’re probably the one person at a party who isn’t dancing. And that’s totally fine. But the crowd is telling you something: they really, really hate future tax bills. They’re voting with their wallets—and their wallets are sprinting towards that lovely, protected tax-free harbor.
Just remember: the grass isn’t always greener. But when it’s tax-free? It’s a lovely shade of emerald. And for now, that’s a shade everyone wants in their garden.