
Gov.uk Stamp Duty Land Tax Residential Property Rates England 2026
So, my mate Dave bought a flat last year. He was so chuffed, sending me photos of the "characterful" (read: wonky) fireplace and the garden that was mostly dandelions. Then, a month later, he was sobbing into his pint over something called "Stamp Duty." I didn't get it then. But now, looking at the 2026 rates for England? Oh, Dave. Oh, mate.
The Great Tax Reset: What Actually Changed?
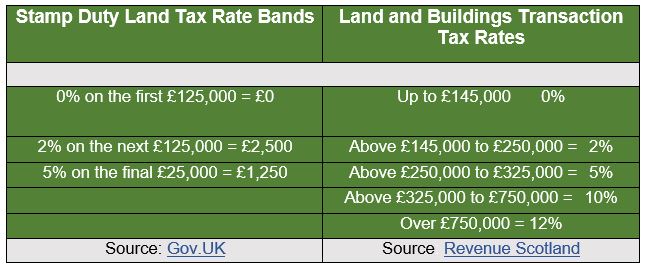
Remember when the nil-rate band was a bit of a safety net? Well, 2026 is the year the government decided to tighten the purse strings. From April 2025, the threshold for first-time buyers dropped from £425,000 back down to £300,000. And for everyone else? That zero-percent slice of the pie shrunk from £250,000 to a far more humble £125,000.
This isn't a minor tweak; it's a seismic shift for anyone thinking of climbing the property ladder. If you’re buying a home for, say, £350,000 in 2026, you’re suddenly paying tax on over two hundred thousand quid of that price. Ouch.
Must Read
- Did Kelly Clarkson Just Get Julia Roberts Treatment? The Untold Truth Behind Brooklyn’s $15m Animatronic Bird Drama
- The 5-minute Visit That Broke The Internet: How Kelly Clarkson Sparked A $15 Million Mechanical Bird War
- Petty Revenge Or Viral Genius? Brooklyn Store Slaps $15,000,000 Tag On Molly The Bird After Kelly Clarkson Backlash
The "Moving House" Penalty (Yes, It's a Thing)
Here’s where it gets spicy for people who aren't first-time buyers. The government loves to call this a "progressive" tax, but let’s be real: it’s a lump-sum headache right when you need cash for a new boiler. The rates still climb in slabs: 2% on the portion from £125,001 to £250,000, then 5% up to £925,000.
But the real killer is the surcharge for second homes and buy-to-let investors. That’s an extra 3% on top of every single band. So if you’re a landlord buying a £300,000 flat, you’re paying 5% on the first chunk and then 8% on the next. It’s designed to cool the market, but it also punishes reluctant landlords who inherit a property.
Think about it: you finally sell your starter flat to move into a family home, and the tax bill just doubled compared to last year. That’s money you were hoping to put toward a new sofa. Or, you know, groceries.
First-Time Buyers: The Tiny Silver Lining
If you’re a first-time buyer, don’t despair completely—the government hasn’t forgotten you entirely. You still get relief on the first £300,000 of a purchase (up to £425,000 for the full relief). So if you’re buying a £300,001 flat, you pay 5% on that single pound. No, really. It’s a weird quirk.

But here’s the rub: in 2026, the average first home in London is still over £500,000. That means you’re paying 5% on the chunk between £300,000 and £500,000, plus 10% on anything above that up to £625,000. It’s progress, but it feels like a cruel math joke.
My advice? If you’re a first-timer, look for a property just under the £425,000 threshold. Seriously, haggle like your life depends on it. You’ll save thousands in tax that would otherwise vanish into the Treasury’s pocket.
The "Non-Resident" Trap (Don't Ignore This)
Oh, and if you’re reading this from abroad? The taxman really wants your attention. Non-UK residents already pay a 2% surcharge on top of everything. So on a £500,000 house, you’re looking at rates starting at 5% and climbing. It’s a deterrent, plain and simple, designed to stop overseas cash flooding into our housing market.
But here’s the irony: it mainly hurts Brits moving back home after a few years working overseas. You’d think "returning to your homeland" would get a discount. Nope. Thanks, HMRC.
Real-World Numbers: Let’s Do the Cringe Math
Let’s say you’re a "home mover" (not a first-time buyer) buying a typical semi-detached for £375,000 in 2026. Here’s your bill: nothing on the first £125,000, then 2% on the next £125,000 = £2,500, and 5% on the remaining £125,000 = £6,250. Total: £8,750.

Now compare that to 2024, when the nil-rate band was £250,000. Back then, you’d have paid only 5% on £125,000 = £6,250. That’s an extra £2,500 just for the privilege of buying a home two years later. It feels almost personal, doesn’t it?
And if you’re buying that same £375,000 home as a second property? Add 3% on every band. That’s £3,750 on the first chunk, £6,250 on the next, and a whopping £18,750 total. Yes, you read that right. Eighteen grand to own a second home. You could buy a small car with that.
The Verdict: Plan Ahead or Pay the Piper
So, what do we do with this? You can’t avoid Stamp Duty entirely (unless you’re buying a houseboat or a mobile home—seriously, those are exempt). But you can game the system a little. If you’re close to a threshold, negotiate the price down. Even £500 below a band can save you thousands in percentage fees.
Also, consider timing. If you’re buying in early 2026, you’re already past the temporary cuts. But if you can wait until after a potential budget change? Keep an eye on the news. Chancellors love to surprise us.
In the end, my mate Dave learned the hard way. He now has a lovely flat, a dandelion garden, and a permanent scowl every time he sees a letter from HMRC. Don’t be Dave. Know the rates, do the math, and never, ever assume the taxman is on your side.